

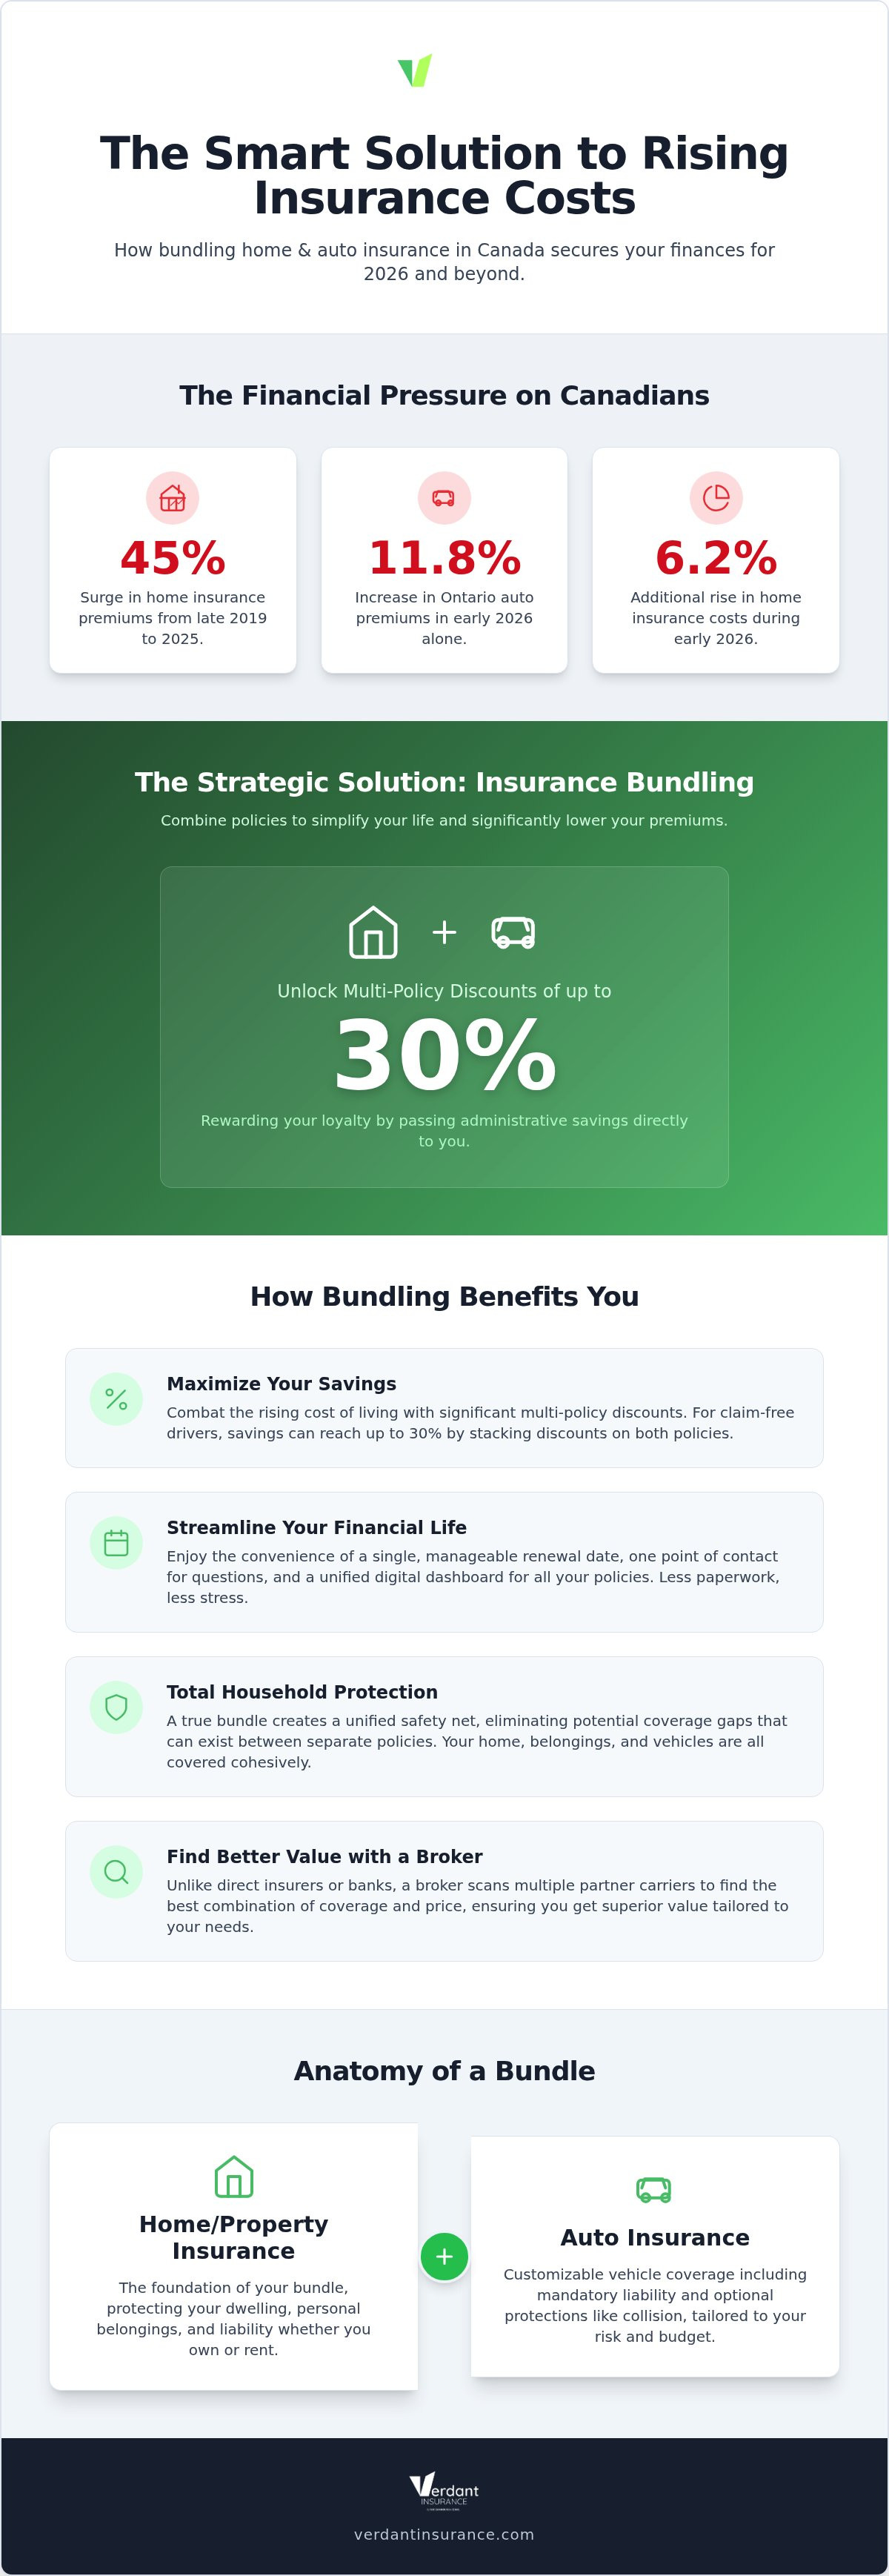
Did you know that Canadian home insurance premiums climbed by a staggering 45% between late 2019 and 2025? With the cost of living continuing to rise through 2026, it often feels like your monthly budget is under constant siege. It's exhausting to manage separate policies, confusing jargon, and various renewal dates while worrying if you're actually covered when it matters most.
We understand that you're looking for clarity and real relief. You deserve a solution that protects your family without draining your bank account. By choosing home and auto insurance bundles Canada, you can simplify your financial life and unlock premium discounts of up to 30%. It's about working smarter, not just paying less, to keep your future secure.
This guide provides our comprehensive 2026 bundling checklist to help you streamline your coverage. You'll discover how to secure a single, manageable renewal date and find a trustworthy broker to handle the heavy lifting. We've broken down the steps to make your path to savings feel effortless and transparent.
Key Takeaways
- Discover how a multi-policy discount rewards your loyalty and helps you combat the rising cost of living in Canada.
- Learn to streamline your financial life by aligning your homeowner or tenant coverage with your vehicle policy for one easy renewal date.
- Master the 10-point checklist for home and auto insurance bundles Canada to ensure you're fully protected while maximizing your savings.
- Understand the broker advantage and how scanning multiple partner carriers leads to better value than traditional bank-owned insurance.
- Follow our simple roadmap to switch policies effortlessly using modern online tools that do the heavy lifting for you.
Why Bundling is the Smartest Financial Move for Canadians in 2026
Living in Canada right now means watching your monthly expenses climb at an uncomfortable pace. With Ontario auto premiums rising by 11.8% and home insurance up by 6.2% in early 2026, finding ways to reduce fixed costs is a necessity. Choosing home and auto insurance bundles Canada is a proactive way to push back against these inflationary pressures. It's not just about a smaller bill; it's a strategic move to secure your household's financial future.
Insurers offer a "Multi-Policy Discount" because it makes their operations more efficient. It costs them significantly less to manage one client with two policies than two separate clients. They pass those administrative savings directly to you as a reward for your loyalty and stability. When you secure home and auto insurance bundles Canada, you're signaling to the insurer that you're a long-term partner. This concentration of risk allows them to offer more competitive rates than you'd find by shopping for individual, fragmented policies.
Think of it as "Total Household Protection" rather than a collection of scattered documents. Before diving into the numbers, it helps to understand the basics. What is property insurance? It's the foundation of your home coverage, protecting your dwelling and your personal belongings. By combining this with your auto policy, you eliminate coverage gaps and ensure you have one point of contact for any questions. This simplicity saves you time and reduces the mental load of managing your protection.
The 'Bundle & Save' Math: More Than Just a Percentage
Many people assume bundling is a flat discount, but it's actually more rewarding. Insurers use "stacking" logic where the discount applies to both the home and auto portions of your premium separately. For claim-free drivers in Ontario, this return on investment is even higher. At Verdant, we help claim-free clients unlock tiers of savings that can reach up to 30%. There's a big difference between a true bundle and just having two policies with the same company; a true bundle integrates your data to lower your overall risk profile and premium cost.
Simplifying Your Digital Paperwork
Managing your life through a single digital dashboard is a massive relief. Instead of hunting for two different login codes or tracking separate renewal dates, everything lives in one secure place. As your broker, we handle the coordination between your different policy types so you don't have to worry about the details. Insurance bundling is a strategic consolidation of risk for a lower premium. This modern approach ensures your coverage evolves as your life does, making your insurance experience feel effortless and transparent.
The Anatomy of a Bundle: What’s Included and How it Works
A bundle is more than a simple price cut. It's a structural link between your vehicle and your residence. Whether you own a house or rent an apartment, home and auto insurance bundles Canada provide a unified safety net. This arrangement typically combines your property coverage with your vehicle's mandatory and optional protections, ensuring no part of your life is left vulnerable to unexpected events.
This "Total Household Protection" model works by grouping different risks under one administrative roof. By doing this, you eliminate redundant fees and simplify your communication. It's helpful to weigh the pros and cons of bundling to ensure it aligns with your specific financial goals for 2026. For most Canadians, the convenience of a single point of contact far outweighs the effort of managing separate providers.
Auto Insurance Components in the Bundle
Ontario's auto insurance landscape underwent significant reform on July 1, 2026. While medical and rehabilitation benefits remain mandatory, many other benefits like income replacement and caregiver support are now optional. This makes choosing customizable car insurance policies more important than ever. You can now tailor your liability and collision coverage to fit your specific risk tolerance and budget.
Strategic bundling allows you to adjust deductibles across both policies to find the perfect balance. For instance, increasing your collision deductible might lower the total cost of the entire bundle. While many traditional bank-owned insurers offer a modest 10% or 15% discount, we focus on helping claim-free and conviction-free drivers in Ontario unlock savings as high as 30%. Your clean driving record is your strongest tool for lowering your overall household expenses.
Home and Property Protection
The home portion of your bundle covers the physical structure, your personal belongings, and legal liability. Understanding the average cost of home insurance Ontario helps you see exactly where a bundle provides the most relief. For those just entering the property market, home insurance for first time buyers is the ideal moment to establish a bundled relationship that grows with you.
Renters can also take advantage of these savings by bundling tenant insurance with their auto policy. This provides the same logistical ease and multi-policy discounts as a standard homeowner bundle. You can also add "Endorsements" or riders for specific high-value items like jewelry or sewer backup protection. These additions benefit from the same streamlined management as your core policies. If you're ready to see how these pieces fit together, you can explore your bundled options online to find a plan that feels just right.
The Essential 10-Point Bundling Checklist for 2026
Switching your protection plan requires more than a quick signature. To truly maximize the benefits of home and auto insurance bundles Canada, you need a methodical approach. This 10-point checklist ensures you don't leave money on the table or leave your assets exposed. It's about moving beyond basic discounts to find a strategy that fits your life in Ontario.
Start with your timing. Audit your current renewal dates first. Cancelling a policy mid-term can lead to short-rate cancellation fees that eat into your savings. Next, confirm your "Claim-Free" status. While many big banks offer a generic 10% discount, we help claim-free and conviction-free drivers in Ontario unlock a much more significant 30% discount tier. This is often the difference between a good deal and a great one.
Always compare combined quotes against standalone options using a digital broker. This transparency ensures the bundle is actually the better deal for your specific postal code. You should also verify that your liability limits are consistent across both policies to avoid legal gaps. Finally, look for "Single Deductible" features. This means if a single event, like a severe Ontario windstorm, damages both your roof and your car parked in the driveway, you only pay one deductible instead of two.
Evaluating Coverage Quality
Replacement cost is a non-negotiable for your home contents. It ensures you get the current market price for your items rather than a depreciated amount. On the auto side, confirm your policy includes "Loss of Use" coverage. This provides a rental vehicle while yours is being repaired after an accident. Safe drivers should also ask about "Disappearing Deductibles." These programs reward your years of careful driving by lowering your out-of-pocket costs every year you remain claim-free.
Provider and Service Verification
The best home and auto insurance bundles Canada are backed by people, not just algorithms. Check your broker's reputation for dedicated support. You want a proactive guide who knows your history, not a random call center agent who treats you like a policy number. Lastly, test the online interface. The policy management tools should be intuitive and fast, allowing you to make changes or download your digital pink slips in seconds. This ease of use is a core part of the "Friendly Expert" experience we aim to provide at Verdant.
Broker vs. Direct Insurer: Finding the Best Value in Ontario
When you search for insurance through a bank or a direct carrier, you only see one piece of the puzzle. These institutions present their fixed rates; if those numbers don't fit your budget, you're forced to start your search from scratch. A broker operates with a different philosophy. We act as your proactive guide, scanning a network of partner carriers to find the perfect marriage between your vehicle and property policies. This is the most effective way to secure home and auto insurance bundles Canada because it forces multiple companies to compete for your business.
A persistent myth suggests that working with a broker adds an extra layer of cost to your monthly bill. In reality, brokers are compensated by the insurance companies, not by the policyholders. You receive expert advice and a customized protection plan without paying a surcharge for the service. Beyond the initial savings, you gain an advocate who stands in your corner during the claims process. Having a professional to handle the heavy lifting provides a level of peace of mind that a faceless call center cannot replicate.
Ready to see how much you can save with a personalized approach? Connect with an Ontario broker today to start your customized quote.
Why Ontario Residents Benefit from Local Brokerage
Ontario features a unique regulatory environment overseen by the Financial Services Regulatory Authority (FSRA). These provincial rules directly influence how your premiums are calculated and what benefits are available to you. Local brokers understand these nuances deeply. We also monitor how regional risks, such as GTA flooding or specific winter storm patterns, impact the pricing of home and auto insurance bundles Canada. This local expertise transforms a bureaucratic transaction into a supportive, human conversation.
Technology Meets Tradition
At Verdant, we've built a modern platform that brings the traditional broker experience into the digital age. You don't have to wait days for a callback or navigate stacks of confusing paperwork. Our online system speeds up the quoting process while maintaining a high degree of care and attention to detail. This solution-oriented support is vital when your life situation evolves. For instance, if you decide to expand your lifestyle by buying a cottage, we can seamlessly integrate that new asset into your existing bundle. We ensure your coverage stays as flexible and dynamic as your life in Ontario.
Step-by-Step: Switch to a Bundled Policy and Save
Moving your protection to a new provider doesn't have to be a logistical headache. While the prospect of "breaking up" with your current insurer might feel daunting, the process is remarkably straightforward when you have a clear roadmap. By following a few logical steps, you can transition to home and auto insurance bundles Canada and start seeing the financial benefits immediately. It's about taking control of your household budget with confidence and clarity.
Your first task is to gather your current "Declarations" pages for both your home and auto policies. These documents act as your coverage blueprint, listing your current limits, deductibles, and any specific riders you've added over the years. Once you have these in hand, you can use the Verdant online tool to input your details just once. Our platform is designed to be tech-forward yet human, allowing you to generate a combined quote in a fraction of the time it takes to call multiple banks. During this stage, you'll want to review the customizable options carefully. We make it easy to ensure your new bundle either matches or exceeds your existing protection levels so you never feel underinsured.
Timing Your Switch Perfectly
The most efficient way to switch is during your "Renewal Window," which typically opens 30 to 60 days before your current policy expires. This timing allows you to move to a new provider without facing mid-term cancellation fees or "short-rate" penalties. However, life isn't always perfectly synchronized. If your home and auto policies expire at different times, we can implement a staggered bundling strategy. This involves moving one policy now and setting the second to join the bundle automatically upon its expiry. Verdant handles the coordination to ensure no insurance gaps occur. This proactive management keeps you protected every single day of the transition.
Finalizing Your 30% Savings
To lock in that top-tier 30% discount, we'll help you verify your clean driving history through a Motor Vehicle Record (MVR) check. This step confirms your status as a low-risk driver, which is the primary key to unlocking maximum savings in Ontario. You can also stack smaller, "Easy Pay" discounts by setting up automated monthly payments from your bank account. This reduces administrative friction and ensures you never miss a deadline. Once you're satisfied with the plan, you can sign your new policy digitally from any device. The final step is notifying your old provider in writing to confirm your cancellation date. This clear communication prevents double-billing and ensures a smooth handoff. Ready to simplify your life? Get your personalized home and auto bundle quote today!
Secure Your Financial Future with Smarter Coverage
Managing your protection shouldn't be a source of constant stress or confusion. By aligning your coverage through home and auto insurance bundles Canada, you simplify your administrative life while locking in significant monthly savings. You now have the tools to move beyond fragmented policies and embrace a single, manageable renewal date. A proactive broker doesn't just find a lower rate; they act as a helpful ally who understands your unique needs in the Ontario market.
We've helped thousands of homeowners find peace of mind by connecting them with Canada's top insurance carriers through our modern, tech-forward platform. If you're a claim-free driver, those savings can reach as high as 30% of your total premium. It's time to stop overpaying and start benefiting from a more transparent, efficient way to protect what matters most to you. Choosing a bundle is a strategic step toward a more stable and predictable financial future.
Start Your Combined Home & Auto Quote and Save Up to 30%
You're now equipped with the checklist and the steps needed to make a strategic switch. We're ready to help you navigate the process so you can enjoy the comfort of knowing you're fully protected at the best possible value. Take that first step today and feel the relief of a simpler, more affordable insurance experience.
Frequently Asked Questions
Is it always cheaper to bundle home and auto insurance in Canada?
Yes, bundling is almost always the most cost-effective choice, but it's vital to compare. While most providers offer a discount, a specialized standalone policy might occasionally be cheaper for unique risks. However, for the majority of drivers and homeowners, home and auto insurance bundles Canada provide the best overall value by stacking discounts and reducing administrative fees. We always scan multiple partners to ensure your specific combination delivers the highest savings.
Can I bundle tenant insurance with my car insurance?
You certainly can bundle tenant insurance with your vehicle policy. This is an excellent way for renters to access the same multi-policy discounts typically reserved for homeowners. It simplifies your monthly budgeting by bringing both protections under one renewal date and one point of contact. This setup ensures your personal belongings and your car are protected while keeping your total premium as low as possible through a single, streamlined arrangement.
How much can I actually save by bundling in Ontario?
Most Ontario residents see a premium reduction of 10% to 15% just for combining policies. However, if you have a clean driving record and no recent property claims, those savings can reach up to 30%. These discounts apply to both the home and auto portions of your bill. This significant reduction helps offset the rising costs of living while ensuring your household remains fully protected by top-tier Canadian insurance carriers.
What happens if I need to cancel one part of the bundle later?
You have the flexibility to cancel one part of your bundle at any time, but doing so will remove your multi-policy discount. Your remaining policy will revert to its standard, standalone rate, which is usually higher. It's also important to check for any short-rate cancellation fees from the insurer if you're stopping a policy mid-term. We can help you calculate the impact of these changes to ensure you're making the best financial decision.
Will my rates go up if I have one claim on a bundled policy?
A single claim doesn't automatically mean your rates will skyrocket, especially if you have claim forgiveness coverage. This endorsement can protect your "claim-free" discount status after your first minor accident or property loss. While a claim might impact one side of your bundle, it typically doesn't remove the bundling discount itself. We'll help you review your policy to see how "claim-free" tiers are protected in your specific plan.
How do I sync renewal dates for my home and auto policies?
Syncing your dates is a straightforward process that we handle for you. We can set up a new policy to start exactly when your current one expires, or use a "pro-rated" approach to align a secondary policy with your main renewal date. This creates a single, manageable anniversary for all your insurance needs. It eliminates the hassle of tracking multiple deadlines and ensures your home and auto insurance bundles Canada remain seamless and gap-free.
Do I need to pay a fee to a broker like Verdant for bundling?
No, you never pay a direct fee to us for our services. As a broker, we're compensated by the insurance companies we partner with, not by our clients. This means you get expert advocacy, customized quotes, and dedicated support at no extra cost to you. Our goal is to find you the best value and the most comprehensive coverage, acting as your proactive guide through the entire process without any hidden surcharges.
Can I bundle insurance for my condo and my SUV?
Absolutely, condo insurance is a core component that can be bundled with any vehicle policy. This combination protects your unit's improvements, your personal contents, and your liability while securing a lower rate for your SUV. It's a popular choice for urban residents who want high-quality protection without the complexity of managing separate providers. This arrangement ensures your urban lifestyle is fully covered under one convenient and cost-effective umbrella.


