

What if your peaceful lakeside escape is actually carrying more risk than your primary residence in the city? Most Canadians view their retreat as a simple sanctuary, but insurance providers see a complex profile of seasonal vacancy and remote wilderness hazards. Finding competitive cottage insurance quotes Canada often feels like a chore when you'd rather be on the dock, especially when premiums climb for a property you only use part-time. You shouldn't have to worry about whether a burst pipe or a remote break-in is covered while you're away.
We believe your "happy place" deserves specialized care, not a one-size-fits-all policy. This guide shows you exactly how to compare cottage insurance quotes while demystifying the crucial differences between seasonal and secondary property classifications. You'll discover how to secure your boathouse, navigate the specific rules for short-term rentals like Airbnb, and leverage bundling to lower your annual costs. We're breaking down the "named perils" jargon into clear, actionable steps. By the end, you'll have a roadmap to protect your Canadian getaway for less, ensuring total peace of mind for every season ahead.
Key Takeaways
- Identify why a standard home policy extension is often insufficient for the unique risks of a remote Canadian retreat.
- Clarify whether your property qualifies as a seasonal or secondary residence to secure the right level of coverage and pricing.
- Master the process of comparing cottage insurance quotes Canada by focusing on key drivers like fire protection proximity and boathouse values.
- Unlock potential savings by bundling your seasonal property with your home and auto insurance for a simplified, cost-effective experience.
- Learn how working with a digital broker allows you to shop multiple carriers at once to find a customized policy for your specific needs.
What is Cottage Insurance and Why is it Different?
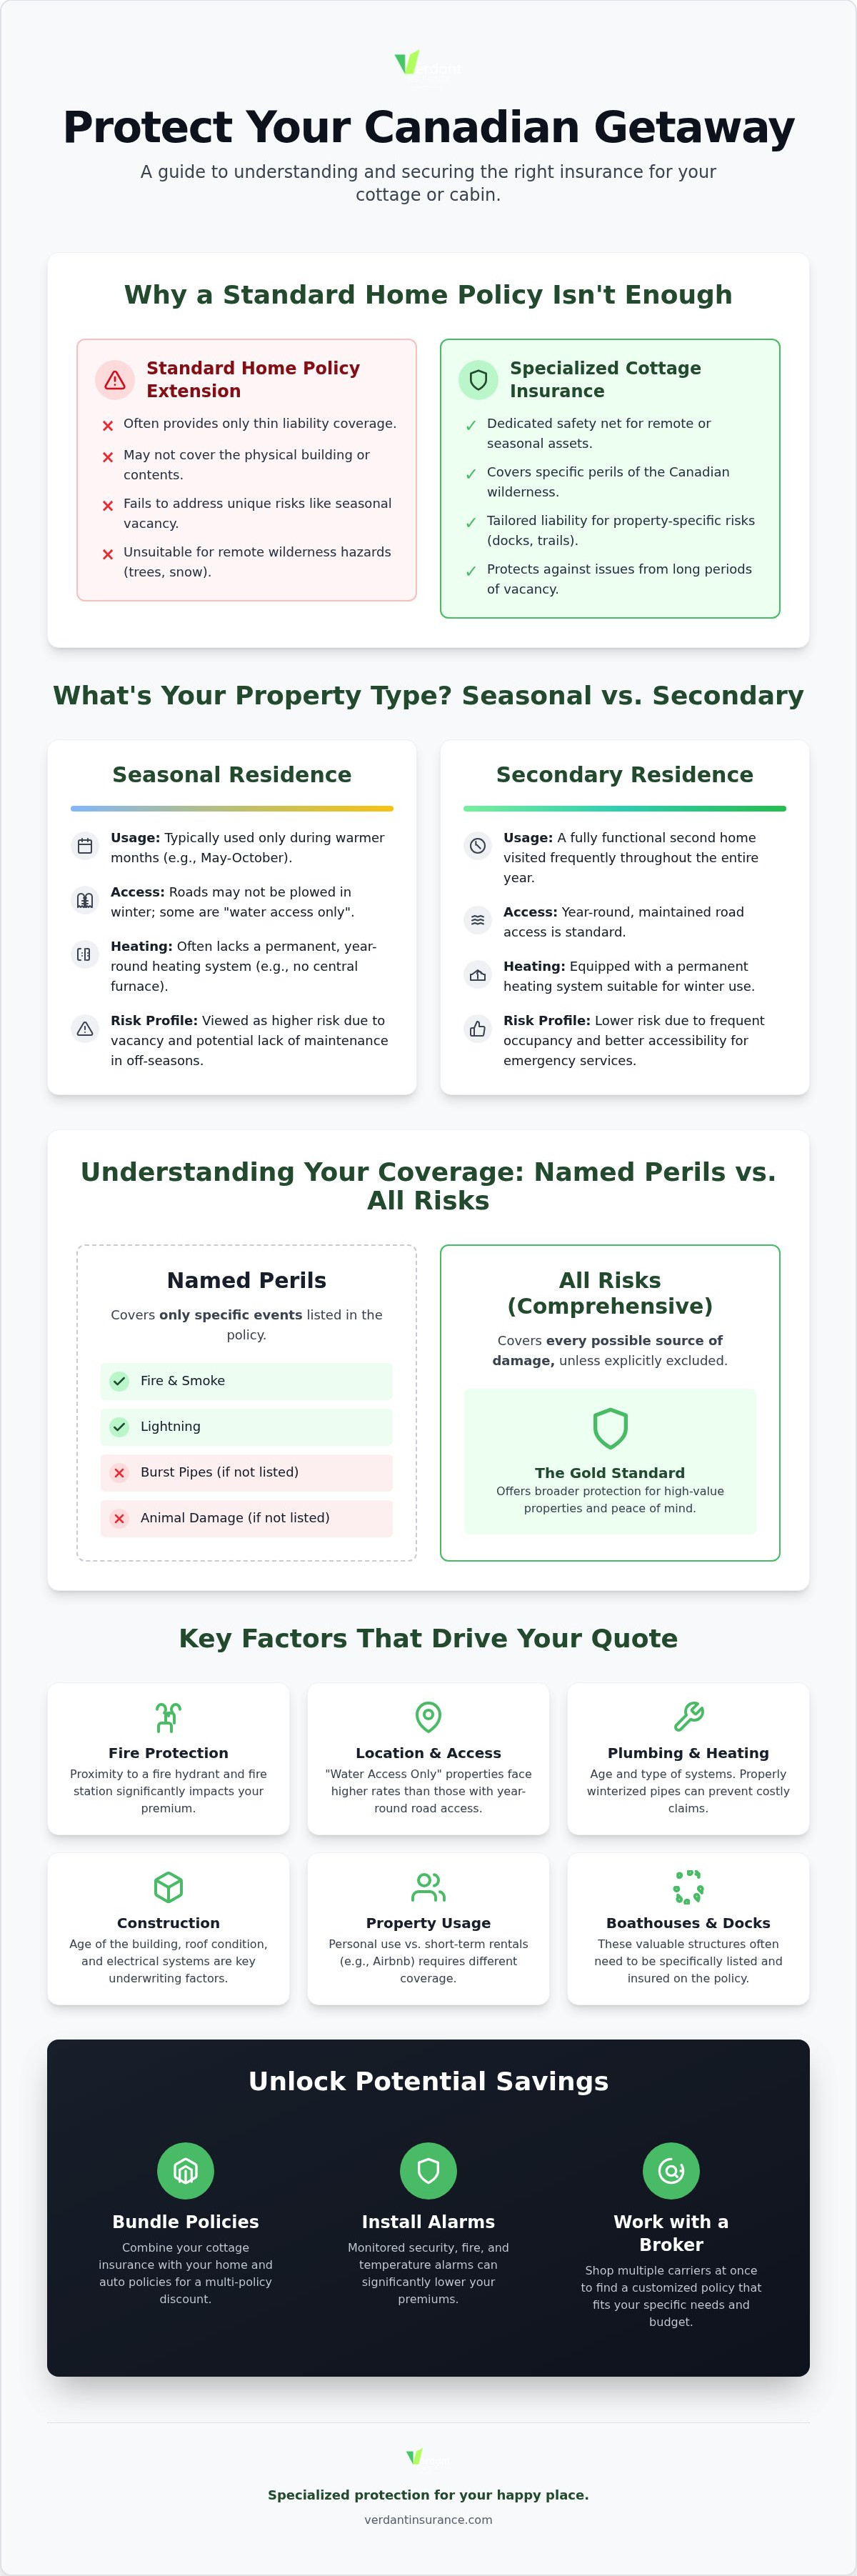
Owning a getaway in the Great White North is a dream, but it brings unique responsibilities that your city home just doesn't face. Many owners assume their primary home policy has them covered for their lakefront escape. In reality, most standard policies only offer a thin liability extension to a second location. This leaves your actual building and belongings vulnerable to the elements. To get accurate cottage insurance quotes Canada, you need to understand that this is a specialized product. It's built for properties that sit empty for weeks or face risks like falling trees and heavy snow loads. Essentially, cottage insurance is a dedicated safety net designed to protect remote or seasonal assets from the specific perils of the Canadian wilderness.
The Legal Necessity of Secondary Liability
A common mistake is thinking liability follows you everywhere without limits. While your home policy might help if you accidentally hurt someone at the park, it often falls short for property-specific incidents at the lake. Think about the risks unique to your retreat: a slippery dock, a steep hiking trail, or a guest using your canoe. If an accident happens on your property line, you need a policy that names that specific location. We help you tailor these liability limits so you aren't left exposed. It's about ensuring that a weekend invite doesn't turn into a legal headache. Having dedicated liability for your secondary location is a fundamental part of any responsible ownership plan.
Named Perils vs. All Risks Explained
When you start looking at cottage insurance quotes Canada, you'll encounter two main types of coverage. "Named Perils" is the basic version. It only covers specific events listed in the document, such as fire, smoke, or lightning. If a bear breaks in or a pipe bursts and it's not on the list, you're out of luck. This type of policy is often used for more modest, seasonal cabins where the owner is comfortable taking on more risk to save on costs.
On the other hand, "All Risks" coverage is the gold standard for high-value secondary homes. It covers every possible damage source unless the policy explicitly excludes it. While "All Risks" usually comes with a higher premium, it offers much better protection for properties with modern finishes and expensive contents. Your choice here directly impacts your quote. Opting for Named Perils might save you money monthly; however, it shifts more financial risk onto your shoulders. We recommend looking closely at your property's surroundings before deciding. A remote cabin might benefit more from a broader shield than a simple fire-only policy.
Seasonal vs. Secondary Residences: Which One Do You Own?
Determining your property's classification is the first step toward getting accurate cottage insurance quotes Canada. Insurers generally split properties into two distinct camps: seasonal and secondary. A secondary residence is essentially a fully functional second home. It features year-round road access, a permanent heating system, and is visited frequently throughout the year. Because you're there often and the property is easy to reach, insurers view it as a lower risk. This status often qualifies you for "Guaranteed Replacement Cost" coverage. This is a vital feature that ensures your building is rebuilt to its original standard even if construction costs have spiked beyond your policy limits.
In contrast, a seasonal property is typically used only during the warmer months. It might lack a central furnace or be located on a road that isn't plowed by the municipality in the winter. For a deeper dive into these nuances, A guide to cottage insurance provides excellent context on how these usage patterns shift your risk profile and your premium.
Underwriting Factors for Seasonal Cabins
If your retreat is "Water Access Only," you face unique underwriting hurdles. Without a maintained road, fire trucks can't reach your front door. This usually results in a lower fire protection grade and higher premiums. Winterization also plays a massive role in your quote. If you don't keep the heat on or properly drain the pipes before the first frost, you might find yourself excluded from water damage claims during the spring thaw. Identifying if your property can be upgraded to "Secondary" status is a great way to secure better rates and broader protection. If you're curious about how these rates compare to your main house, check out the average cost of home insurance Ontario for a helpful baseline.
Comparison Table: Seasonal vs. Secondary
Use this table to see where your getaway fits. This clarity helps us provide the most accurate options when you request a customized quote from our team of experts.
| Feature | Seasonal Property | Secondary Residence |
|---|---|---|
| Access | Water access or seasonal roads | Maintained year-round roads |
| Heating | Wood stove or space heaters | Central furnace or electric baseboards |
| Coverage | Named Perils (Basic) | All Risks (Comprehensive) |
| Replacement | Actual Cash Value | Guaranteed Replacement Cost |
When you're gathering cottage insurance quotes Canada, be specific about your heating source and whether the local municipality plows your road. Small details like a wood-burning stove or a monitored alarm system can significantly shift your classification and your final price. We recommend keeping a log of your visits; frequent check-ins during the off-season can sometimes help move a property from the "seasonal" bucket into a more favourable "secondary" category.
Key Factors That Drive Your Cottage Insurance Quote
Once you've identified your property's classification, several specific variables will determine the final price of your coverage. Unlike a standard home in the suburbs, a retreat's environment plays a massive role in its risk profile. For example, your proximity to the nearest fire station or hydrant is a primary driver for cottage insurance quotes Canada. If your property is off-grid or located in a remote "unprotected" zone where fire trucks can't easily reach, your premiums will reflect that increased risk. We often see significant price differences for properties just a few kilometers apart simply because one sits within a serviced fire district and the other does not.
Your quote also needs to account for everything outside the main cabin walls. Many Canadian getaways feature detached structures like boathouses, bunkies, sheds, and docks. These aren't always covered under a base policy, so you must value them accurately to ensure they're protected from winter ice damage or spring flooding. On the flip side, you might find savings by adjusting your contents coverage. Most people keep older furniture or fewer valuables at the lake, meaning you likely don't need the same high limits you carry for your primary residence. To keep your costs as low as possible, ensure your roof is less than 20 years old and your electrical system is up to modern standards, as outdated wiring or aging shingles can lead to steep surcharges or even coverage denials.
The Short-Term Rental Factor (Airbnb & Vrbo)
Are you planning to list your space on Airbnb or Vrbo? You must disclose this to your broker immediately. Standard personal policies rarely cover commercial activities, and failing to mention renters could void your entire policy if a claim occurs. We help you find "rental-friendly" partners that offer specific riders for tenant liability and even loss of rental income if a fire makes the property uninhabitable. It's a small addition that provides massive peace of mind when strangers are enjoying your space.
Wilderness Perils: Bears, Trees, and Water
The Canadian wilderness presents unique hazards that city homes never encounter. Many of our clients ask about the "bear clause," which is officially known as coverage for vandalism by animals. While some basic policies exclude damage from wildlife, we can help you secure comprehensive protection that covers a bear breaking through a door or a raccoon nesting in the attic. Additionally, you should consider enhanced water damage packages. These go beyond basic leaks to protect you against septic system backups or overland flooding, which are common risks in low-lying lakeside areas. In heavily forested regions, ensure your policy specifically addresses falling trees and windstorm damage to avoid out-of-pocket costs after a major storm.
How to Compare Cottage Insurance Quotes and Save
Finding the best cottage insurance quotes Canada requires a bit of homework, but the savings are well worth the effort. Start by gathering the essential data: the year your cottage was built, the age of your roof, and the specific distance to the nearest fire station. Having these details ready ensures your quote is accurate from the start. If you're just beginning your journey into property ownership, our home insurance for first time buyers guide offers a great foundation for understanding policy basics.
One of the most effective ways to lower your costs is by adjusting your deductible. While a lower deductible feels safer, increasing it to C$1,000 or even C$2,500 can lead to substantial savings on your annual premium. This strategy works best if you have an emergency fund set aside for minor repairs, allowing your insurance to act as a true safety net for major losses. Many homeowners make the mistake of keeping their cottage policy with a different company than their primary residence. We often see that primary insurers offer less competitive rates for secondary properties because they don't specialize in seasonal risks.
The Bundle Benefit
Choosing a broker that understands the nuances of the Canadian landscape allows you to unlock multi-policy discounts. You can often save up to 15% across your home, auto, and cottage coverage by placing them with the same provider. At Verdant, we specialize in these "Peace of Mind" bundles. It's much simpler to have one point of contact for all your insurance needs, ensuring there are no gaps in your protection. This approach also prevents the confusion of dealing with multiple renewal dates and different sets of paperwork.
Security and Prevention Discounts
Your cottage often sits empty for long stretches, making it vulnerable to undetected issues. Installing smart technology like temperature sensors and water leak detectors is a proactive way to protect your investment. These devices alert your phone if the heat fails or a pipe starts to drip, preventing a minor issue from becoming a catastrophic claim. Most insurers offer discounts for these remote monitoring tools and for professionally monitored alarm systems.
Above all, maintaining a "Claim-Free" status is your most powerful asset. Staying claim-free and conviction-free can earn you a discount of up to 30%, making it the single best way to keep your premiums low over the long term. These savings reflect the lower risk you present to the insurer. Ready to see how much you can save? You can request a bundled quote today and let our experts do the shopping for you.
Securing Your Retreat with Verdant Insurance
Have you ever spent hours on the phone only to receive a single insurance price that didn't quite fit? Most direct insurers can only offer you their own specific product, which might not account for the unique nuances of your lakeside property. This is where Verdant Insurance changes the game. As a digital broker, we don't work for a single insurance company; we work for you. We use our modern technology to shop the entire market, comparing multiple cottage insurance quotes Canada to find the one that balances cost and comprehensive coverage perfectly. You get the benefit of multi-carrier comparisons without the endless paperwork or bureaucratic hurdles.
Our process is built on being a "Friendly Expert." We understand that insurance jargon often feels cold and intimidating, so we focus on providing peace of mind through total clarity and simplicity. Whether you're managing a complex claim or just updating your policy limits, you'll experience a supportive, solution-oriented approach. We take pride in simplifying the lives of our clients, making the path to protection feel effortless. We're a tech-forward entity that hasn't lost its human touch, ensuring you feel secure and well-cared for at every step of your ownership journey.
Tailored Coverage for Every Cabin
No two retreats are identical, and your insurance shouldn't be either. You might own a luxury lakefront estate in Muskoka or a rustic, off-grid cabin tucked away on the rugged terrain of the Canadian Shield. We have established relationships with specialized underwriters who deeply understand these specific Ontario property risks. Our brokers know the local landscape, from the challenges of water-access lots to the specific requirements for year-round secondary homes. This deep expertise ensures your policy is customized to your actual needs rather than a generic template. We help you navigate the fine print so that your boathouse, bunkie, and docks are just as protected as your main cabin.
Get Your Quote Today
You've worked hard to secure your Canadian getaway, and protecting it shouldn't feel like a second job. Our digital platform is designed for efficiency, allowing you to start your online quote in under five minutes. You'll get the reassurance of working with a proactive guide while maintaining access to the best rates in the industry. We're confident in our ability to find you the right fit, especially for claim-free and conviction-free clients who can save up to 30%. Don't leave your sanctuary to chance. Experience the ease of a modern brokerage and Get a Cottage Insurance Quote with Verdant today to secure your peace of mind for the seasons to come.
Ready to Secure Your Canadian Sanctuary?
Protecting your retreat shouldn't be a source of stress. By now, you understand how property classifications and remote wilderness risks shape your coverage needs. Whether you're navigating the nuances of a secondary residence or securing an off-grid cabin, the right policy ensures your peace of mind remains intact. Comparing cottage insurance quotes Canada is the most effective way to find a balance between comprehensive protection and affordable premiums. We specialize in Ontario cottage country risks and offer a modern, digital-first experience backed by dedicated human support. Claim-free homeowners can even save up to 30% by switching to our tailored solutions.
Your getaway is a place for making memories, not worrying about the "what-ifs." Let us handle the heavy lifting by shopping the market for you. Get Your Personalized Cottage Insurance Quote Today and see how simple it is to protect your happy place. We're here to help you every step of the way.
Frequently Asked Questions
Is cottage insurance more expensive than regular home insurance?
Cottage insurance is typically more expensive than regular home insurance because of the unique risks involved. Remote locations, delayed fire response times, and long periods of vacancy all contribute to higher premiums. While a city home has the benefit of nearby fire hydrants, a cottage relies on specialized coverage for its wilderness setting. We help you find the right balance between cost and protection for your seasonal getaway.
Does my primary home insurance cover my cottage automatically?
Your primary home insurance does not automatically cover your cottage structure or its contents. It might offer a small extension of liability coverage to a second location, but this is often insufficient for property-specific risks. You need a dedicated policy or a specific rider to protect your building from fire, theft, or storm damage. This ensures your retreat has its own robust safety net while you are away.
Can I get insurance for a cottage that is only accessible by boat?
Yes, you can secure coverage for water-access properties. These are more complex to insure because fire departments cannot reach them by road, which usually leads to higher premiums. We work with specialized underwriters who understand the unique nature of island living. They can provide competitive cottage insurance quotes Canada for these remote retreats, ensuring your sanctuary is protected even without traditional road access.
What happens if a tree falls on my cottage during a storm?
If you have comprehensive coverage, damage to the building is typically covered. Most policies pay for repairs to the structure and the removal of the tree if it strikes a covered building. However, if a tree falls on your lawn without hitting anything, coverage for its removal is rarely included. It is a good idea to keep large trees trimmed to prevent these incidents from happening.
Do I need special insurance if I rent my cottage on Airbnb?
You definitely need a specialized rental endorsement if you list your property on platforms like Airbnb. Standard personal policies often exclude commercial activities, meaning a guest-related injury or damage might not be covered. Disclosing your rental plans to your broker ensures you have the right liability protection. It prevents your policy from being voided when you need it most during the rental season.
What is the difference between Actual Cash Value and Replacement Cost for a cottage?
Actual Cash Value pays the depreciated value of your property at the time of a loss. In contrast, Replacement Cost covers the actual expense to rebuild your cottage with new materials today. Most older seasonal cabins are insured at Actual Cash Value. Modern secondary homes often qualify for Replacement Cost, which offers much stronger financial security if you face a total loss or major structural damage.
Are docks and boathouses covered under a standard cottage policy?
Docks and boathouses are often classified as detached structures and might have limited coverage under a base policy. Docks are especially vulnerable to ice damage, which is a common exclusion in many contracts. It is vital to list these items specifically on your policy. This ensures they are valued correctly and protected against perils like fire, wind, or falling trees throughout the entire year.
How can I lower my cottage insurance premiums in Ontario?
You can reduce costs by increasing your deductible or bundling your cottage, home, and auto policies. Installing monitored security systems or smart water shut-off valves also earns significant discounts. When comparing cottage insurance quotes Canada, staying claim-free and conviction-free remains your best strategy. These proactive steps help you secure the lowest possible rates while maintaining high-quality protection for your seasonal retreat and your peace of mind.


