

Imagine a Richmond Hill homeowner waking up to a damp basement after a spring thaw, only to realize their standard policy doesn't cover the specific way the water entered their home. It's a stressful scenario that happens far too often when people assume "all-risk" means every possible event is included. When researching home insurance riders Canada residents often find themselves buried in confusing jargon like endorsements or floaters. You might feel that with the rising costs of living in the GTA, adding more to your premium is the last thing you want to do right now.
We understand that insurance can feel like a maze of fine print and unexpected exclusions. You want the peace of mind that comes with knowing a claim won't be denied because of a technicality in your contract. This guide will help you bridge the gap between standard policy limits and the specific risks facing Ontario homeowners today. We'll provide a clear, prioritized list of riders relevant to our local weather and explain how these options work in plain language. By the end, you'll have the confidence to speak with a Verdant Insurance broker about exactly what your family needs to stay secure and well-cared for.
Key Takeaways
- Gain clarity on the technical differences between riders and endorsements to better understand your policy's fine print.
- Discover how specific home insurance riders Canada homeowners use can bridge the gap for risks like overland flooding and sewer backups.
- Learn why standard limits for jewelry or electronics might leave you underinsured and how to properly schedule your high-value items.
- Evaluate the cost versus the potential risk to determine which optional coverages provide the most essential protection for your property.
- Understand the benefit of using an Ontario brokerage to compare specialized coverage options from a variety of insurance carriers.
What are Home Insurance Riders and Endorsements in Canada?
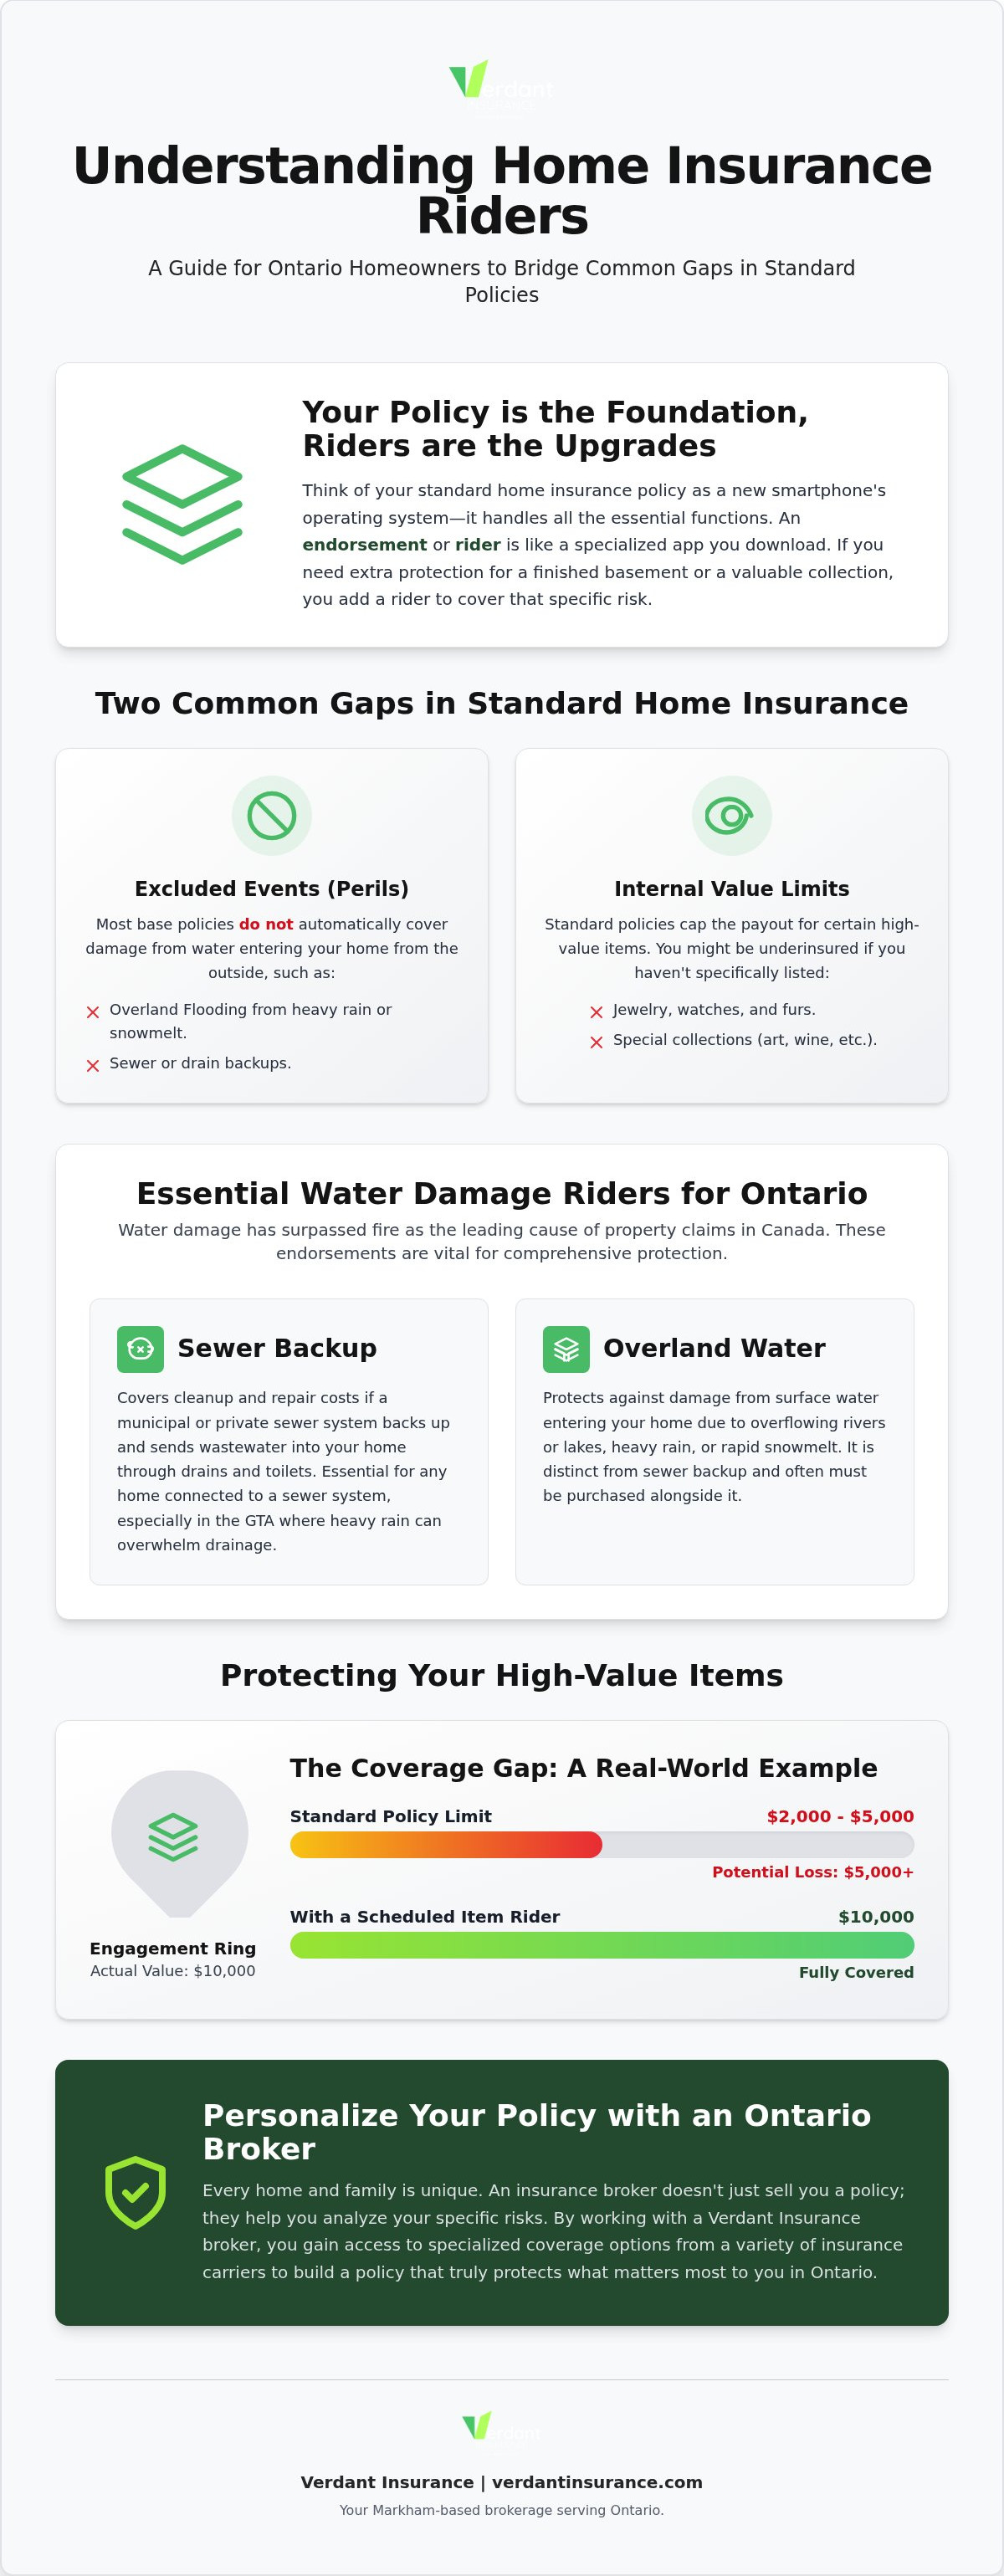
A standard home insurance policy provides a solid foundation, but it isn't a one-size-fits-all solution for every household. For many residents looking into home insurance riders Canada providers offer, the goal is to bridge the gap between "standard" protection and their actual lifestyle. A rider is a policy amendment that adds, deletes, or excludes specific coverage to tailor protection. By adding these optional layers, you ensure that your most valuable assets and specific risks aren't left vulnerable to standard policy exclusions.
Rider vs. Endorsement: Is There a Difference?
You might hear your broker use the terms "rider" and "endorsement" interchangeably, and in Ontario, they effectively mean the same thing. While "rider" is a term more traditionally found in life insurance circles, property and casualty insurers in the GTA often prefer the word "endorsement." Both terms describe a document that modifies your base insurance contract.
To make it simple, think of your home insurance policy like a new smartphone. The base policy is the operating system; it covers the essentials and keeps everything running. Adding an endorsement is like downloading a specific app. If you need to track your fitness or manage a budget, you add an app for that. Similarly, if you have a finished basement or a collection of vintage watches, you add a rider to handle those specific risks.
Why Base Policies Aren’t Always Enough
Standard policies are designed to cover the "average" home, but few homes are truly average. Most base contracts include internal limits, which are caps on how much the insurer will pay for certain categories of items. For instance, jewellery coverage is often limited to a range of $2,000 to $5,000 unless you specifically list the items. If an engagement ring worth $10,000 is stolen, a standard policy might only cover half that value.
Beyond physical items, standard policies often exclude specific events, or "perils," like overland flooding or sewer backups. These are the leading causes of claims in Ontario, yet they usually require an add-on to be fully covered. Customizing your protection is now a standard part of the home insurance quote online Canada process. This reflects a broader provincial trend toward user-selected benefits, much like the changes seen in Ontario auto insurance in July 2026. By working with a broker, you can identify these gaps before they lead to an out-of-pocket loss.
Essential Riders for Ontario Homeowners: Protecting Against Water and Weather
Ontario weather is becoming increasingly volatile. From rapid spring thaws in Markham to torrential summer downpours in Toronto, water poses a constant threat to your property. In fact, water damage has officially surpassed fire as the leading cause of property claims across the country. Insured losses from severe weather in Canada exceeded $2.4 billion in 2025 alone. Despite these risks, many residents are surprised to learn that a basic policy often excludes water that enters your home from the outside. This is why understanding the specific home insurance riders Canada homeowners need is vital for long-term security.
Standard policies typically cover "sudden and accidental" internal water damage, such as a burst pipe. However, they rarely cover water coming up through the floor or in through the windows without additional endorsements. These add-ons are particularly important if you live in flood-prone areas or have a finished basement that would be expensive to repair.
Sewer Backup Endorsement
Municipal drainage systems in the GTA can't always keep up with heavy rainstorms. When these systems become overwhelmed, wastewater can flow backward through your home's drains and toilets. A sewer backup rider covers the extensive cleanup and repair costs associated with this event. The price for this protection varies based on your specific location and the average cost of home insurance in Ontario. It's a fundamental addition for any home connected to a municipal sewer system.
Overland Water Protection
This endorsement covers damage from surface water that enters your home during extreme weather. This includes overflowing lakes, heavy rain, or rapid snowmelt. It's different from sewer backup because it focuses on water that stays on the ground's surface before entering. Most insurers in Ontario require you to have sewer backup coverage in place before you can add overland protection. Bundling these two creates a much more robust safety net for your property.
Ground Water Coverage
If water seeps through your basement walls or foundation floors, you are likely dealing with a ground water issue. This is distinct from a flood or a sewer backup. Some insurers now offer "Enhanced Water" packages that combine sewer, overland, and ground water risks into one simplified add-on. This ensures you don't have to worry about the technicalities of how the water entered when you're dealing with a claim.
Ensuring your basement is protected starts with a conversation about your property's specific risk factors. A professional insurance broker in Ontario can help you navigate which water endorsements are worth the investment for your specific neighbourhood.
Specialty Coverage: Protecting High-Value Items and Unique Risks
Standard policies offer broad protection for your belongings, but they almost always include "special limits" for specific categories of items. If you own a high-end watch, a collection of fine art, or professional-grade musical instruments, you might find that your base coverage isn't enough. This is where "Scheduled Personal Property" becomes essential. By listing these items individually, you ensure they're covered for their full appraised value without the constraints of standard policy caps.
Unlike standard contents coverage, these specialized home insurance riders Canada homeowners choose often provide "all-risk" protection. This means your items are covered for almost any event, including accidental loss or "mysterious disappearance," which are typically excluded from a basic contract. Most insurers offer these riders with a $0 deductible for the scheduled items. You won't have to pay out of pocket if a specific piece is lost or damaged.
Jewellery, Fine Arts, and Collectibles
Standard home insurance in Ontario usually limits jewellery claims to a total of $2,000 to $5,000 per incident. If you have an engagement ring or a family heirloom worth significantly more, scheduling the item is the only way to guarantee full reimbursement. To set this up, you'll need a professional appraisal from a certified jeweller or art expert. Once the item is scheduled, the coverage often follows you globally. Whether you lose a gemstone while on vacation or a painting is damaged during a move within the GTA, your protection remains intact.
Bylaw Coverage Endorsement
If you live in a historic neighbourhood in Markham or a classic home in Toronto, building codes have likely changed significantly since your house was built. Standard policies are designed to rebuild your home exactly as it was before the loss. However, if a fire occurs, the City of Toronto or the City of Markham will require you to rebuild according to 2026 Ontario building standards. This might involve expensive upgrades to wiring, plumbing, or insulation. Bylaw coverage pays for these mandatory extra costs. This ensures you aren't stuck with a massive bill just to meet current legal requirements.
Identity Theft Protection
Identity theft is a modern risk that requires a modern solution. This rider doesn't reimburse you for stolen money; instead, it covers the administrative and legal costs of restoring your credit and your good name. It pays for things like legal fees, notary costs, and lost wages while you spend time meeting with banks or credit bureaus. It's an affordable add-on that provides a proactive guide through a very stressful and time-consuming recovery process. Adding this to your policy is a simple way to gain peace of mind in our increasingly digital world.
How to Determine Which Riders are Worth the Investment
How do you decide which add-ons are necessary and which are just extra noise? The answer depends on three main factors: your home's location, its age, and what's inside. When exploring home insurance riders Canada residents often struggle with the "Cost vs. Risk" balance. It's helpful to view these as a small monthly investment that prevents a massive out-of-pocket loss. A rider might only add a few dollars to your monthly bill, but it could cover a $50,000 restoration after a basement flood. We recommend reviewing your policy annually, especially after major renovations or luxury purchases, to ensure your coverage still fits your life. If you're currently buying a home, remember that some mortgage lenders in high-risk Ontario flood zones may require specific water riders before they approve your financing.
Assessing Your Local Risks
Start by looking at your neighbourhood's history. Have there been basement flooding incidents in your part of Markham or Richmond Hill recently? You can check municipal flood maps or ask your broker about regional claim trends in the York Region. Proactive risk management is the best way to ensure long-term stability for your property. The logic used for car insurance for safe drivers applies here too. By identifying potential hazards like aging sewer lines or nearby bodies of water, you can choose the specific endorsements that provide the most value for your specific address.
The "Inventory Check": Evaluating Your Contents
A room-by-room walkthrough is the most effective way to spot gaps in your contents coverage. Open your closets and check your storage spaces for items that might exceed standard policy limits. During this check, it's vital to understand the difference between "Actual Cash Value" and "Replacement Cost." Standard policies often pay the depreciated value of an item, while many riders ensure you receive enough to buy a brand-new equivalent. Create a checklist of high-value items to discuss with your broker, including:
- Professional-grade musical instruments
- High-end e-bikes or specialized sporting equipment
- Collectibles, such as rare cards or vintage wine
- Home office equipment that exceeds basic business limits
Speak with a Verdant broker to customize your coverage
Personalizing Your Policy with an Ontario Insurance Broker
Verdant Insurance is an Ontario-based property and casualty insurance brokerage located in Markham. You should keep in mind that we are an insurance brokerage, not a direct insurance company or insurer. This distinction is the core of the value we provide to our clients. When you explore the various home insurance riders Canada residents have available, a broker acts as your personal advocate. Instead of being limited to the products of a single company, we compare endorsements and riders across our network of multiple insurance partners. This ensures you receive a policy tailored to your specific needs rather than a generic, one-size-fits-all solution.
Why Local Expertise Matters in Markham and the GTA
Our team is based right here in Markham, which gives us a deep understanding of the local landscape that a national call centre simply cannot match. We are familiar with the specific weather patterns of the York Region and the unique building bylaws in Richmond Hill, Vaughan, and Toronto. This local expertise is vital when determining the appropriate limits for sewer backup or overland water coverage. We know which areas are more prone to specific risks, allowing us to provide proactive guidance. As your Friendly Expert, we focus on simplifying the insurance process. We take the time to explain how each rider works in plain language, ensuring you feel well-cared for and secure in your choices.
Getting a Customized Home Insurance Quote
Working with a Verdant broker to secure a home insurance quote in Ontario is a transparent and supportive experience. We begin by assessing your property's unique characteristics and your personal belongings. Our goal is to find the right balance between comprehensive protection and your specific budget. We help you identify which riders are essential investments for your peace of mind and which ones might be unnecessary for your situation. This methodical approach ensures there are no surprises if you ever need to make a claim.
Insurance should provide clarity and comfort, not confusion. By choosing a local broker who understands the GTA, you gain a partner dedicated to protecting what matters most to you. We invite you to reach out for a comprehensive policy review. Whether you are moving into a new home or simply want to ensure your current coverage is up to date, we are ready to assist you with integrity and care.
Securing Your Ontario Home for the Future
Customizing your protection is the most effective way to ensure your insurance actually works when you need it most. Whether you are adding overland water protection for a property in York Region or scheduling a family heirloom, these specific home insurance riders Canada residents choose provide the layer of security that standard contracts often lack. By focusing on your unique risks rather than a generic policy, you build a safety net that is both efficient and comprehensive.
Our Markham based team is here to help you navigate these choices with clarity and ease. As an Ontario brokerage, we specialize in comparing options from multiple insurance partners to find the right fit for your budget and your home. You deserve to feel confident that your most valuable assets are well cared for by experts who truly understand the local landscape.
Taking a proactive approach to your coverage today ensures you can face whatever tomorrow brings with total peace of mind.
Frequently Asked Questions
What is the difference between a rider and an endorsement in Ontario?
In Ontario, there is no practical difference between a rider and an endorsement. While property insurers in the GTA often use the term "endorsement" to describe a modification to your contract, "rider" is a common term used in the broader industry. Both documents serve to amend your base policy by adding, deleting, or changing specific coverages. When discussing home insurance riders Canada residents often find that these terms are used interchangeably by brokers to describe customized protection.
Are home insurance riders mandatory for Canadian homeowners?
Home insurance riders are not legally mandatory in Ontario, but they are often practically necessary. While the province doesn't require them, your mortgage lender might insist on specific endorsements. For example, if you are buying a home in a known flood zone in the York Region, a lender may require overland water and sewer backup coverage as a condition of your financing. These add-ons ensure the lender's investment is protected against common regional risks.
How much do home insurance riders typically cost in Ontario?
The cost of adding a rider depends on several factors, including your home's location, the age of your property, and the specific risk being covered. Generally, premiums for water protection or scheduled items vary by insurer and individual circumstances. Because Verdant is a brokerage, we can compare these costs across our network of insurance partners. This allows us to help you find a customized solution that fits your budget while addressing your most significant exposures.
Does a standard home insurance policy cover my jewellery?
A standard policy does cover jewellery, but it is subject to strict "special limits" that often range between $2,000 and $5,000 per incident. If you have an engagement ring or a luxury watch worth more than these amounts, the base policy won't provide full reimbursement after a theft or loss. You will need to "schedule" these items individually. This specialized rider ensures your high-value belongings are protected for their full appraised value without a deductible.
Can I add a rider to my home insurance policy at any time?
You can add a rider to your policy at any time during your term. You don't need to wait for your annual renewal to update your coverage. If you make a significant purchase, such as a high-end e-bike, or complete a basement renovation in Richmond Hill, you should contact your broker immediately. We can bind the new coverage quickly to ensure there are no gaps in your protection while you wait for your next renewal date.
What is the most important rider for a home with a finished basement?
Sewer backup and overland water protection are the most vital riders for any finished basement in Ontario. Water damage is the leading cause of property claims in the GTA, often resulting in restoration costs that can be quite substantial. A standard policy typically excludes water that enters from outside or backs up through drains. Adding these riders ensures that your flooring, drywall, and furniture are covered if municipal systems become overwhelmed by heavy rainfall or rapid snowmelt.
Do I need a separate rider for my home-based business?
Yes, a separate endorsement is usually required because standard policies offer very limited protection for business-related risks. Most base contracts have a low cap on business equipment coverage, which may not cover professional computers or inventory. Additionally, standard home insurance doesn't cover liability if a client is injured on your property. A home-based business rider provides the necessary equipment limits and liability protection for consultants or online sellers operating in Ontario.
Is earthquake coverage a standard part of home insurance or a rider?
Earthquake coverage is an optional rider and is not included in standard Ontario home policies. While the GTA is not considered a high-risk earthquake zone, some homeowners choose to add this endorsement for total peace of mind. It covers damage to the dwelling and its contents caused by tremors or shifting. Because the risk varies by geography, a broker can help you determine if this add-on is a practical choice for your specific address in the York Region.


