

Imagine you've spent months planning a dream getaway from Markham to the Amalfi Coast, only for an unexpected family emergency to ground you just days before takeoff. Without the right trip cancellation insurance Canada provides, you could be looking at thousands of dollars in non-refundable deposits simply vanishing. It’s a common fear for many Ontario travelers who worry that one bit of bad luck could turn a hard-earned vacation into a major financial loss. We understand that you want to focus on your itinerary, not on the "what-ifs."
This comprehensive guide will show you exactly how to protect your travel investment from unexpected disruptions. You’ll learn the difference between cancellation and interruption coverage, and why the Government of Canada strongly recommends this protection even for short trips. We’ll break down the specific reasons that trigger coverage, compare the fine print of credit card plans against standalone policies, and help you decide which protection fits your specific journey. Whether you're flying out of Pearson or crossing the border for a quick weekend away, you’ll gain the confidence to choose a plan that secures your peace of mind and protects your budget.
Key Takeaways
- Understand how trip cancellation insurance acts as a vital financial safeguard for non-refundable deposits if an unexpected event prevents you from traveling.
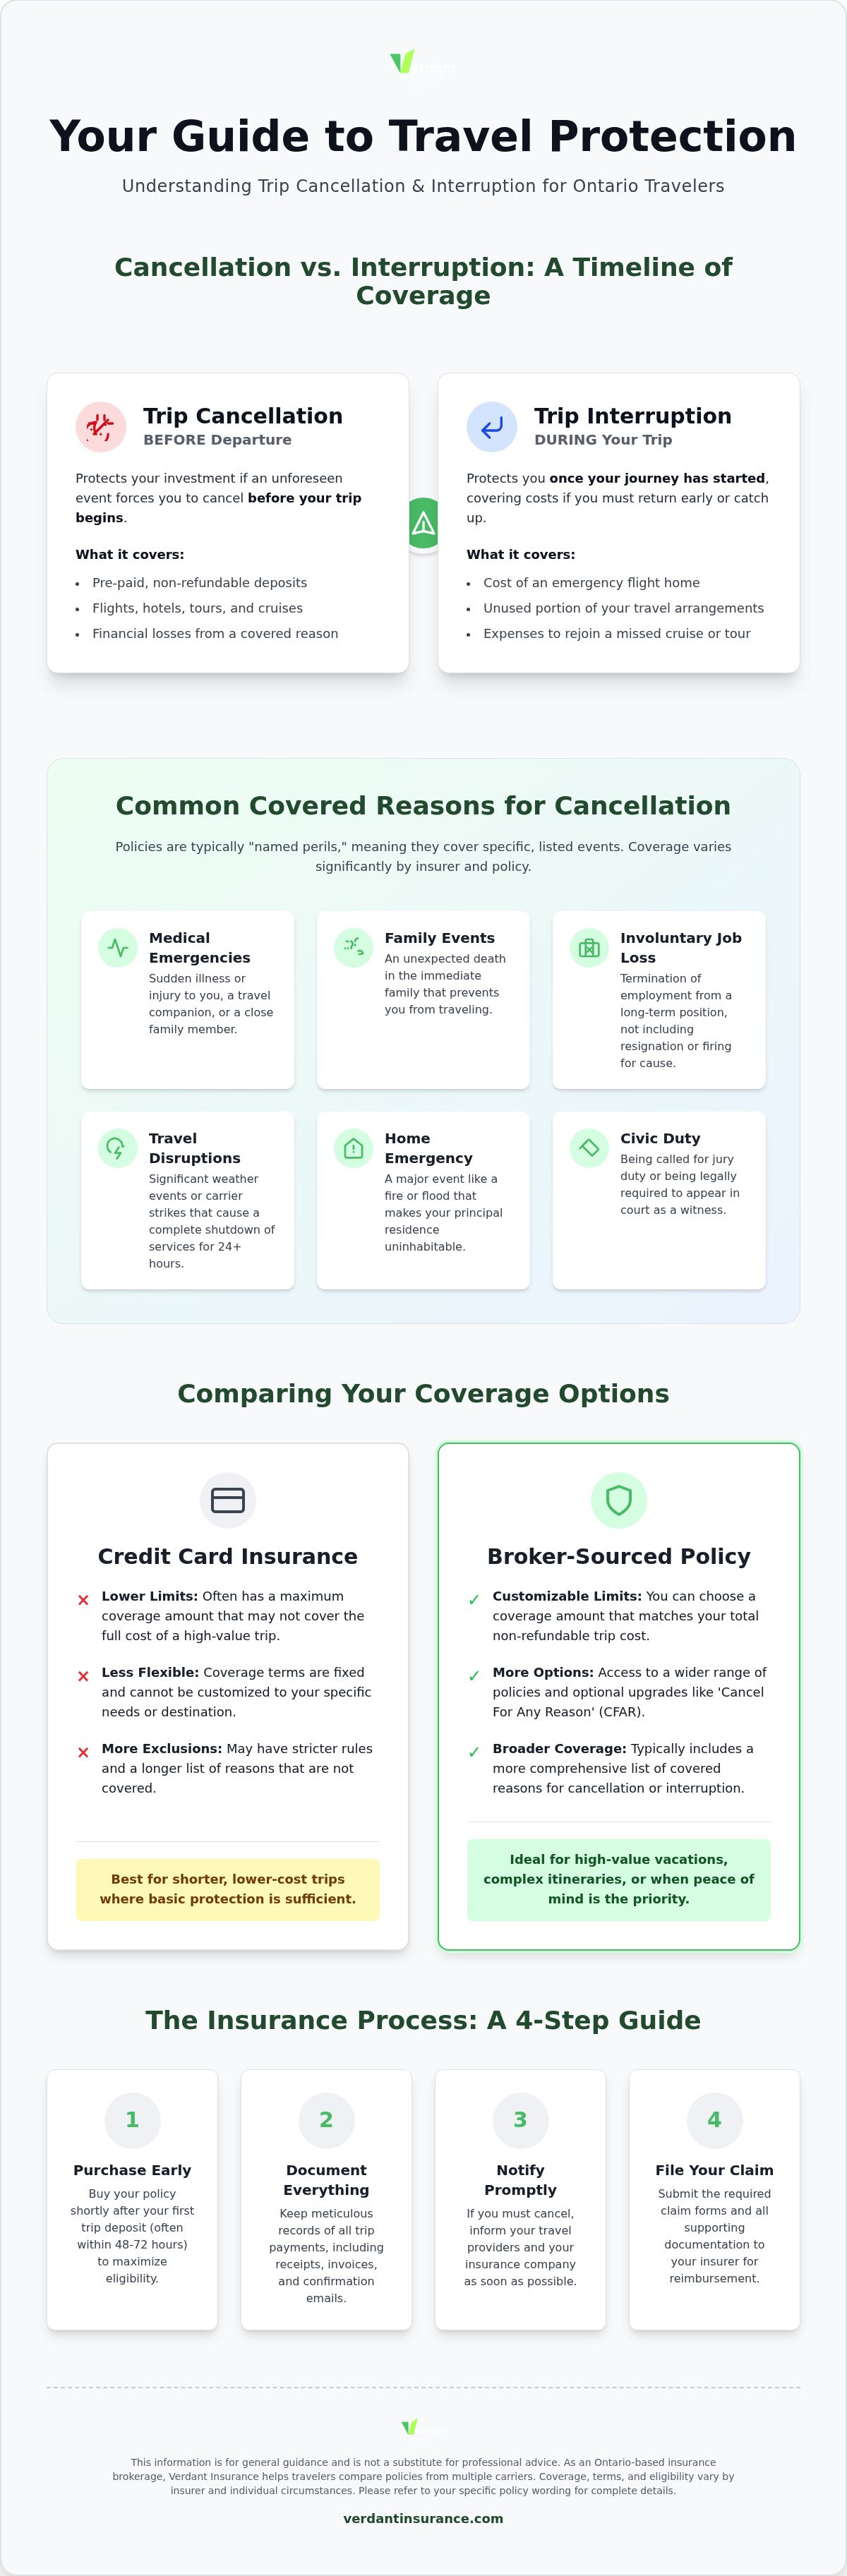
- Learn the chronological difference between trip cancellation, which covers you before departure, and trip interruption, which protects you once your journey has begun.
- Discover why credit card insurance often has lower limits and how standalone trip cancellation insurance Canada policies offer broader, more customizable coverage for high-value trips.
- Identify common covered reasons for claims, including sudden illness, involuntary job loss, or significant weather disruptions affecting major GTA airports.
- See how working with an Ontario-based broker allows you to compare multiple carriers to find a policy tailored to your specific destination and individual needs.
What is Trip Cancellation Insurance in Canada?
Trip cancellation insurance Canada acts as a financial bodyguard for your vacation budget. It's a specific type of policy designed to reimburse you for pre-paid, non-refundable travel expenses if an unforeseen event forces you to cancel your plans before you ever leave home. When you start researching What is travel insurance, you'll find that trip cancellation is one of the most critical components for protecting your financial interests. For Ontario families booking a winter escape to the Caribbean or a summer tour through Europe, these bookings often happen six to twelve months in advance. A lot can change in that time. This insurance ensures that a sudden change of plans doesn't mean your money simply disappears.
This coverage protects your total travel investment, including airfare, hotel stays, tours, and even cruise fares. Most standard policies operate on a named perils basis. This means they cover specific events like a sudden illness, a death in the family, or an involuntary job loss. If you want more flexibility, you might look into Cancel for Any Reason (CFAR) options. While CFAR adds a layer of versatility, you should remember that coverage details, limits, and eligibility vary by insurer and your specific situation.
The Core Purpose of Trip Protection
The primary goal is to remove the financial sting of a cancelled trip. Without it, you could be on the hook for thousands of dollars in non-refundable deposits. If a medical emergency occurs right before you're set to depart from Pearson, this insurance helps you recover those costs. It transforms a potential financial disaster into a manageable situation. By securing trip cancellation insurance Canada, you're essentially buying the right to try again later without losing your initial investment. It provides the peace of mind needed to book those once-in-a-lifetime trips with confidence.
Who Should Consider This Coverage?
Anyone booking a high-value international trip should prioritize this protection. Families in the GTA traveling with elderly relatives or small children often find it indispensable because health situations can change rapidly. Business owners in Markham with non-transferable travel arrangements also benefit from the stability these policies provide. Because every traveler’s needs are different, talking to a broker can help you compare the various options available from different insurance carriers. Whether you're heading south for the sun or flying overseas for a wedding, protecting your deposits is a smart financial move.
How Trip Cancellation and Interruption Insurance Works
Understanding how trip cancellation insurance Canada functions is the first step toward a stress-free departure. It operates on a specific timeline that dictates when and why you can file a claim. While many people use the terms interchangeably, cancellation and interruption coverage serve two distinct purposes based on where you are in your journey. Insurers calculate your payout based on the actual non-refundable loss you've incurred, which is why keeping meticulous records is vital for anyone in the GTA planning a getaway. Every policy is triggered by specific "covered reasons," which are the only situations that allow for a successful claim payout.
The Timeline: Before vs. During Your Trip
Cancellation coverage applies strictly before your scheduled departure date. If you're at home in Richmond Hill and a sudden illness prevents you from leaving, this part of your policy covers the non-refundable deposits you've already paid. Once you've cleared security at Pearson and your trip begins, interruption coverage takes over. This helps with the cost of returning home early or staying longer due to a crisis. It also addresses misconnections; for example, if a flight delay causes you to miss a cruise departure in a different city, your policy may help cover the costs to catch up with the ship.
Common Steps in the Insurance Process
Following a structured process ensures your claim moves forward smoothly. It starts the moment you book your travel and continues until you return to Ontario.
- Step 1: Purchase coverage early. Most carriers require you to buy your policy within a specific window, often 48 to 72 hours after making your initial trip deposit.
- Step 2: Document everything. Save every receipt, invoice, and confirmation email for your flights, hotels, and tours. This creates a clear paper trail for the insurer.
- Step 3: Notify the insurer immediately. If something goes wrong, contact the insurance company or your broker before making new arrangements. They can guide you on the required next steps.
- Step 4: Gather official proof. You'll need a medical certificate from a physician or an official report to validate the reason for your disruption.
Eligibility for a payout depends entirely on the policy wording and the specific triggers included in your plan. Insurers calculate your reimbursement by looking at the unused, non-refundable portions of your trip. If you miss three days of a pre-paid hotel stay, they focus on the value of those specific nights. If you're unsure which triggers are included in your plan, you can connect with a broker to review the details of various travel insurance options. This clarity helps you avoid surprises if you ever need to use your trip cancellation insurance Canada.
Is your credit card enough to protect your vacation? Many travellers in the GTA rely on the "free" insurance bundled with their premium plastic, but this convenience often comes with hidden gaps. While these cards provide a basic safety net, they rarely offer the robust protection found in standalone trip cancellation insurance Canada policies. Understanding the fine print before you head to Pearson can save you from a major financial headache if your plans fall through. It's your investment on the line, and a generic bank product might not be the right tool for the job.
Limitations of Credit Card Coverage
One of the biggest hurdles with credit card insurance is the reimbursement cap. These plans often limit payouts to a specific dollar amount per person that may not reflect the rising costs of international travel. If you've booked a high-end luxury cruise or a multi-city European tour, that cap might only cover a fraction of your non-refundable deposits. Most cards also require you to charge the entire trip cost to that specific card. If you paid for your flights with loyalty points or used a different card for your hotel booking, you might find yourself without any coverage at all. The list of covered reasons is also significantly shorter, often excluding common disruptions like specific family emergencies or job-related changes.
Benefits of a Standalone Policy
Standalone policies offer a higher level of customization that matches the actual value of your travel investment. Because these plans aren't tied to a specific payment method, you have more flexibility in how you book your trip. They also provide much better support for travellers with pre-existing medical conditions. While a credit card policy might have a rigid stability period, standalone plans often offer more lenient terms that are easier to navigate. This is particularly important for seniors or those with ongoing health management needs who want to ensure their coverage is valid.
Working with an Ontario broker gives you a dedicated ally during the claims process. Instead of waiting on hold with a generic bank call center, you have access to professional advice right here in Markham or Richmond Hill. A standalone plan often acts as primary coverage, which simplifies the reimbursement process significantly. This direct path to a payout provides the clarity and security that high-value trips deserve. Choosing a tailored plan means investing in a solution that fits your specific itinerary rather than a one-size-fits-all bank product.
What is (and Isn’t) Covered: Navigating Policy Exclusions
Understanding what triggers a claim is essential for any traveler from Markham or Vaughan. Many people assume that any cancellation is covered, but trip cancellation insurance Canada is built on specific, named perils. If you aren't clear on these triggers, you might face an unpleasant surprise when trying to recover your costs. It is also important to remember that actual coverage is subject to insurer eligibility, policy wording, limits, and exclusions.
Standard Covered Reasons
Most policies focus on significant life events that are entirely beyond your control. These typically include medical emergencies affecting you, your travel companion, or an immediate family member. If the Canadian government issues a new travel advisory for your destination after you've booked, this is often a valid reason to cancel. Legal obligations, such as being called for jury duty or acting as a witness in court, are also standard inclusions. These triggers provide a safety net for the most common disruptions that could derail your plans.
In the GTA, we often deal with severe winter weather that can disrupt travel for days. If a massive ice storm grounds all flights at Pearson International Airport or Billy Bishop, your policy typically covers the resulting cancellation. However, this usually only applies if the weather event was not already a known or named storm when you purchased your coverage. This local context is why buying insurance the moment you book your trip is so important for Ontario residents.
Common Exclusions to Watch For
Changing your mind is the most frequent reason people want to cancel, but standard policies don't cover a simple "change of heart." You also need to be wary of the pre-existing medical condition clause. For Ontario seniors, this often involves a stability period, which can range from 90 to 180 days depending on the insurer. If you've had a change in medication, a new prescription, or a recurrence of symptoms during this window, the insurer may deny a claim related to that condition. Always check the look-back period to ensure your health history won't invalidate your protection.
Other common exclusions include participating in high-risk activities or extreme sports that aren't specifically added to your plan. If you're planning an adventurous trek or scuba diving excursion, you may need a specific endorsement. Additionally, disruptions caused by events you already knew about before purchasing the policy, such as a looming strike or a known political uprising, are typically excluded. Being proactive and honest about your plans ensures you get the right level of protection.
Choosing the Right Travel Protection with an Ontario Broker
When you're ready to secure your 2026 travel plans, the most important step isn't just buying a policy; it's choosing the right partner to help you navigate the options. Unlike direct insurers or banks that only offer one proprietary product, an Ontario insurance broker works for you. By accessing multiple partner insurance carriers, a broker can help you find a plan that aligns with your specific destination and risk tolerance. This objective approach ensures you aren't overpaying for coverage you don't need or, worse, leaving your travel investment exposed due to a narrow policy. Because every journey is unique, customization is the key to true peace of mind.
Why Work with a Broker in Ontario?
Working with a professional in Markham or the wider GTA provides a layer of accountability you won't find with a faceless online platform. A local broker understands the specific concerns of Ontario travelers, from the nuances of OHIP limitations to the impact of seasonal disruptions at Pearson. If you ever need to file a claim, having a proactive guide to help you navigate the carrier's requirements is invaluable. They can help clarify the "Policy Wordings" before you commit, ensuring you understand exactly what is and isn't covered under your chosen trip cancellation insurance Canada plan. This local expertise ensures that the advice you receive is grounded in Ontario specific regulations and needs.
Preparing for Your Quote
To get the most accurate quote for your upcoming journey, it's helpful to have your details organized before you begin. Start by calculating your total non-refundable trip costs, including flights, hotels, and pre-paid excursions. You'll also need your exact departure and return dates, along with details of any stopovers. Because underwriting requirements vary by insurer, be prepared to discuss your medical history if you're seeking coverage for pre-existing conditions. This transparency allows your broker to find a stable policy that respects your health needs. Many travelers find that getting a tailored quote through an online platform is the most efficient way to start, but having the option to speak with a broker in Richmond Hill or Vaughan adds that essential human touch.
Your 2026 travel investment deserves more than a generic bank-led product. By taking the time to compare multiple carriers and understanding the specific triggers in your policy, you can set off on your next adventure with total confidence. Whether you're planning a multi-generational cruise or a solo adventure, a tailored approach provides the clarity you need to protect your budget from the unexpected.
Secure Your Next Adventure with Confidence
Planning a trip should be about the excitement of discovery, not the anxiety of potential financial loss. By understanding the nuances of trip cancellation insurance Canada, you've taken a vital step toward a more secure vacation. You now know how to distinguish between cancellation and interruption, why standalone policies often outperform credit card coverage, and how to manage common exclusions like pre-existing medical conditions.
Our Markham-based team at Verdant Insurance is here to act as your proactive guide. As a brokerage, we provide access to multiple Ontario insurance partners to find a policy that truly fits your unique itinerary. We also look at your entire insurance profile, which may include identifying claims-free discounts on other lines like your auto or home insurance. As always, actual coverage is subject to your policy wording and insurer eligibility.
You've put a lot of effort into planning your 2026 travels. Let's ensure your financial investment is as stable as your itinerary so you can head to the Pearson departure gates with total peace of mind.
Frequently Asked Questions
Is trip cancellation insurance mandatory for Canadians traveling abroad?
No, trip cancellation insurance is not legally mandatory for Ontario residents traveling abroad. However, the Government of Canada strongly recommends it to avoid significant financial loss. While not required by Ontario law, some international destinations may require proof of insurance for entry. It's a personal choice to protect your non-refundable deposits from unexpected events before you depart from the GTA.
Can I buy trip cancellation insurance after I have already booked my flight?
Yes, you can purchase coverage after booking, but timing is critical. Most insurers require you to buy your policy within a specific window, often 48 to 72 hours after making your initial payment, to cover pre-existing conditions. If you wait too long, you might lose access to certain benefits. It's always best to secure your trip cancellation insurance Canada plan as soon as you make your first non-refundable deposit.
Does trip cancellation cover me if I just change my mind about going?
Standard policies don't cover a simple change of mind. To have this flexibility, you'd need to purchase a "Cancel for Any Reason" (CFAR) endorsement. Standard plans only trigger for "named perils" like sudden illness or involuntary job loss. Without a specific CFAR add-on, deciding you no longer want to travel won't result in a successful claim payout for your non-refundable costs.
What happens if my airline goes bankrupt before my trip?
Coverage for airline bankruptcy varies significantly by insurer. Some comprehensive policies include a "Default of a Travel Provider" clause that protects you if an airline or tour operator ceases operations due to financial insolvency. However, this isn't a universal feature. You should review your policy wording carefully or ask your broker to confirm if this specific protection is included in your travel insurance plan.
How much does trip cancellation insurance typically cost in Ontario?
The cost of travel insurance in Ontario varies based on several factors, including your age, trip length, and the total non-refundable cost of your vacation. Generally, premiums range between 4% and 12% of your total trip value. For example, a more expensive cruise will have a higher premium than a short flight. Your individual circumstances and choice of carrier will ultimately determine your final rate.
Will trip cancellation insurance cover me for COVID-19 or other pandemics?
Many modern policies now include coverage for COVID-19 if you contract the virus and are unable to travel. However, coverage for general pandemic-related disruptions, such as border closures or new government lockdowns, is often excluded once a pandemic is considered a "known event." You should check the specific terms regarding infectious diseases for your trip cancellation insurance Canada policy to see how an insurer handles these disruptions.
What is the difference between trip cancellation and travel medical insurance?
These are two distinct types of protection. Trip cancellation focuses on reimbursing your non-refundable, pre-paid costs if you can't leave home. Travel medical insurance covers emergency healthcare expenses, like hospital stays or doctors' visits, while you're actually on your trip. While often bundled together, they serve different purposes. Cancellation protects your wallet before you depart Pearson, while medical insurance protects your health while you're abroad.
Can I get a refund on my insurance premium if I cancel my trip for a covered reason?
No, you generally don't receive a refund on your insurance premium if you file a claim. The premium is the fee paid to the insurer to take on the risk of your trip being cancelled. Once the policy is in effect and a claim is paid out, the contract is considered fulfilled. You'd receive reimbursement for your non-refundable travel expenses, but the cost of the insurance policy itself isn't refundable.


