

Why are you still paying for a "one-size-fits-all" insurance policy when your daily commute has shifted from the Don Valley Parkway to your home office? Many Ontario drivers feel the frustration of paying for high-mileage coverage that doesn't reflect their actual time on the road. It's a common concern, especially with the significant provincial insurance reforms that took effect on July 1, 2026. Discover how to tailor your auto coverage to your specific lifestyle and budget using our professional Ontario policy customization framework for customizable car insurance policies.
This article provides a clear roadmap through the new "à la carte" system. We'll break down the difference between mandatory requirements and optional accident benefits, ensuring you're protected in complex GTA traffic without overpaying for redundant coverage. Whether you're driving in Markham, Richmond Hill, or Toronto, you'll learn how to engineer a policy that reflects your actual driving habits. We'll demystify which OPCF endorsements are truly worth the cost so you can build a policy that offers genuine peace of mind. By the end of this guide, you'll have the confidence to choose coverage that fits your needs perfectly.
Key Takeaways
- Identify the four mandatory pillars of Ontario auto insurance and how they form the foundation of your protection.
- Learn how to design customizable car insurance policies that match your specific lifestyle, from remote work setups to daily GTA commutes.
- Use our step-by-step template to inventory your vehicle's value and your personal liability needs before choosing coverage limits.
- Discover which optional accident benefits and OPCF endorsements provide the most value for your unique risk profile.
- Understand how a professional broker navigates multiple insurance carriers to find a tailored fit for Ontario drivers.
The Shift Toward Customizable Car Insurance Policies in Ontario
The 2026 insurance reforms in Ontario changed how we think about protection. We've moved away from rigid packages toward a risk-aligned structure that reflects your actual life. A customizable policy isn't just a collection of standard features; it's a strategy designed to protect your specific assets. In the modern Ontario market, especially with the rise of remote work in York Region, flexibility is no longer a luxury. It's a necessity.
The role of a broker is vital here. Unlike a direct insurer with a single set of rules, a broker accesses different customization menus from various insurers. This allows you to build customizable car insurance policies that address rising repair costs and changing lifestyle needs. Personalized coverage goes much deeper than simply adjusting your deductible. It involves analyzing your daily risks to ensure you aren't paying for protection you'll never use.
Customization vs. Standard Quotes
A generic online quote is often just a starting point. While these tools provide a quick estimate, they rarely account for the nuances of Ontario's complex Vehicle insurance laws. "Off-the-shelf" policies frequently contain a "Protection Gap." This is the space between what a standard policy covers and the actual financial risk you face on the 401 or in downtown Toronto. A broker-negotiated policy closes this gap by fine-tuning liability limits and specific endorsements that a computer algorithm might overlook.
The Benefits of a Tailored Approach
Choosing a tailored plan offers more than just better protection; it often leads to better value. Safe, claim-free, and conviction-free drivers in Ontario can access discounts of up to 30% through specific insurer programs. This is particularly beneficial for low-mileage drivers who spend more time working from home in Markham or Vaughan than commuting on high-traffic routes.
By aligning your premium with your actual vehicle usage, you gain peace of mind. You'll know that your coverage is robust enough for high-density GTA traffic but efficient enough that you aren't overpaying. Whether it's adjusting for how your car is stored or how many kilometres you drive annually, customizable car insurance policies make your insurance work for you. It's about creating a policy that feels as personal as the car you drive.
Building Your Policy: Mandatory Coverage vs. Optional Endorsements
In Ontario, every policy rests on a foundation of four mandatory pillars. These are Third-Party Liability, Statutory Accident Benefits, Uninsured Automobile coverage, and Direct Compensation-Property Damage (DC-PD). While the Financial Services Regulatory Authority of Ontario (FSRA) sets the legal minimum for liability at $200,000, this amount is rarely enough to protect your assets in a modern legal environment. Most drivers in Markham and the GTA opt for $1 million or $2 million to account for the high costs of medical claims and potential lawsuits.
The "no-fault" system often confuses people. It doesn't mean no one is responsible for a collision. Instead, it means you deal with your own insurance company for medical benefits and car repairs, regardless of who caused the accident. This structure makes customizable car insurance policies essential; you're essentially building a safety net that you trust to support you directly when things go wrong. By understanding how these pieces fit together, you can avoid the fear of being underinsured in a complex traffic environment.
Essential Ontario Endorsements (OPCFs) to Consider
Ontario Policy Change Forms, or OPCFs, are the primary tools used to fine-tune your protection. They allow you to add specific coverage that isn't included in a standard policy. Here are three common ones that add significant value:
- OPCF 20 (Transportation Replacement): If your car is in the shop after a claim, this pays for a rental vehicle so you can still get to work or run errands.
- OPCF 27 (Liability for Non-Owned Vehicles): This extends your existing coverage to vehicles you rent or borrow, which is often more cost-effective than buying insurance at a rental counter.
- OPCF 43 (Removing Depreciation): For those with a new vehicle, this ensures you receive the full purchase price rather than a depreciated value if the car is totalled within a specific timeframe.
Customizing Your Accident Benefits
As of July 1, 2026, Ontario's "à la carte" system gives you more control over your accident benefits. You can now choose whether to purchase optional benefits like income replacement, caregiver assistance, or increased medical and rehabilitation limits. Before deciding, it's wise to review your existing employer health plans. If your workplace already provides robust disability coverage, you might choose to stick with the standard auto limits. However, if you're self-employed or have dependants, enhancing these limits ensures your family is protected without gaps. If you're unsure which options fit your life, you can consult with a broker to review your current workplace benefits against your auto policy requirements.
Tailoring Coverage to Your Lifestyle: Common Customization Scenarios
Every driver in Ontario has a unique routine, which means a generic policy rarely provides the best value. Customizable car insurance policies allow you to adjust your protection based on how often and where you drive. If you're a remote worker in Markham or Vaughan, you might spend very little time on the road. In this case, exploring low-mileage discounts or usage-based insurance (UBI) can help align your costs with your actual vehicle use. It's a practical way to ensure you aren't paying for road time you don't actually use.
Conversely, a daily GTA commuter facing the 401 or the Don Valley Parkway has different needs. These drivers often benefit from enhancing their collision and comprehensive coverage to handle the higher risks of dense highway travel. For multi-vehicle households, leveraging home and auto insurance bundles in Ontario is a smart way to streamline protection while maximizing value across all assets. New drivers also face a unique challenge. They must balance higher premiums with the need for robust accident benefit protection, ensuring they aren't left vulnerable during their early years on the road.
Customizing for High-Value or Modified Vehicles
If you've invested in a unique build or a high-end vehicle, standard "Actual Cash Value" coverage might not be enough. You should consider "Agreed Value" coverage. This guarantees a specific payout amount in the event of a total loss, rather than a depreciated market value. This is one of many optional coverage choices that can be added to your policy to protect your investment. It's also vital to ensure that any aftermarket parts, custom paint, or high-end electronics are explicitly listed. In Ontario, insurers often require specialized vehicle appraisals to verify the value of these modifications before they'll bind the coverage.
The 'Occasional Driver' Strategy
Adding a student or a family member to your policy doesn't always require paying full-time primary driver rates. By listing them as an occasional driver, you can maintain protection without the heavy cost of a separate policy. Many Ontario insurers now offer telematics programs that use a smartphone app to prove safe driving habits. This is a great way for young drivers in Richmond Hill or Toronto to build a positive insurance history while unlocking potential discounts. For students living away from home, linking their auto coverage with tenant insurance for students creates a holistic plan that protects their belongings and their liability simultaneously. These strategies ensure that customizable car insurance policies grow and change alongside your family's needs.
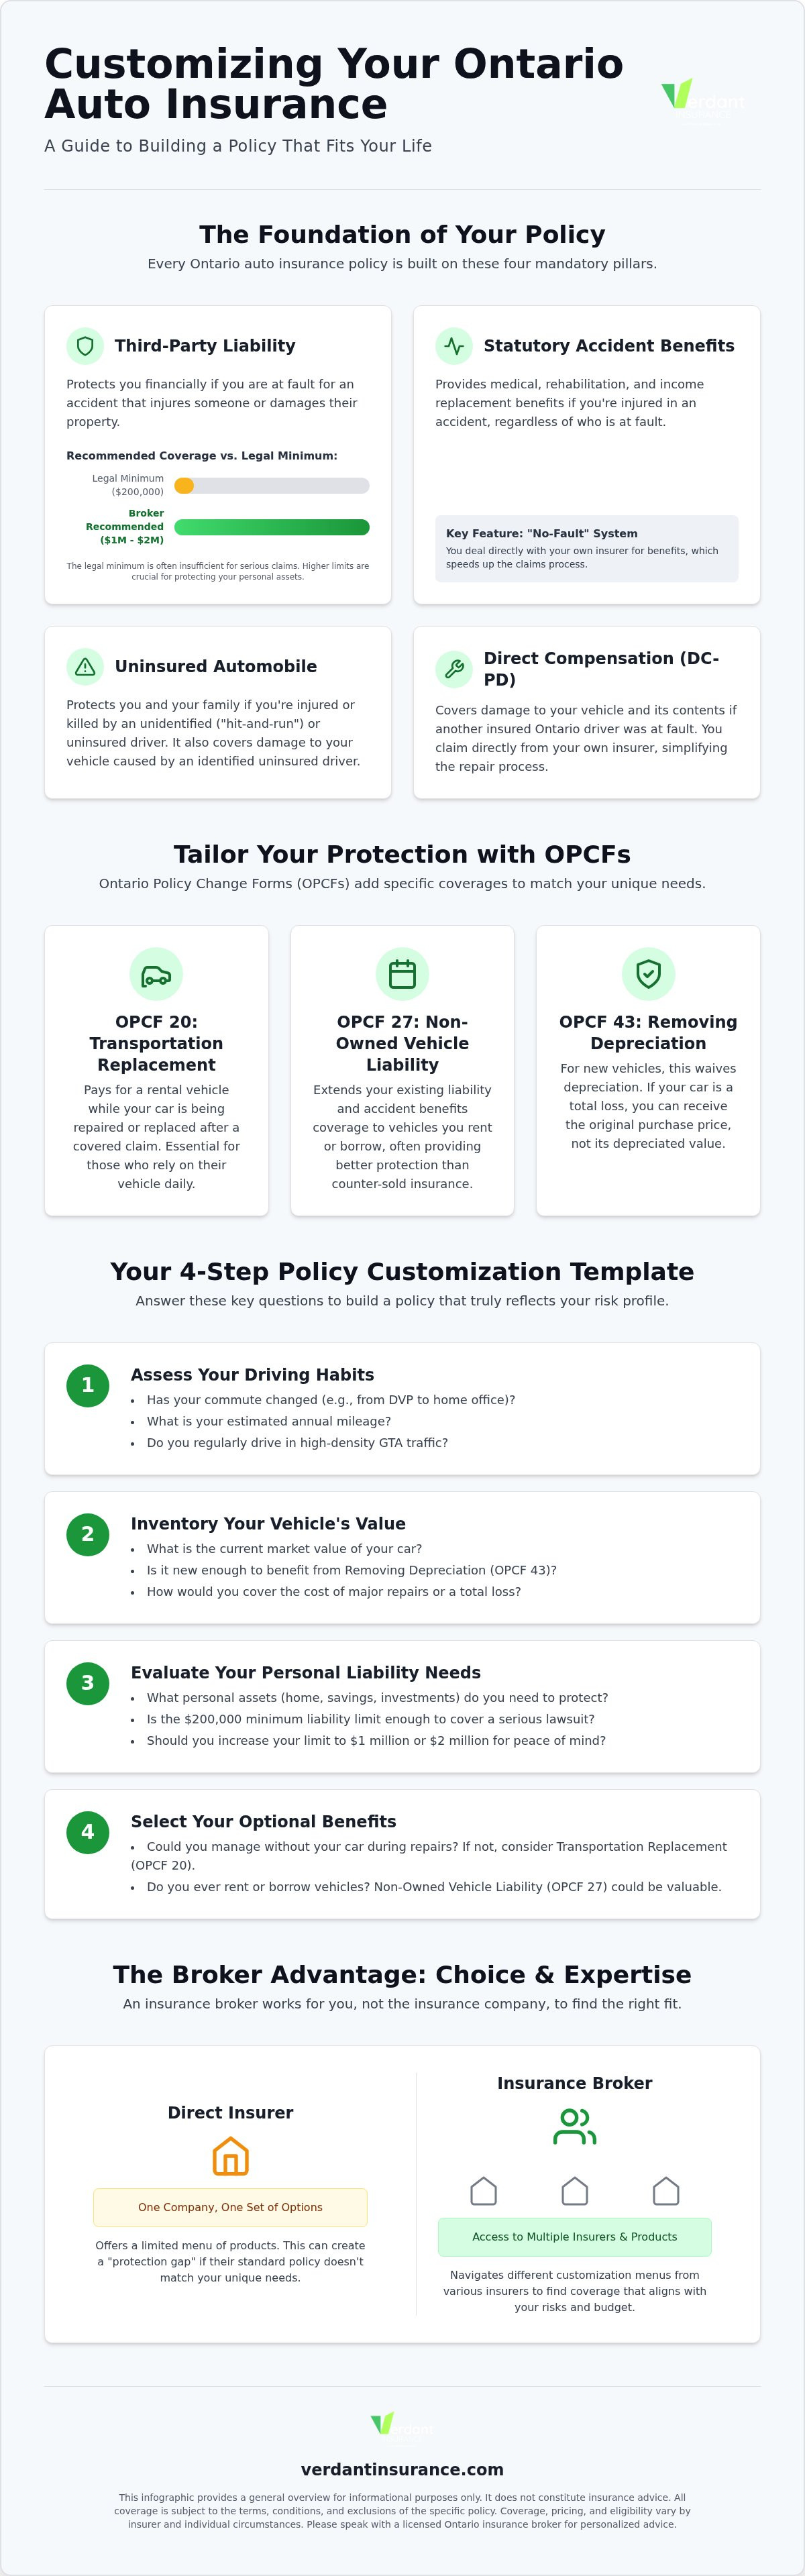
The Ontario Driver's Policy Customization Template
Building customizable car insurance policies shouldn't feel like guesswork. It's a methodical process of aligning your financial reality with your daily habits. Follow these five steps to create your personal insurance blueprint before you sign your next renewal or purchase a new vehicle.
- Step 1: Inventory your assets. Evaluate your vehicle's current market value and whether it is leased or financed. If you have significant personal assets, you'll likely need higher liability limits beyond the provincial minimum to protect your financial future.
- Step 2: Define your usage. Be honest about your annual kilometres and who actually drives the vehicle. Are you a weekend driver in Richmond Hill or a daily commuter to downtown Toronto? Identifying whether you need primary or occasional driver designations is a simple way to keep your policy accurate.
- Step 3: Select your 'Must-Have' Endorsements. Use the OPCF codes we previously explored. For those with a brand-new vehicle, OPCF 43 is a vital addition. If you rely on your car for work, ensuring you have OPCF 20 for a rental replacement is essential for your daily routine.
- Step 4: Determine your risk tolerance. Deciding on your deductible is a major part of the process. Choosing a $1,000 deductible instead of $500 can lower your premium, but you must ensure you have that amount ready in your emergency fund.
- Step 5: Review external benefits. Check your credit card for rental car collision coverage and your workplace health plan for disability or medical benefits. This prevents you from paying for redundant protection that you already access through other channels.
If you're still deciding which vehicle to purchase, it can help to get an insurance quote before buying the car so you can compare the insurance cost of different options before signing.
Preparing for Your Broker Consultation
Coming prepared makes the consultation process effortless for everyone involved. Have your driver's license history, your current policy "dec" page, and your vehicle's VIN ready. Ask your broker which insurers on their panel offer discounts for your specific profession or alumni group. This preparation helps you compare cheap car insurance Canada quotes effectively while ensuring the quality of your coverage remains high.
The Annual Customization Audit
Your life doesn't stay the same, so your insurance shouldn't either. Re-evaluate your policy every 12 months to ensure it still reflects your reality. Major life events like moving to a new GTA neighbourhood, getting married, or changing jobs can significantly impact your risk profile. A quick check-in ensures you're still eligible for the 30% claim-free discount and that your customizable car insurance policies still fit your current lifestyle and budget.
Speak with a Verdant broker to customize your auto policy
How a Verdant Insurance Broker Personalizes Your Protection
The Verdant Advantage lies in our ability to access a wide network of Ontario's leading insurance carriers. Because we aren't tied to a single insurance company, we can shop the market to find the specific "menu" of options that fits your life. This brokerage model is the engine behind truly customizable car insurance policies. Our team takes a "Friendly Expert" approach, stripping away the technical jargon of OPCFs and limits to provide you with a clear, honest picture of your protection.
We understand that modern drivers want efficiency, but they also want to know there's a real person behind the screen. We bridge the gap between being a digital insurance broker and providing deeply personal service. Our deep local knowledge of Markham, Toronto, and the GTA means we understand the specific risks you face, from the icy curves of the York Region backroads to the bumper-to-bumper traffic on the Don Valley Parkway.
From Online Quote to Bound Policy
The journey to a better policy starts with a few clicks. Our online quote tool kickstarts the customization process by gathering the essential data about your vehicle and driving history. However, we don't stop at the algorithm. Once you have your initial results, our licensed brokers step in to fine-tune your template. We'll look for potential discounts you might have missed or suggest adjustments to your accident benefits based on your current lifestyle. This collaborative process ensures you can finalize your policy with total confidence and clarity.
Ongoing Support and Claims Advocacy
Customization matters most when it's time to file a claim. If you've engineered your policy correctly, you won't face surprises when you need support. Our Markham-based team acts as your advocate, guiding you through the process and ensuring your insurer honours the specific terms of your tailored coverage. As your life changes, perhaps you've moved to Richmond Hill or started a new remote role, we're here to adjust your protection accordingly. Ready to build your policy? Speak with a Verdant broker today and experience the peace of mind that comes with a policy built just for you.
Securing Your Future on Ontario Roads
Building a policy that reflects your unique life in the GTA is about more than just checking boxes. By leveraging the 2026 provincial reforms and using our customization template, you can ensure your protection is as dynamic as your daily commute. Whether you are navigating Toronto traffic or working from a home office in Markham, customizable car insurance policies provide the flexibility to align your premiums with your actual risks. You no longer have to settle for a generic plan that ignores your specific lifestyle and driving habits.
Our Markham-based brokers are ready to act as your proactive guides through this process. We provide access to multiple top-rated Ontario insurers and specialize in finding savings of up to 30% for safe, conviction-free drivers. We take pride in simplifying the complex world of accident benefits and endorsements, ensuring you have total clarity before you sign. Our goal is to make your insurance experience transparent and entirely stress-free.
Get Your Personalized Ontario Auto Quote You deserve a policy that works for you every kilometre of the way. Let's build a safety net that offers genuine peace of mind and reflects the way you drive today. We're here to make the journey toward better protection effortless and supportive.
Frequently Asked Questions
Can I customize my car insurance policy at any time, or only at renewal?
You can customize your coverage at any point during your policy term. While many people wait until their renewal date, you don't have to wait to update your information. If you move to a new area like Richmond Hill or change your commute, you should contact your broker immediately. Making mid-term adjustments ensures your protection remains accurate. Keep in mind that changes might result in a premium adjustment depending on your insurer's specific rules.
What is the most important optional endorsement for Ontario drivers?
Many experts consider the OPCF 44R (Family Protection Coverage) essential for Ontario drivers. This endorsement protects you and your family if you're involved in an accident with an underinsured or hit-and-run driver. While customizable car insurance policies allow for many choices, this specific addition provides vital financial security in the high-traffic environments of Toronto and the GTA. It bridges the gap between another driver's low liability limits and your own higher level of protection.
Does customizing my policy always make the premium more expensive?
No, tailoring your policy can actually lead to lower premiums in many cases. Customization is about aligning your coverage with your actual risks, which often means removing expensive options you don't need. For example, if you work remotely in Markham and drive fewer than 5,000 kilometres annually, you might qualify for significant low-mileage discounts. By refining your customizable car insurance policies to reflect your real-world habits, you ensure every dollar spent provides meaningful protection.
How do I know if I'm over-insured on my current Ontario auto policy?
You might be over-insured if you're paying for benefits already provided by other sources. A common example is paying for transportation replacement (OPCF 20) when you already have access to a second household vehicle. You should also review your workplace health benefits; if you have robust long-term disability coverage, you might not need the highest optional accident benefit limits. A quick audit with a broker can identify these redundancies and help you streamline your costs.
Are there specific customizable options for electric vehicles in Ontario?
Yes, many Ontario insurers now offer specific customization options for electric vehicle owners. These can include specialized endorsements for home charging stations or discounts for driving a "green" vehicle. Some policies also provide unique roadside assistance tailored to EV needs, such as towing to the nearest charging point. Since these offerings vary significantly by company, it's helpful to have a broker compare different insurers to find the best fit for your specific EV model and charging habits.
Can a broker help me find discounts that aren't listed on standard quote sites?
A broker can definitely find specialized discounts that generic quote engines often miss. These include savings for members of specific professional associations, alumni groups, or even certain employers. Brokers also have access to niche insurance companies that don't advertise on major comparison sites. By understanding your full background, a broker can uncover these "hidden" opportunities to lower your rates while maintaining the high quality of your property and casualty coverage across Ontario.
What happens if I customize my policy but then my driving habits change mid-year?
If your driving habits change mid-year, you should notify your broker as soon as possible to update your policy. Whether you've started a new job with a longer commute or decided to store your vehicle for the winter, your policy should reflect these shifts. Failing to update your usage could impact your coverage during a claim. Most insurers allow you to adjust your annual kilometre estimates or driver status at any time, ensuring your protection stays current.
Is usage-based insurance (telematics) considered a form of customization?
Usage-based insurance is a very effective form of customization for modern drivers. By using telematics to track your actual driving behavior, insurers can offer personalized rates that reflect how safely and how often you drive. This is a great way for safe drivers in Vaughan or Markham to prove their low-risk status. It moves away from traditional group statistics and focuses entirely on your individual performance on the road, often leading to earned discounts for safe habits.


