

Did you know that the "standard" auto insurance policy you've relied on for years fundamentally changed on July 1, 2026? Most Ontario drivers looking to get insurance quote online Canada expect a simple price comparison, but the recent overhaul of Statutory Accident Benefits means that "standard" doesn't mean what it used to. It's frustrating to spend time on a digital form only to worry if the final price includes hidden costs or leaves you underinsured. We understand that you want a process that's both fast and transparent.
You're about to learn exactly how to navigate this new landscape to find coverage that fits your unique lifestyle and budget. We'll walk you through the required documents you need to have ready and explain why many previously mandatory benefits are now optional choices you must actively select. By the end of this guide, you'll feel confident choosing the right limits and understand how a local Ontario broker can help you turn a generic online quote into a personalized plan that truly protects you.
Key Takeaways
- Distinguish between a direct insurer and an Ontario brokerage to find a partner that offers professional advice rather than just a one-size-fits-all policy.
- Identify the specific documents required for an Ontario quote to prevent unexpected price changes when you're ready to finalize your coverage.
- Navigate the 2026 Ontario auto insurance reforms with confidence when you get insurance quote online Canada by understanding which accident benefits are now optional.
- Learn to evaluate technical terms like "Replacement Cost" and "Liability Limits" so you can choose a policy that matches your budget and risk tolerance.
- Transition smoothly from a preliminary digital estimate to a bound policy with a broker's review to ensure no eligible discounts are left on the table.
Understanding the Digital Insurance Landscape in Ontario
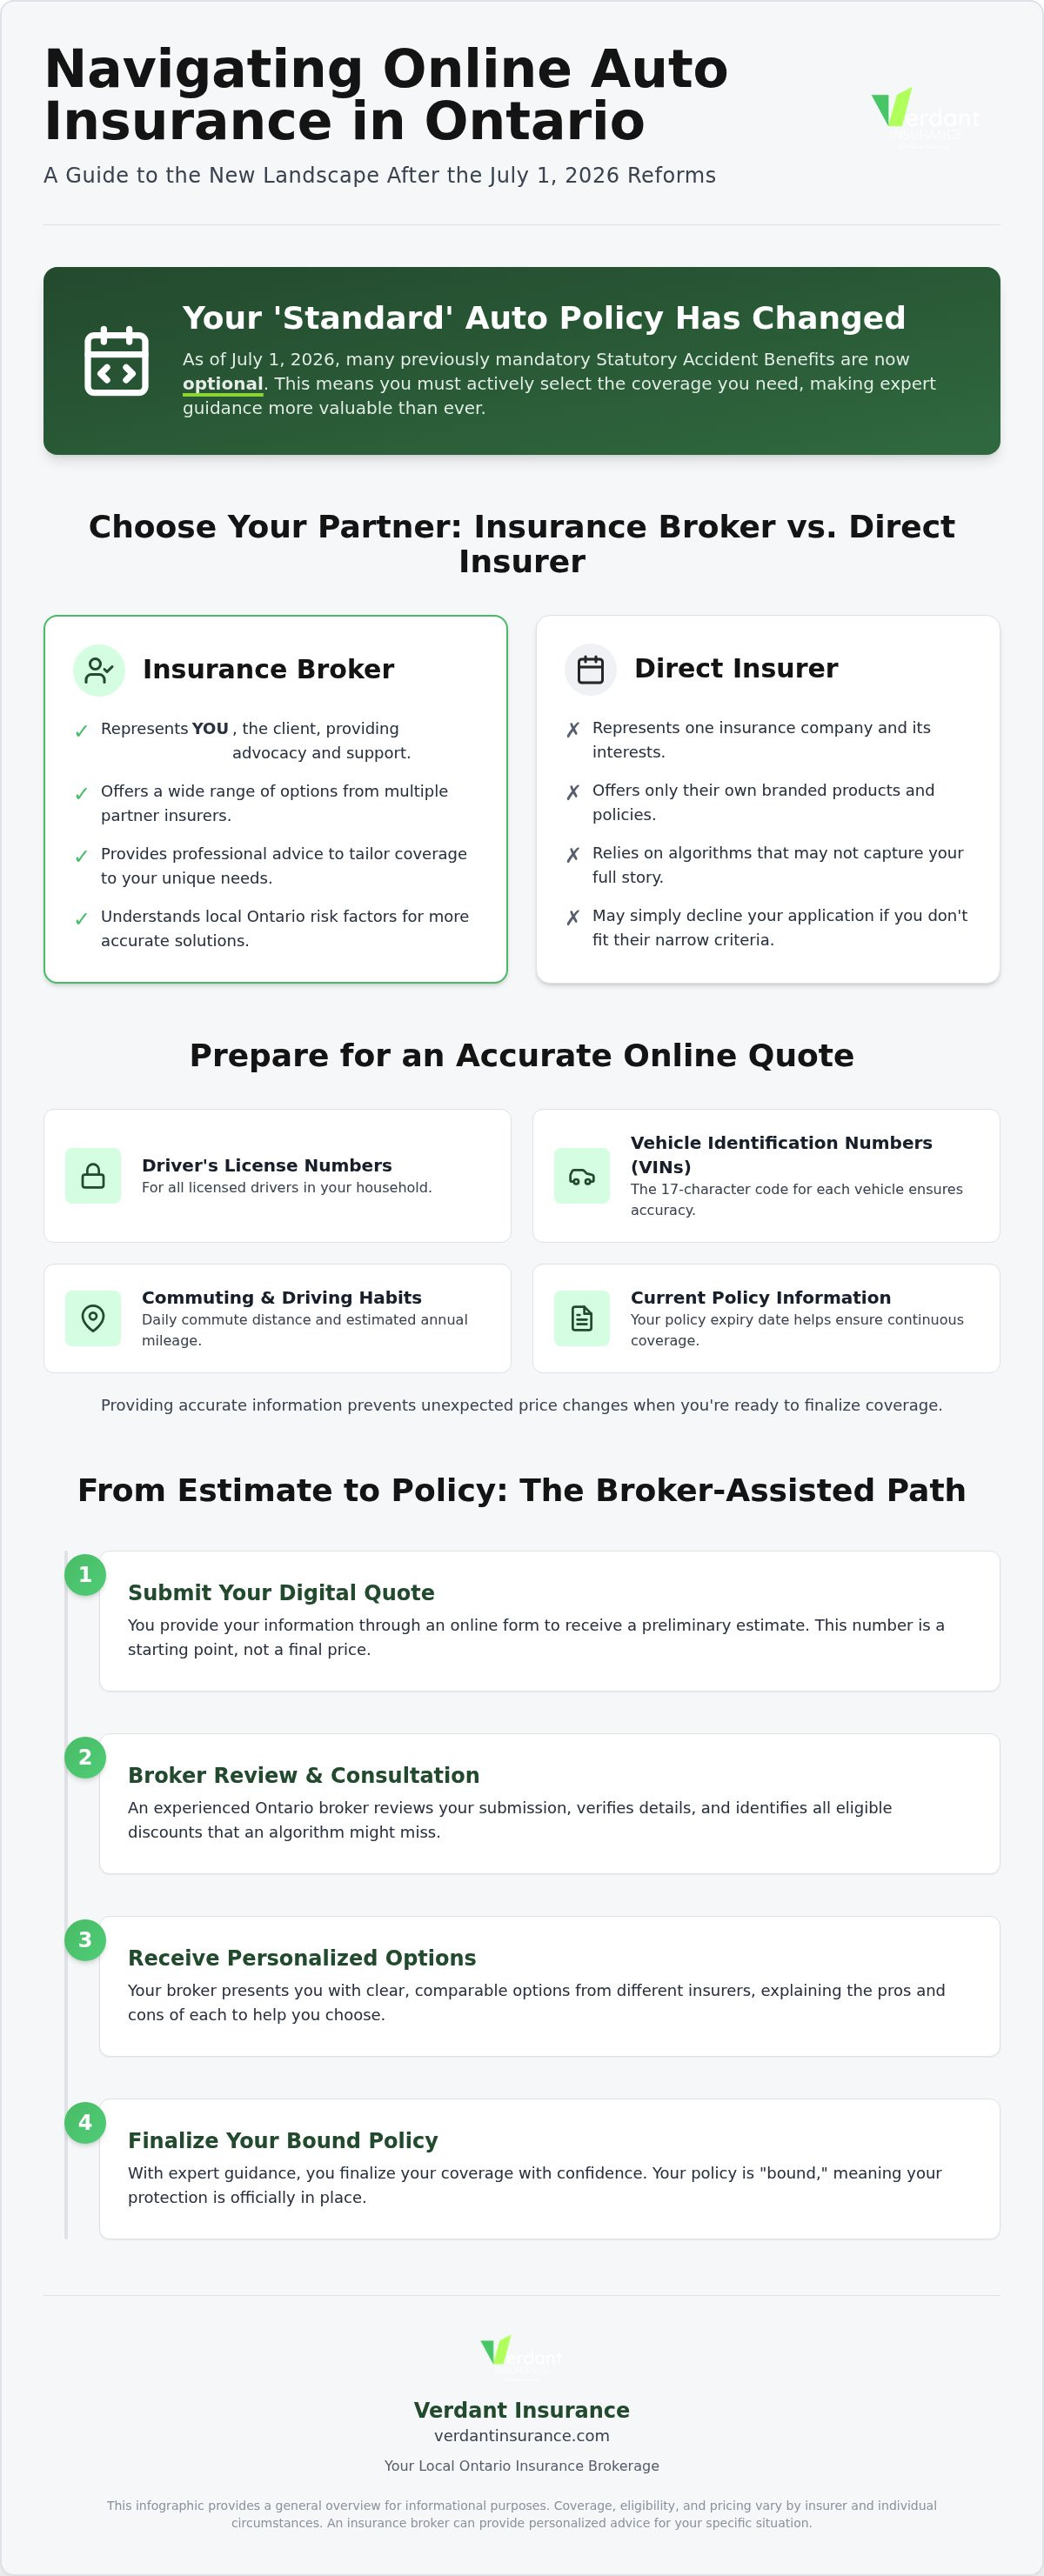
When you look to get insurance quote online Canada, you're essentially requesting a preliminary estimate rather than a final contract. This figure is a calculation based on the specific data points you provide during the digital intake. In Ontario's evolving digital insurance landscape, these estimates are always subject to specific insurer eligibility and underwriting rules. Since the major system overhaul on July 1, 2026, these digital forms have become more detailed because many previously standard accident benefits are now optional selections you must actively choose.
There's a significant difference between clicking a link from a direct bank and using a brokerage platform. A direct insurer only offers their own branded products. If your specific situation doesn't fit their narrow criteria, they simply decline the risk. An Ontario brokerage works as your ally. We connect you to multiple partner carriers, allowing you to see a broader range of available options without needing to fill out separate forms for every company. This model is particularly helpful for Ontario residents who want to compare different coverage levels side-by-side.
The Role of an Ontario Insurance Broker
A broker acts as your personal advocate throughout the quoting process. Instead of representing a single insurance company, we represent you. In communities like Markham, Richmond Hill, or the wider GTA, having a local expert review your digital quote provides a layer of security that an algorithm cannot match. We understand local risk factors, such as specific regional weather patterns or traffic trends, that might influence your premiums. Because we have access to various insurance partners, we can find tailored coverage that aligns with your budget while ensuring you remain compliant with provincial laws.
Digital Convenience vs. Professional Advice
Speed is a great benefit of modern technology, but accuracy is far more important for your financial protection. While many websites promise "instant" results, these are usually just the first step in a larger conversation. If the information entered into a digital form is even slightly inaccurate, your final premium could change significantly once the policy is actually bound. Professional advice helps ensure you don't pay for unnecessary add-ons while also preventing you from skipping benefits that protect your income. Under the Registered Insurance Brokers Act, an insurance broker in Ontario is defined as an independent professional who acts as an intermediary between a client and an insurance company to provide advice and secure coverage.
Preparing Your Information: What You Need for an Accurate Online Quote
Accuracy is the secret to a smooth experience. When you look to get insurance quote online Canada, the number you see on the screen is only as reliable as the data you put in. Many people rush through the forms, but being precise prevents the "sticker shock" that can happen when an insurer verifies your history later. The Ontario insurance regulator (FSRA) ensures that companies follow filed rules, so if your information changes during the verification stage, your premium will too.
Your history plays a massive role in the final outcome. For instance, drivers with claim-free and conviction-free records often qualify for lower rates than those with recent incidents. Having your current policy's expiry date handy is also vital. It helps you time your transition perfectly, avoiding mid-term cancellation fees while ensuring you don't have a gap in coverage. If you aren't sure where to find these details, a quick look at your current "pink slip" or policy declaration page is the best place to start.
Checklist for Auto Insurance Quotes
Before you start your digital application, gather these specific details to ensure your estimate is as close to the final price as possible:
- Driver's license numbers: You'll need these for every licensed driver in your household to check their experience level and record.
- Vehicle Identification Numbers (VIN): This 17-character code provides the exact trim level and safety features of your car, which influences the rate.
- Commuting habits: Be ready to state your one-way daily commute distance and your total estimated annual mileage.
If you're a new driver or looking for ways to manage your premiums, our Cheap Car Insurance Canada: Ultimate Buying Guide 2026 provides deeper insights into the specific factors that influence your rate in Ontario.
Checklist for Home and Tenant Insurance Quotes
Property quotes require a different set of data points focused on the physical structure and its location. Insurers use this info to gauge the likelihood of a claim.
- Property updates: Know the age of your roof and the types of plumbing and heating systems in the home.
- Fire protection: Check your approximate distance to the nearest fire hydrant and the local fire station.
- Content value: For those renting, calculate the total value of your belongings, including electronics, clothing, and furniture.
Renters can find more specific tips in our Tenant Insurance Affordable Canada: Your 2026 Renter’s Buying Guide. If you find these details confusing, reaching out to a Verdant broker can help clarify exactly what information is needed for your specific situation.
Navigating the Online Quote Process: From Form to Comparison
The journey usually begins with a few simple details, like your postal code and the type of coverage you need. Most Ontario forms follow a logical sequence: personal information, details about your vehicle or property, and finally, your insurance history. One of the most effective ways to simplify this process is to look for the "bundling" option early on. Combining your home and auto insurance into a single inquiry doesn't just save time; it often unlocks discounts that aren't available for standalone policies. As you move through the screens, you'll encounter a list of coverage limits and deductibles. Since the July 1, 2026, reforms, you'll also see a section for optional benefits like income replacement or caregiver assistance. Take your time here; these choices directly impact your financial security after an accident.
Filling Out the Digital Form with Confidence
It's natural to feel a bit of pressure when faced with technical questions about your home's wiring or your car's annual mileage. The key is to provide the most accurate estimate possible. If you're unsure about a specific detail, it's better to look it up than to guess. Honesty about past claims or driving convictions is particularly vital. While it might be tempting to omit a minor ticket, insurers will eventually discover it during the underwriting process, which could lead to a sudden price increase or even a declined application. At Verdant, our digital platform is designed specifically for Ontario residents, making these steps feel less like a chore and more like a clear path to protection.
Comparing Multiple Quotes Effectively
Once you've submitted your details to get insurance quote online Canada, you'll likely receive a list of different options. It's important to remember that the lowest price on the list isn't always the best value. To truly compare "apples to apples," you need to look beyond the monthly premium. Check that the liability limits, deductibles, and optional endorsements are identical across all quotes. The Insurance Bureau of Canada suggests that consumers pay close attention to how different insurers handle replacement costs and specific exclusions. If you're feeling overwhelmed by the variety of choices, our guide on Choosing an Online Insurance Broker in Canada: An Ontario Digital Guide can help you decide which partner is right for you. A broker can help you spot the nuances between quotes that a simple price-sorting tool might miss, ensuring you don't sacrifice essential protection for a slightly lower bill.
How to Evaluate Your Insurance Quotes and Coverage Options
Once you've taken the steps to get insurance quote online Canada, the next phase is making sense of the numbers. In Ontario, an auto quote isn't just a single price; it's a bundle of specific protections. You'll see Third-Party Liability, which covers you if you're responsible for an accident, and Direct Compensation Property Damage (DCPD), a unique Ontario regulation where your own insurer handles your vehicle repairs when you aren't at fault. Since the July 1, 2026, reforms, the Accident Benefits section requires extra attention. This is where you decide which financial protections, like income replacement, are worth the additional premium based on your personal health coverage and workplace benefits.
Home insurance quotes involve different but equally important terms. You'll often choose between "Replacement Cost," which pays to replace your belongings at today's market prices, and "Actual Cash Value," which only pays the depreciated value of the item. Your chosen deductible also plays a major role in the premium you see. A higher deductible typically lowers your monthly cost, but it means you'll pay more out of pocket if you need to make a claim. Balancing these factors is how you move from a generic estimate to a plan that fits your life in the GTA or York Region.
Mandatory vs. Optional Coverage in Ontario
Ontario law requires every driver to carry a minimum amount of Third-Party Liability, Accident Benefits, and Uninsured Automobile coverage. However, the "standard" policy often leaves gaps that optional endorsements can fill. You might see options for "Loss of Use," which provides a rental car while yours is in the shop, or "Sewer Back-up" for your home policy. It's vital to remember that actual coverage is always subject to the insurer's specific policy wording and exclusions. A quote is a helpful guide, but the fine print in the final policy is what determines how you're protected during a crisis.
Identifying Potential Savings
Finding value doesn't always mean cutting coverage. Many Ontario insurers offer significant discounts for safe habits and proactive choices. For example, staying claim-free and conviction-free can lead to savings of up to 30% with certain partner carriers. Most Ontario carriers define a "clean record" as having no at-fault accidents and no minor, major, or criminal driving convictions within the last three to six years. Other common ways to lower your Ontario quote include:
- Installing certified winter tires (a mandatory discount in Ontario).
- Having a professionally monitored alarm system in your home.
- Maintaining a membership in certain professional associations or alumni groups.
- Bundling multiple vehicles or combining home and auto policies.
Explore Ontario auto insurance options
Finalising Your Coverage with an Ontario Insurance Broker
Completing the digital form is a major milestone in your journey. When you use a tool to get insurance quote online Canada, you receive a sophisticated estimate based on the data points you provided. However, the transition from a screen-based number to a legally active contract requires a specific process known as binding. This is where the expertise of an Ontario broker becomes your most valuable asset. We don't just process the paperwork; we perform a comprehensive audit of your application to ensure every detail is accurate. This human review is the final safeguard that ensures you aren't overpaying or missing out on regional credits that an automated system might overlook.
The Verification and Binding Process
Once you submit your information to get insurance quote online Canada, the broker review phase begins. During this time, we may ask for additional documentation such as a driver abstract or proof of prior insurance from your previous carrier. These documents verify your history and ensure that the rate you were quoted matches the reality of your record. It's vital to understand that your coverage is not active the moment you click "submit." Protection only begins once the insurer formally binds the policy, a step that your broker coordinates to ensure there are no gaps in your safety net. We guide you through this verification stage to make it feel effortless and transparent.
Local Support for Your Long-Term Peace of Mind
For residents in Markham, Vaughan, or across the GTA, working with a local brokerage offers a level of service that large, national institutions often lack. We understand the specific risks associated with driving in York Region or owning a home in a specific Toronto neighbourhood, such as regional trends in vehicle theft or local water damage risks. This local insight allows us to provide advice that is actually relevant to your daily life. Beyond the initial setup, we provide ongoing support, including annual policy reviews to ensure your coverage keeps pace with life changes like a new car, a home renovation, or a change in your daily commute.
If you've started the process online and want to ensure your final policy is as robust as possible, we invite you to speak with a Markham insurance broker at Verdant. Our team is ready to review your digital quote and provide the professional clarity you need to move forward with confidence. We take pride in being a proactive guide for our neighbours, ensuring that your insurance experience is defined by reliability and personal care rather than just a digital form.
Secure Your Future with Professional Ontario Advice
Finding the right coverage doesn't have to be a source of stress. By understanding the 2026 shifts in accident benefits and preparing your documentation in advance, you've already simplified the path to protection. When you look to get insurance quote online Canada, remember that the digital estimate is just your starting point. The real security comes from a professional review that ensures your policy matches your life in Markham or the GTA. Our Ontario-licensed brokers are specialists in identifying discounts for claim-free drivers and tailoring plans that respect your budget. We're here to turn your digital inquiry into a bound policy that offers genuine peace of mind.
You deserve a partner who values your time and prioritizes your safety. We take pride in our Markham-based local expertise and our commitment to making insurance accessible for every neighbour. Whether you're navigating new provincial regulations or looking to bundle your home and auto, we're ready to assist. Let's work together to make your insurance experience straightforward, transparent, and supportive.
Get your personalized Ontario insurance quote with Verdant Insurance today You don't necessarily need to own the vehicle yet. Verdant can help you quote a vehicle before you buy it so you can understand the insurance cost before finalizing your purchase.
Frequently Asked Questions
Is an online insurance quote in Ontario legally binding?
An online insurance quote is not legally binding; it is a preliminary estimate based on the information you provide. The final contract only becomes active once an Ontario broker reviews your details and the insurance company formally binds the policy. This process ensures that all data points, such as your driving abstract and property details, are verified for accuracy. Until you receive a policy number and confirmation, you aren't officially covered.
How long does it take to get an insurance quote online in Canada?
It typically takes between five and ten minutes to get insurance quote online Canada when you have your documents ready. The speed of the process depends on whether you have your driver's license, vehicle identification number, and current policy details on hand. While the initial digital intake is fast, remember that a broker review is necessary to finalize the coverage and ensure you've selected the right optional benefits for your lifestyle.
Will getting an insurance quote online affect my credit score in Ontario?
No, obtaining a quote won't lower your credit score in Ontario. Most insurance providers perform what's known as a "soft inquiry" to determine your eligibility for certain rate tiers or payment plans. Unlike the "hard hits" used by lenders for car loans or mortgages, these soft inquiries are not visible to other creditors. You can compare multiple options without worrying about any negative impact on your financial standing or credit history.
Can I get a quote for a car I haven’t bought yet?
Yes, you can absolutely request a quote for a vehicle you're considering but haven't yet purchased. This is a smart way to compare the long-term costs of different makes and models before you sign a bill of sale. You just need the year, make, and model; or ideally the VIN; to see how that specific vehicle impacts your premium. It helps you make a more informed decision at the dealership.
Why is my final insurance premium different from the online quote?
Your final premium might differ from the digital estimate if the reports pulled during underwriting reveal new information. When a broker verifies your history, they check provincial databases for accidents or driving convictions that might have been missed in the initial form. Changes to coverage limits or the addition of optional endorsements after the July 2026 reforms can also adjust the price. Accuracy during the intake phase is the best way to keep these numbers stable.
Do I need to live in Markham to use Verdant Insurance?
You don't need to live in Markham to work with Verdant Insurance; we serve consumers and businesses throughout all of Ontario. While our physical office is located in Markham, our digital platform and brokers support clients in Toronto, Vaughan, Richmond Hill, and rural communities across the province. We provide the same expert guidance and access to multiple partner carriers whether you're in the GTA or elsewhere in Ontario.
What is the most important factor in lowering my Ontario insurance quote?
Maintaining a clean driving record is the most significant factor in lowering your premium. Most Ontario carriers define this as having no at-fault accidents or driving convictions within the last three to six years. Safe drivers can see savings of up to 30% with our partner carriers. Other factors like installing winter tires or bundling your home and auto policies also help, but your personal history remains the primary driver of your rate.
Can I bundle business and home insurance in one online quote?
While most digital platforms use separate forms for business and home insurance, a broker can help you coordinate these policies for maximum efficiency. You can start by submitting your information for each line individually to get insurance quote online Canada. Once you connect with a Verdant broker, we'll review both files to see if any multi-policy discounts or specialized commercial packages apply to your specific situation, ensuring your total protection is seamless.


