

Did you know that overall commercial insurance rates in Canada actually declined by 6% in the first quarter of 2026? Most entrepreneurs expect their overhead to climb every year, especially with inflation and rising input costs weighing on their minds. It's frustrating to feel like you're paying a premium for business insurance you don't fully understand, or worse, getting stuck in a mess of technical jargon. You want to protect what you've built, but the manual process of calling brokers can feel like a full time job.
This guide will show you how to cut through the noise, master the essentials of commercial coverage, and secure the best quotes available in today's market. We'll break down which coverages are mandatory for your specific industry, how to leverage the current softening market to your advantage, and how to use digital tools to compare carriers in minutes rather than days. You deserve the peace of mind that comes from knowing your livelihood is secure without the headache of endless paperwork.
Key Takeaways
- Understand how 2026 market shifts, including softening rates for many sectors, allow you to strengthen your safety net without breaking the bank.
- Learn to identify exactly which coverage types fit your specific industry so you can avoid paying for protection you'll never use.
- Discover the broker advantage and how comparing multiple business insurance quotes ensures you get the most competitive rates in the Canadian market.
- Master a fast, digital-first application process that replaces slow manual paperwork with clear, actionable steps for immediate coverage.
- Find out how a proactive Ontario guide can help you navigate technical jargon and secure your livelihood with confidence.
Why Business Insurance is Your Company’s Foundation in 2026
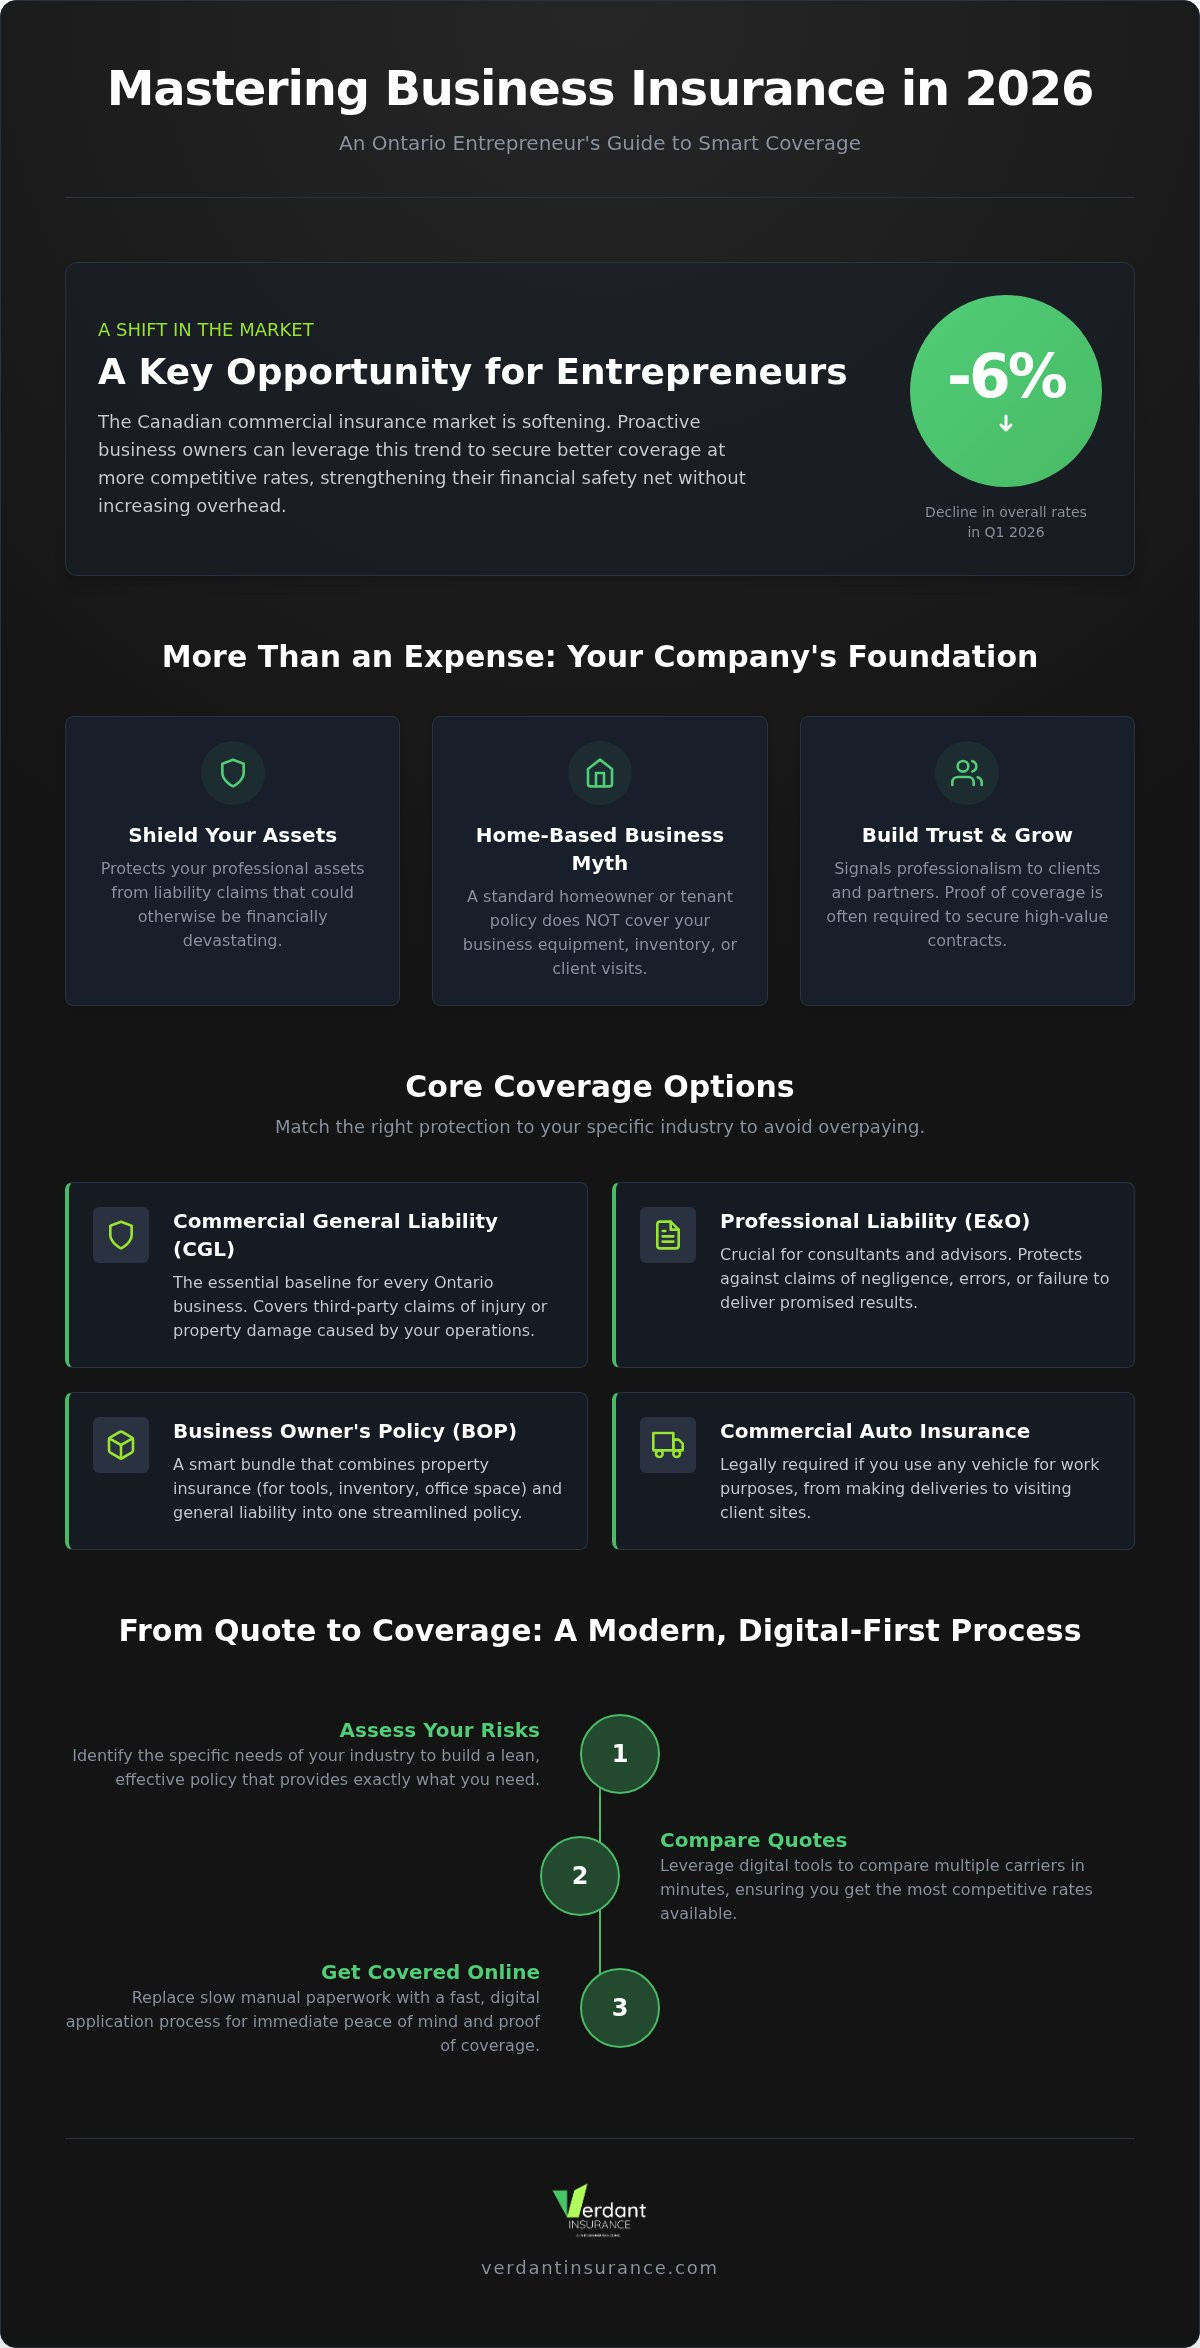
Building a business in 2026 feels like a balancing act. While overall commercial insurance rates in Canada declined by 6% in the first quarter of the year, other costs like inflation and transportation continue to rise. Think of business insurance as your company’s foundation rather than just another line item on your expense sheet. It acts as a safety net for your professional assets and shields you from liability that could otherwise end your journey before it truly begins.
Don't fall into the common "Home-Based Business" trap. Many entrepreneurs assume their homeowner or tenant policy covers their laptop, inventory, or client visits. It doesn't. Standard residential policies usually exclude business activities, making a dedicated business insurance policy essential for keeping your personal life and professional dreams separate and secure. A single mishap in your home office could leave you personally responsible for thousands in damages without the right coverage.
Beyond protection, insurance is a growth tool. Modern clients and partners are more risk-averse than ever. Having a robust policy isn't just about safety; it's about building trust. It signals that you're a professional who takes responsibility seriously, which is often the deciding factor in securing high-value contracts and building long-term partnerships.
The Legal and Contractual Reality in Ontario
In Canada, certain types of insurance are legally required depending on your industry and whether you have employees. For example, if you use a vehicle for work, commercial auto insurance is a must, especially as premiums in this sector continue to climb. Most independent contractors find that clients won't even sign a work order without proof of coverage. Commercial General Liability is the baseline for every Ontario business. It protects you if a third party gets hurt or their property is damaged because of your operations.
Protecting Your Digital and Physical Assets
Your assets aren't just the tools in your van or the furniture in your office. In 2026, protecting intangible assets like data and your reputation is just as vital as protecting your storefront. A Business Owner's Policy often bundles these protections together, offering a streamlined way to cover both physical property and liability in one package.
Physical property coverage remains a cornerstone for retail and trades, but the focus has shifted toward resilience. Canadian businesses are increasingly looking for coverage that accounts for natural disasters and climate-related disruptions. Whether it's a flood in the GTA or a storm in the Maritimes, your policy should ensure you can rebuild and resume operations without draining your life savings. This proactive approach to risk management helps you stay operational when others might be forced to close their doors.
Core Coverage Options: Matching Protection to Your Industry
Insurance often feels like an alphabet soup of acronyms. CGL, E&O, BOP; it's enough to make any business owner's head spin. The key is matching the right ingredients to your specific recipe for business insurance. A management consultant needs protection against bad advice, while a plumber needs coverage for a burst pipe or accidental water damage. Bundling these into a single package often saves you money and simplifies your renewals. As your revenue grows, don't forget to review your business insurance limits to ensure your protection keeps pace with your success.
Customization is the secret to a policy that works as hard as you do. You don't want to pay for a "one-size-fits-all" plan that includes coverage for a fleet of trucks if you only use a laptop. By focusing on your specific industry risks, you can build a lean, effective policy that provides exactly what you need and nothing you don't. This precision keeps your premiums manageable while ensuring you're never left exposed.
Professional Liability (Errors & Omissions) for Consultants
Errors and Omissions (E&O) is your shield against claims of negligence or failing to deliver a promised result. If an IT consultant's code causes a major system crash, or a management advisor provides data that leads to a financial loss, E&O steps in. Standard liability covers physical slips and falls, but E&O covers the financial impact of your professional expertise. It's the safety net that keeps your business alive if a professional mistake happens.
E-commerce and Retail: Protecting the Modern Storefront
If you're selling products online or in-store, your risks are unique. Product liability is essential because it covers you if a customer gets hurt by something you sold. For 2026 digital operations, cyber liability isn't just an add-on; it's a necessity. It protects you if customer data is breached or your site is held for ransom. Don't overlook transit insurance either. It guards your inventory while it's moving from your warehouse to a customer's doorstep.
Commercial Property and Business Interruption
Commercial property coverage goes far beyond the four walls of a building. It protects your expensive tools, specialized electronics, and the inventory you've worked hard to build. If a fire or flood stops you from working, business interruption coverage provides the funds to pay your bills while you recover. For home-based entrepreneurs, understanding the average cost of home insurance Ontario is helpful, but remember that residential policies rarely cover commercial equipment or lost income. Finding the right mix doesn't have to be a solo mission. You can compare multiple coverage options to find a plan that fits your specific industry.
Evaluating Small Business Insurance Quotes: A Decision-Making Framework
Getting a single direct quote is like buying the first car you see on the lot. It's fast, but you'll never know if you could've found a better deal or more comprehensive protection elsewhere. Evaluating business insurance quotes requires a framework that looks beyond the monthly premium. You need to understand the "Broker Advantage." While a direct insurer only sells their own product, a broker searches multiple Canadian carriers to find the policy that actually fits your specific risks and budget.
Watch out for "hollow" coverage. This happens when a policy looks inexpensive but contains fine print that excludes the very risks your industry faces most often. A cheap policy is no longer a bargain if it fails to pay out when you need it. At Verdant, we simplify this comparison process for Ontario owners by stripping away the jargon and presenting clear, side by side options from the country's top carriers.
Comparing Coverage Types at a Glance
Choosing the right mix depends on your daily operations. Use this table to see how different protections serve your business:
| Coverage Type | What it Covers | Who Needs It | Typical Risk Example |
|---|---|---|---|
| CGL | Third-party injury or damage | Every Ontario business | A client slips on your wet office floor |
| E&O | Advice or service-based errors | Consultants and IT pros | A software bug causes a client's data loss |
| Property | Physical assets and inventory | Retailers and trades | Specialized tools are stolen from your van |
Maintaining a clean claims history is one of the most effective ways to lower your business insurance premiums, often resulting in savings of up to 30%.
What Drives the Cost of Your Quote?
Revenue size usually impacts your rate more than your employee count. Higher revenue suggests a higher volume of work, which naturally increases the statistical likelihood of a claim occurring over time. Your specific postal code also triggers the "Ontario Effect." Local regional risks, such as higher theft rates in certain urban centers or unique weather patterns in rural areas, influence how insurers calculate your risk level.
Don't ignore your deductible when trying to find a balance. A higher deductible will lower your monthly cost, but you must ensure you have that cash on hand if a disaster strikes. It's about finding the sweet spot where you feel secure without overpaying for protection you don't need. We help you calibrate these levels so your coverage feels like a support system, not a burden.
Steps to Secure Your Policy Online: From Quote to Coverage
Business moves fast. You need a partner that keeps up. The days of waiting weeks for a callback from a traditional broker are over. Modern digital platforms allow you to transition from curious browser to fully covered entrepreneur in a single afternoon. Securing business insurance is now a logical, transparent process that respects your time and provides immediate results.
Step 1: Your Business Profile Audit
Before you start, gather a few key details to ensure your application is accurate. You'll need your estimated annual revenue and a brief history of any previous insurance claims. Insurers also use North American Industry Classification System (NAICS) codes to categorize your risk level. Identifying your primary business activities accurately helps the system match you with the right carriers. Finally, check your current client contracts. Many larger organizations or government bodies in Ontario require specific coverage limits, such as $2 million or $5 million in liability, before you can begin work.
Step 2: Comparison and Customization
Once your profile is ready, you'll receive quotes from multiple Canadian insurance partners. This is where the broker model shines. Instead of seeing one price, you can compare different packages side by side. You might decide to add cyber liability to protect your digital storefront or crime insurance to guard against internal theft. If you're unsure about a specific clause, you can consult with a Friendly Expert at Verdant. We act as your proactive guide, ensuring the fine print actually supports your goals before you make anything official.
Step 3: Binding and Peace of Mind
The final step is binding the policy. This is the moment your coverage becomes active. After a quick digital sign-off, you'll receive your certificate of insurance instantly. This document is your golden ticket for landing bigger contracts and proving your professional reliability to stakeholders. The ease of this digital journey mirrors how simple it is to secure tenant insurance affordable Canada policies for your personal living space. Managing your policy online also means renewals and updates are just as effortless as the initial setup. If you're ready to protect your livelihood, you can start your business insurance quote today and see how simple the process can be.
Choosing Verdant: Modern Insurance for Ontario Entrepreneurs
Ontario's business landscape is changing fast. For six consecutive quarters leading up to April 2026, more businesses closed in Canada than opened. This entrepreneurial drought means every dollar counts. You need more than just a policy; you need a proactive guide who understands the unique pressures of the local market. Verdant acts as that bridge, connecting you with top Canadian carriers while stripping away the cold, bureaucratic feel of traditional banking. We believe in transparency. That means no hidden fees and no confusing fine print, just honest protection for the things you've worked hard to build.
2026 is the year to embrace a digital-first approach. The world doesn't stop for manual paperwork, and neither should your business insurance. By choosing a modern broker, you get the speed of an online platform combined with the human touch of a dedicated ally. We move at the pace of your growth, ensuring you're never held back by slow approvals or outdated processes.
Tailored Solutions for Local Industries
Ontario is a hub for tech and consulting. We've built our services to support these growing sectors with specialized coverage that actually makes sense. You won't find any dense industry jargon here. Instead, we focus on clear communication that helps you make informed decisions. If you ever need to file a claim, you won't be left to deal with a call center. We stand by your side as a dedicated ally, guiding you through the process and ensuring your interests are protected. It's about providing peace of mind through every stage of your business journey.
Ready to Protect Your Livelihood?
If you have a clean, claim-free record, you could see savings of up to 30% on your premiums. It's our way of rewarding responsible business owners who prioritize risk management. Simplification is another key part of our mission. You can manage multiple parts of your life in one place, like bundling your commercial policy with cheap car insurance Canada options. This holistic approach reduces your administrative burden and keeps your focus where it belongs, on growing your company.
Your livelihood is too important to leave to chance or outdated systems. You can get your personalized business insurance quote in minutes and join a community of Ontario entrepreneurs who value clarity and efficiency. Let's build a secure future together.
Securing Your Business Future in 2026
You've worked hard to build your brand; now it's time to ensure it stands the test of time. We've explored how the softening 2026 market offers a unique chance to strengthen your coverage while potentially lowering your overhead. By matching your specific industry risks to the right policy, you avoid the trap of overpaying for generic protection. Whether you're a consultant needing specialized professional liability or a retailer looking for property safeguards, the path to security is now faster and more transparent than ever.
Verdant is proud to be trusted by Ontario small business owners as a proactive guide. We provide instant digital quotes from top Canadian carriers so you can get back to what you do best. If you have a claim-free record, you could save up to 30% on your business insurance premiums. Don't leave your livelihood to chance when modern, affordable protection is just a few clicks away.
Get Your Personalized Business Insurance Quote Today
We're ready to help you grow with confidence and ease. Your success is our mission, and we're here to support you every step of the way. Let's make 2026 your most secure year yet.
Frequently Asked Questions
Is business insurance required by law in Ontario?
Business insurance isn't universally mandatory for every company in Ontario, but certain coverages are legal requirements. If you use a vehicle for any work purposes, you must have commercial auto insurance by law. Most businesses with employees are also required to register for WSIB. Beyond legislation, your commercial landlord or project clients will almost always require proof of liability coverage before you can sign a contract.
How much does small business insurance cost in Canada?
The cost of business insurance depends on your specific industry, annual revenue, and your location. In the first quarter of 2026, overall commercial insurance rates in Canada declined by 6%, which is good news for your budget. While prices vary, maintaining a clean claims history is the best way to secure a lower rate. We recommend getting a personalized quote to see exactly how these factors impact your premium.
Can I use my home insurance to cover my home-based business?
Standard home insurance policies usually exclude business activities, meaning your professional equipment and liability aren't protected. If a client trips in your home office or your inventory is damaged in a fire, a residential policy likely won't pay out. You need a dedicated commercial policy or a specific business endorsement to ensure your professional assets are secure without risking your personal coverage or your home's safety.
What is the difference between General Liability and Professional Liability?
Commercial General Liability covers physical accidents, such as a customer getting injured on your premises or you damaging a client's property. Professional Liability, often called Errors and Omissions, protects you against financial losses caused by your professional advice or services. If you're a consultant who provides a strategy that leads to a client's loss, Professional Liability is the specific coverage that handles that claim for your business.
Does business insurance cover cyber attacks or data breaches?
Standard business insurance doesn't always include cyber protection, but it's an essential add-on for any company handling digital data in 2026. Cyber liability covers the costs of recovering lost data, notifying affected customers, and legal fees following a breach. As digital threats become more common, this coverage ensures your reputation and your bank account stay protected if your systems are ever compromised by an outside attack.
How do I get a certificate of insurance for a new client?
Getting a certificate of insurance is a quick, digital process with a modern broker. Once your policy is active, you can download your proof of insurance instantly from your online dashboard. This document is vital for starting new projects, as it shows your clients that you have the required coverage limits in place. It's a simple way to build trust and prove your professional reliability to every new partner.
Can I save money by bundling my business and auto insurance?
Yes, bundling your commercial coverage with your auto insurance is a smart way to simplify your life and potentially lower your total costs. Many insurers offer multi-policy discounts when you manage all your protection in one place. This approach not only saves you money but also makes it much easier to track your renewal dates. It's a logical way to keep your protection organized while keeping more cash in your pocket.
What happens if I need to make a claim?
If you need to make a claim, your first step is to contact your broker immediately. We act as your dedicated ally and proactive guide throughout the entire process with the insurance carrier. We'll help you gather the right documentation and ensure the insurer has everything they need to review your case fairly. Our goal is to make the experience smooth and transparent so you can get back to work quickly.


