

Would your consulting practice survive a costly legal battle in an Ontario court over a simple professional oversight? Many professionals realize too late that their coverage doesn't actually meet the strict insurance requirements found in modern corporate contracts. When you're searching for business insurance for consultants Canada, it's easy to get lost in a sea of generic options that don't account for the specific legal and regulatory landscape of the GTA.
It's frustrating to feel like you're paying for protection you don't fully understand while worrying if a single mistake could derail your career. We agree that insurance should provide peace of mind, not more confusion. This 2026 guide is designed to clarify your options and ensure your policy stands up to the scrutiny of major Ontario clients.
You'll discover the critical differences between professional and general liability and learn which coverages are actually mandatory for your practice. We'll also walk through how to choose a Markham based broker who can navigate local market conditions with you. By the end, you'll have a clear path to securing your business and focusing on what you do best.
Key Takeaways
- Identify the crucial differences between Professional Liability (E&O) and General Liability to ensure your professional advice and physical assets are fully shielded.
- Learn how to audit your client contracts for specific insurance clauses that often dictate the coverage limits you're required to carry.
- Navigate the unique risks of the Ontario market by building a strategy for business insurance for consultants Canada that accounts for local legal costs and provincial regulations.
- Discover why niche-specific protections like Cyber Liability are now vital for IT and management consultants handling sensitive client data.
- Understand the benefits of working with a Markham based broker who can advocate for your practice and find tailored solutions from multiple partner insurers.
Understanding the Consultant Insurance Landscape in Ontario
Consulting in Ontario is more than just sharing expertise; it's about managing the liabilities that come with high-stakes advice. Many professionals view business insurance for consultants Canada as a simple checkbox required to sign a contract. In reality, it's a multi-layered protection strategy. For a consultant based in Markham or Toronto, your risk profile is shaped by specific provincial regulations and the litigious nature of the GTA corporate sector. Large firms in the York Region often require proof of specific coverage before you can even step into a boardroom. A generic, one-size-fits-all policy usually falls short because it doesn't account for the precision your niche requires.
Securing a tailored strategy for business insurance for consultants Canada ensures you meet the high standards of Ontario's major corporate players. This isn't just about avoiding risk; it's about validating your professionalism. When you work with a brokerage like Verdant Insurance, you're building a defense that respects the unique legal and economic environment of the province.
The Legal Reality for Professionals in the GTA
Ontario negligence laws are complex. If a client alleges that your advice caused them a significant financial loss, you could find yourself facing a claim in the Ontario Superior Court of Justice. The costs to defend such a case are often staggering, regardless of whether you actually made an error. Many independent contractors believe that incorporating their business provides a total shield for their personal assets. While incorporation protects you from general business debts, it doesn't necessarily protect you from personal liability for professional negligence. This is a critical distinction that many Ontario professionals overlook until they're already in a dispute.
Consultant vs. Contractor: Does the Distinction Matter for Insurance?
Insurers distinguish between those who perform manual labour and those who provide expert advice. If you're an IT consultant or a management specialist, your primary risk is "errors and omissions" rather than property damage. Standard commercial policies often exclude advice-based claims entirely. This means if your policy describes you as a general contractor but you're actually providing strategic financial consulting, you might have no coverage when you need it most.
Accurate business descriptions are vital for your business insurance. At Verdant Insurance, we help you ensure your policy documents reflect the true nature of your work. This proactive approach prevents surprises during the claims process and ensures your coverage aligns with the specific services you provide to your clients.
E&O vs. CGL: Deciphering the Two Pillars of Consultant Coverage
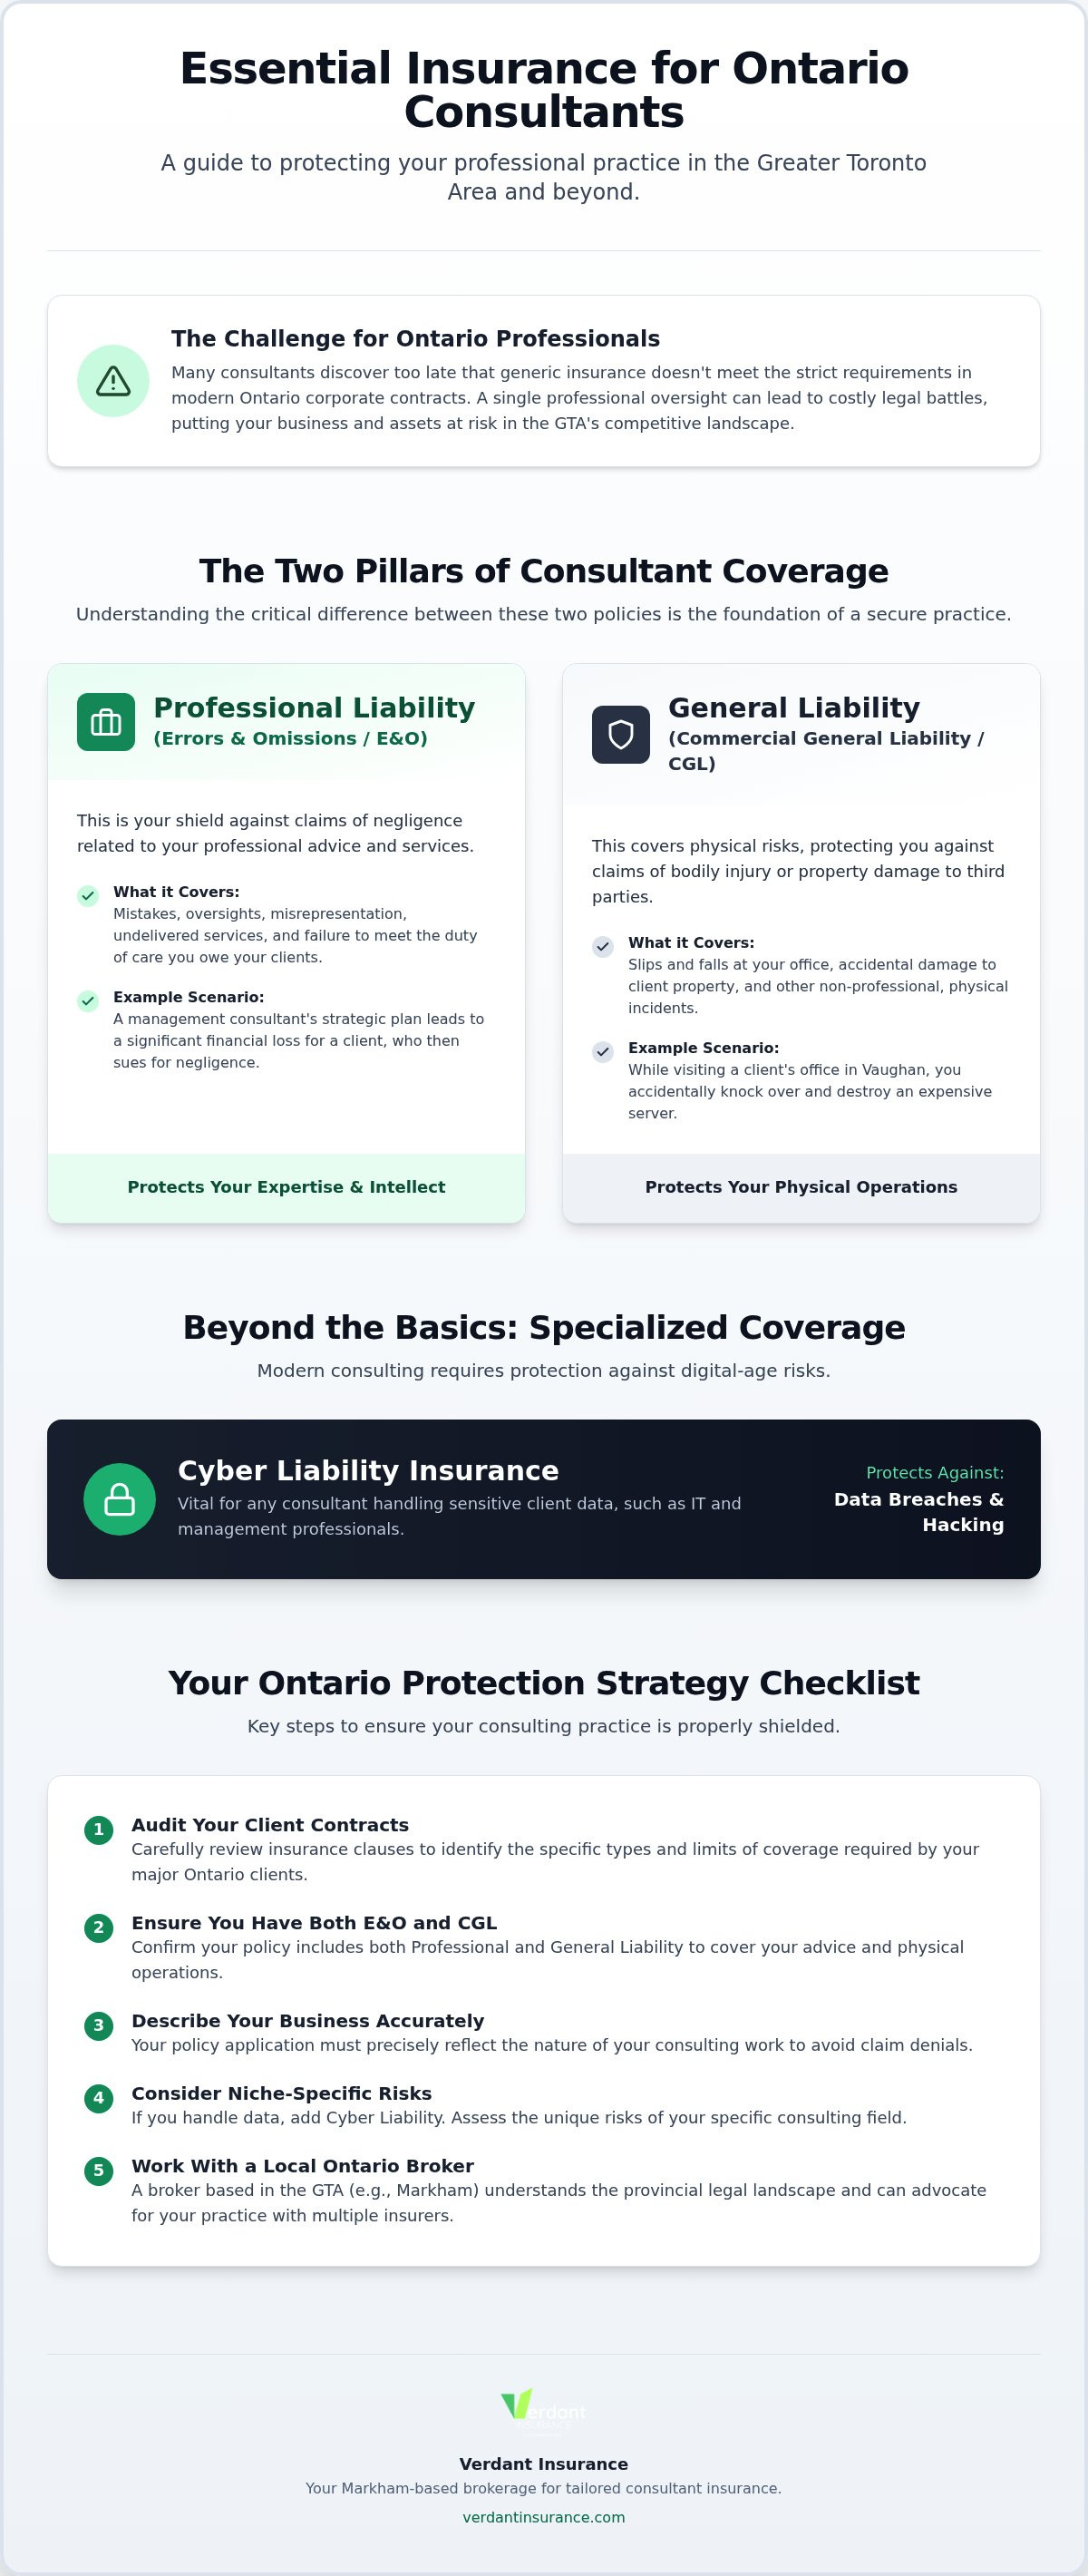
Understanding the difference between Professional Liability and Commercial General Liability is the first step toward a secure practice. While many search for business insurance for consultants Canada as a single product, it's actually a combination of these two essential pillars. Most corporate contracts in Ontario require both to ensure that every possible risk, from a bad recommendation to a physical accident, is covered. These policies work together to protect your finances and your reputation simultaneously.
Professional Liability: Protecting Your Expertise
Often called Errors and Omissions (E&O), this coverage is the primary shield for your professional advice. In the consulting world, a "professional error" isn't just a typo; it's a failure to meet the duty of care you owe your clients. If a management consultant in Markham provides a strategic plan that leads to a significant financial loss, the client might sue for negligence or misrepresentation. E&O insurance helps cover the legal defense costs and any settlements, ensuring a single mistake doesn't end your career. It's about protecting the value of your intellect and the advice you provide every day.
Commercial General Liability: Beyond the Office
While E&O covers what you say, Commercial General Liability (CGL) covers what you do. It protects you against physical risks and third-party injuries. Imagine you're visiting a client's office in Vaughan and accidentally knock over a high-end server, or a client slips on a rug during a meeting at your home office. CGL handles these third-party property damage and bodily injury claims. Even if you work primarily from home, CGL is vital because accidents can happen anywhere, from coffee shop meetings to on-site presentations. Most business insurance packages for consultants include CGL as a foundational element.
Think of these two coverages as a safety net with different weaves. If you give a client advice that causes their system to crash, that's an E&O claim. If you physically drop a client's laptop while discussing that advice, that's a CGL claim. Because these lines can blur, Ontario's major corporate clients typically mandate specific limits for both in their vendor agreements. Having both ensures you're never left vulnerable due to a technicality in policy wording. It's a proactive way to show your clients that you're a prepared and reliable professional. Choosing the right limits for business insurance for consultants Canada requires an understanding of your specific project risks and contract obligations.
Tailoring Coverage: Specialized Insurance for Different Consulting Niches
A generic policy is rarely enough for the specialized world of professional services. An IT specialist in Markham faces different hurdles than a strategy consultant in Toronto. When you're looking for business insurance for consultants Canada, you need a strategy that reflects your specific day-to-day operations. Standard policies often leave gaps that only specialized endorsements can fill. As your business grows or you pivot into new services, your coverage must evolve to match your new risk profile.
IT and Software Consultants
Tech firms often demand Technology Errors and Omissions (E&O) as a mandatory requirement. This specific coverage addresses the intersection of professional error and digital failure. If your software causes significant system downtime or a data breach for a client, the financial fallout can be devastating. Cyber Liability is now a vital component for any data-heavy role. It helps manage the high costs of data recovery and legal notifications required under Ontario privacy standards. It's a proactive way to protect your business from the evolving threats of the digital landscape.
Management and Strategy Consultants
Your advice shapes the financial future of your clients. If a strategic recommendation leads to a loss, you may be held liable for misrepresentation or inaccurate projections. Vicarious Liability is particularly important in this niche if you use subcontractors for large GTA projects. It ensures your practice is shielded even if the error was made by a third party you hired. Protecting your intellectual property and maintaining strict confidentiality are also top priorities that specialized policies can address. These protections ensure you can provide expert guidance with confidence.
HR, Marketing, and PR Consultants
These roles deal with public-facing content and sensitive personnel matters. Protection against claims of defamation, libel, or slander is essential for those in PR and Marketing. If a creative campaign accidentally infringes on a competitor's trademark, advertising liability coverage steps in. HR consultants face unique risks when providing recruitment or employment advice. Ensuring your business insurance includes coverage for these specific interactions provides the security you need to give bold, effective advice. It's about making sure your creative and professional output doesn't become a liability.
Building Your Protection Strategy: A Checklist for Ontario Professionals
Setting up a consulting practice in Ontario requires more than just expert knowledge and a laptop; it requires a defense that scales with your success. Many professionals searching for business insurance for consultants Canada often overlook the fine print in their own client agreements. Use this five-step checklist to ensure your protection strategy is airtight and meets the standards of the GTA corporate landscape.
- Audit your contracts: Look for specific indemnity clauses and insurance requirements before you begin any project.
- Determine your limits: Evaluate if a C$1 million limit is sufficient or if a C$5 million limit is required for larger Ontario corporate projects.
- Evaluate your equipment: Ensure your high-end hardware and specialized software licenses are covered under your business property policy.
- Review the retroactive date: Verify that your claims-made policy covers work performed before the current policy period to avoid gaps.
- Consult with an Ontario broker: A Markham based expert can compare options from multiple partner insurers to find the right fit for your niche.
Meeting Client Contract Requirements
Ontario corporate clients often use specific legal terms that can be confusing. You might see a request to be named as an "Additional Insured." This gives the client protection under your policy for specific risks related to your work on their project. Once your policy is in place, your broker can issue a Certificate of Insurance (COI) quickly to prove you meet these standards. Never sign a contract until you've verified that your business insurance for consultants Canada actually meets their specific demands. This prevents you from being contractually obligated to coverage you don't yet have.
Managing the Cost of Your Policy
Your premium isn't a random number; it's a reflection of your specific risk profile. Factors like your annual revenue, the industry you serve, and your past claims history all influence the final price. You can often find efficiencies and simplify your billing by bundling your home and business insurance through the same brokerage. Learn more about the average cost of business insurance to help you budget effectively for your practice. Managing these costs proactively ensures your business remains profitable while staying fully protected.
Request a tailored business insurance quote for your consulting practice
Navigating the Ontario Insurance Market with a Local Broker
Choosing where to buy your policy is just as important as what's in the policy itself. A direct insurer can only offer you their own products, which might not be a perfect fit for your specific consulting niche. As a multi-line brokerage based in Markham, Verdant Insurance provides you with choice. We work with multiple partner insurers to compare different options for business insurance for consultants Canada. This means you don't have to settle for a rigid policy that doesn't quite match your needs. Instead, you get a tailored strategy that provides genuine peace of mind.
The most significant advantage of a brokerage is advocacy. If you ever need to make a claim, you aren't dealing with a faceless corporation alone. We act as your proactive guide, helping you manage the process and ensuring your interests are protected. It's about having a friendly expert in your corner who understands the local market and the pressure you're under as a GTA professional. Our commitment is to provide straightforward, knowledgeable service that makes your life easier.
Why a Local Perspective Matters
Our team understands the business culture of the York Region, Richmond Hill, and Vaughan. We know that a contract with a major firm in Toronto often comes with strict insurance demands. Having a local broker means you have someone who can explain Ontario-specific policy nuances in plain language. We have access to a network of insurers that specialize in Canadian professional risks. This ensures your coverage is compliant with provincial laws and the expectations of high-value corporate clients.
Getting Started with Verdant Insurance
Obtaining a tailored quote is a straightforward and transparent process. To help us find the best fit, you'll want to have a few details ready. This includes your estimated annual revenue, a clear description of your consulting services, and any specific insurance clauses from your current client contracts. We focus on making business insurance for consultants Canada easy to understand, breaking down potentially intimidating information into logical segments. Our goal is to make the path forward feel effortless for you. Speak with a Verdant broker in Markham today to secure your practice with a strategy designed for the Ontario landscape.
Secure Your Professional Future in Ontario
Building a successful consulting practice requires significant dedication; protecting that hard work should be your next priority. You now have a clearer understanding of how Professional Liability and CGL work together to satisfy the strict requirements found in Ontario corporate contracts. By following a structured strategy and auditing your agreements, you ensure that your advice remains a strategic asset rather than a potential liability.
Finding the right business insurance for consultants Canada doesn't have to be a complicated or cold experience. It's about partnering with a proactive guide who understands the local landscape in Markham and the GTA. At Verdant Insurance, we take pride in offering straightforward, knowledgeable service that simplifies your life and provides true peace of mind. Our team has direct access to multiple Canadian insurance partners, allowing us to find the specific coverage that fits your professional niche and matches Ontario liability standards.
Get a Tailored Business Insurance Quote for Your Consulting Practice
Take the next step with confidence. We're ready to help you navigate the complexities of the market so you can stay focused on delivering exceptional results for your clients.
Frequently Asked Questions
Is business insurance mandatory for consultants in Ontario?
Business insurance isn't legally mandatory for most consultants under Ontario law, but it's almost always a contractual requirement for professional engagements. Major corporate clients in the GTA typically won't finalize a vendor agreement without proof of coverage. Even if it isn't legally required, operating without protection leaves your personal assets vulnerable to professional negligence claims in Ontario courts. It's best to view it as a necessary business expense for professional credibility.
How much does professional liability insurance cost for a consultant?
The cost of business insurance for consultants Canada varies significantly based on your specific industry, annual revenue, and past claims history. Insurers also consider the size of the contracts you handle and the level of risk associated with your advice. Because every consulting practice is unique, premiums are calculated individually by each insurer. A broker can help you compare options from multiple partners to find a policy that fits your budget and protection needs.
Does my Ontario home insurance cover my consulting business?
Standard Ontario home insurance policies rarely provide adequate coverage for a consulting business. Most residential policies exclude business liabilities and only offer very limited protection for office equipment. If a client slips and falls during a meeting at your home, your personal liability coverage might not apply. You'll typically need a commercial insurance policy or a specific business rider to ensure your professional activities and assets are fully protected while working from home.
What is the difference between "claims-made" and "occurrence" policies?
Most professional liability policies are "claims-made," meaning they cover incidents reported while the policy is active. In contrast, "occurrence" policies cover events that happened during the policy period, even if the claim is filed years later. For consultants, claims-made is the standard. It's vital to maintain continuous coverage because a gap could leave you unprotected for work performed in the past. This makes the "retroactive date" a crucial detail in your policy documents.
Does consultant insurance cover work done for international clients?
Many standard policies cover work done for clients in Canada and the United States, but you must verify the "territorial limits" in your wording. If you provide advice to clients in Europe or Asia, you may need a specific endorsement to extend your coverage globally. It's also important to check if the policy covers legal actions brought in foreign courts, as some insurers only defend cases filed within Canadian jurisdictions.
What happens if I hire a subcontractor for a consulting project?
If you hire subcontractors, your policy might not automatically cover their errors. You should ensure that every subcontractor carries their own business insurance for consultants Canada and names you as an additional insured. You can also add "vicarious liability" coverage to your own policy. This protects you if a client sues you for a mistake made by a third party you hired. Always verify these details with your broker before starting a collaborative project.
What is a "Retroactive Date" in a professional liability policy?
A retroactive date is the specific point in time from which your insurer agrees to cover your professional activities. Any work performed before this date won't be covered, even if a claim is filed while your current policy is active. When switching insurers, it's essential to ensure your new policy maintains your original retroactive date. This prevents "coverage gaps" for advice you provided to clients months or even years ago.
Can I get insurance if I am a new consultant with no prior claims?
You can certainly obtain insurance as a new consultant even if you don't have a prior claims history. Insurers will look at your professional background, education, and years of experience in your field rather than just the age of your new business. Providing a clear business plan and a copy of your standard client contract can help a broker find an insurer willing to offer competitive terms for your startup practice.


