

What if a small kitchen fire in your Markham apartment ended up costing you C$50,000 in damages to the building? Many renters believe their landlord's policy covers everything, but that's a risky assumption that could leave your finances vulnerable. While the Ontario rental market is shifting toward more balance in 2026, finding affordable tenant insurance ontario remains a priority for those facing a high cost of living in the GTA. The reality is that your landlord's insurance only covers the building structure, leaving your personal belongings and legal liability entirely up to you.
You likely want the security of knowing your laptop, furniture, and personal liability are protected without overspending. Securing the right coverage is about more than just checking a box on a lease; it's about securing your peace of mind. In this guide, you'll discover how to navigate the three pillars of coverage, what landlords can legally demand under the Residential Tenancies Act, and how to customize a policy for your specific lifestyle. We'll explore everything from contents protection to additional living expenses so you can rent with confidence.
Key Takeaways
- Understand why most Ontario landlords require insurance as a lease condition even though it is not mandated by provincial law.
- Identify the three essential pillars of coverage-contents, liability, and additional living expenses-that safeguard your financial future.
- Clarify the critical distinction between your landlord’s building insurance and your own personal protection to avoid costly coverage gaps.
- Discover how to secure affordable tenant insurance ontario by evaluating factors like your building type, location, and claims history.
- Learn how working with a local Markham-based broker provides access to multiple insurers and a simplified online experience.
What is Tenant Insurance and Why Do Ontario Renters Need It?
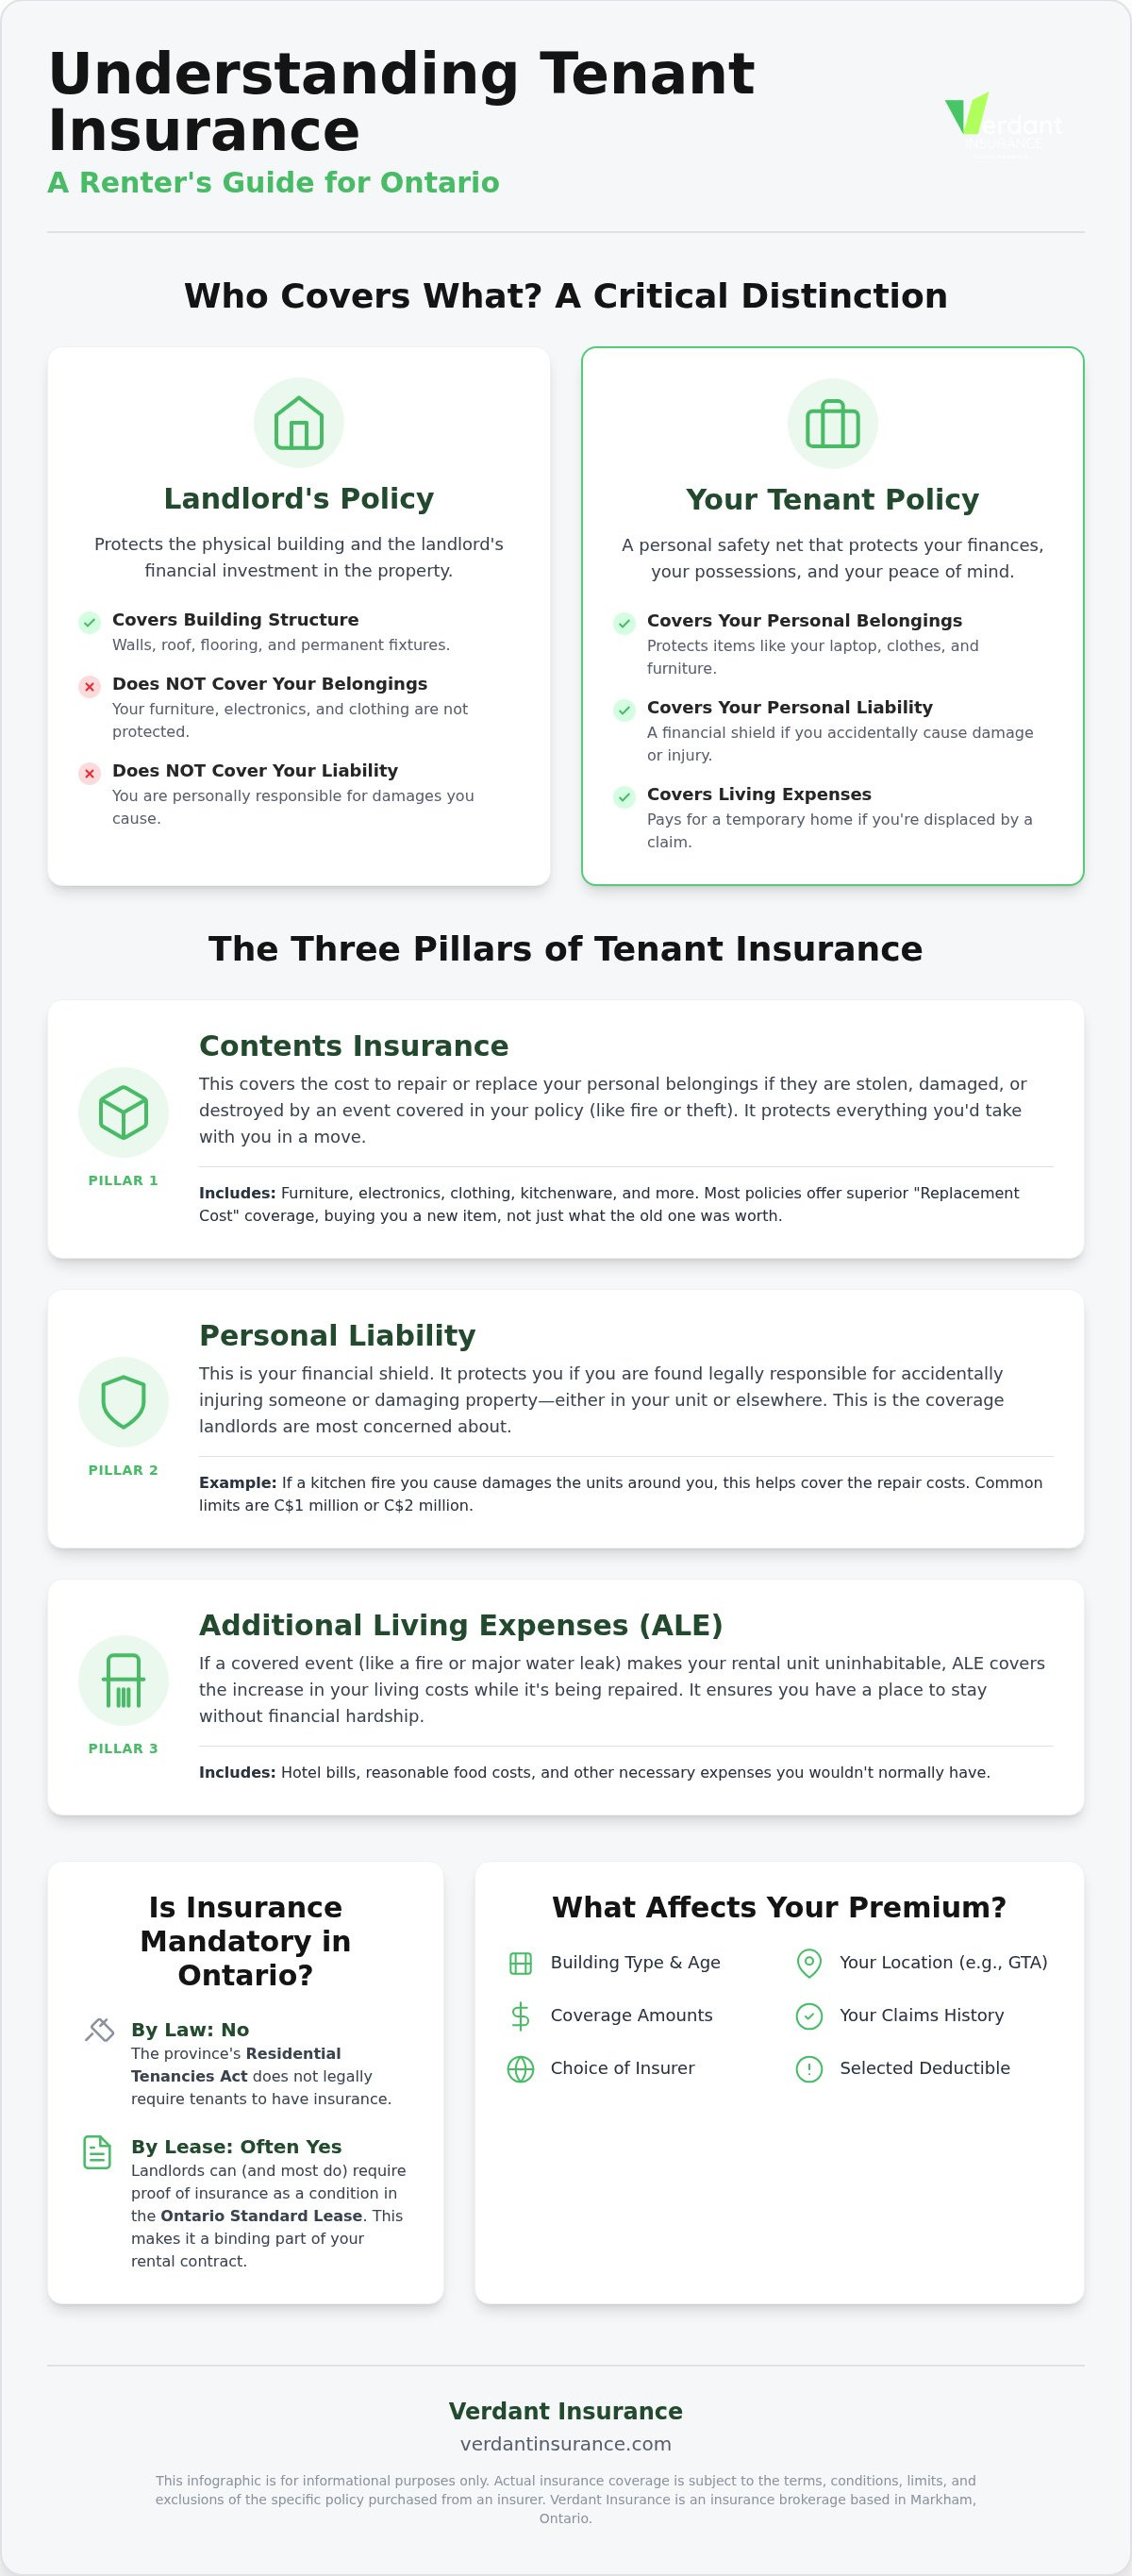
Tenant insurance is a financial safety net designed to protect you from the unexpected costs that come with renting. While your landlord has insurance for the physical building, that policy doesn't extend to your couch, your electronics, or your personal legal liability. What is renter's insurance? It's a specialized agreement that ensures a single accident doesn't wipe out your savings. At its heart, tenant insurance is a single policy that safeguards your personal belongings, provides a shield against legal liability, and covers your temporary living costs if you're displaced from your home.
Living in high-density areas like Toronto or Markham brings unique risks. A small mishap in one unit, like a kitchen fire or a burst pipe, can quickly impact dozens of other neighbors. Having tenant insurance ontario provides a layer of security that allows you to enjoy your lifestyle without the constant fear of a single accident leading to financial ruin. It’s about more than just your "stuff"; it’s about protecting your future financial stability.
Is Tenant Insurance Mandatory in Ontario?
One of the most common points of confusion for renters is whether they're legally required to have a policy. Under the Residential Tenancies Act, there's no provincial law that forces a tenant to buy insurance. However, the Ontario Landlord and Tenant Board (LTB) recognizes the Ontario Standard Lease, which is the mandatory contract for most private residential tenancies. Section 11 of this standard lease allows landlords to require proof of liability insurance as a condition of the rental agreement.
If you agree to this condition when signing your lease, it becomes a binding contractual obligation. Landlords insist on this because it ensures that if you accidentally cause damage to the building, your insurance provider handles the repairs. Proactively managing your tenant insurance ontario requirements is a standard part of the modern rental process, ensuring both you and the property owner stay protected.
The Risk of Going Uninsured
Choosing to skip coverage can be a costly mistake. If a pipe bursts or a fire breaks out, the cost of replacing your furniture and clothes is only the beginning of your worries. In the GTA rental market, where vacancy rates are tight and short-term rentals are expensive, displacement costs accumulate rapidly. Most policies include "Additional Living Expenses" to cover hotel stays and meals if you're forced out of your home.
Without this protection, you could be left paying out of pocket for a hotel while still being responsible for your rent or legal obligations. Beyond the immediate financial hit, a lack of insurance can lead to serious friction with your landlord. You could even face legal action if you're held liable for building-wide damages. The risks of going without coverage include:
- Total loss of personal belongings with no path to replacement.
- Legal responsibility for thousands of dollars in building repairs.
- Unplanned costs for temporary housing during building renovations.
Understanding Your Coverage: Contents, Liability, and Beyond
A standard policy for tenant insurance ontario isn't a one-size-fits-all product. It's a modular shield you can adjust to fit your specific life. Whether you're renting a condo in downtown Toronto or a basement suite in Markham, your policy usually rests on three essential pillars. While actual coverage is always subject to your specific insurer's policy wording and exclusions, these components are designed to handle life's little accidents with ease. By customizing your limits, you ensure you aren't paying for more than you need while staying fully protected.
Contents Insurance: More Than Just Furniture
Your contents include almost everything you'd take with you if you moved. To estimate the value, think beyond your sofa. Consider your laptop, winter wardrobe, and kitchen appliances. Most policies offer "Replacement Cost" coverage, which pays to buy a brand-new version of your item at today's prices. This is much better than "Actual Cash Value," which only pays what the used item was worth. A helpful benefit is that this coverage often follows you. If your phone is stolen while you're commuting through the GTA, your policy may still provide protection.
Liability Coverage: Your Financial Shield
This is often the part of the policy landlords care about most. Personal liability protects you if you're held legally responsible for accidentally hurting someone or damaging their property. In Ontario, carrying C$1 million or C$2 million in liability is the standard expectation. Imagine a visitor slips on a spilled drink in your apartment and suffers an injury. Without coverage, you could be personally responsible for their medical costs or legal fees. Understanding the tenant insurance requirements in Ontario helps you see why this shield is vital for your long-term security.
Additional Living Expenses (ALE)
If a pipe bursts and your apartment becomes a construction zone, where do you go? ALE is your "hotel and food" fund. It covers the extra costs of living elsewhere while your home is being repaired. This ensures you can maintain your standard of living without draining your savings on last-minute hotel stays or expensive takeout. It's a reassuring layer of support during a stressful displacement. If you have questions about how these limits apply to your specific building, you can always speak with a local broker to clarify your options.
Landlord vs. Tenant: Who is Responsible for What?
A common myth persists among many renters across the GTA. There's a widespread belief that because the landlord owns the building, their insurance policy handles every possible mishap. This misunderstanding often leads to financial heartbreak when a claim actually occurs. In reality, a very clear line exists between what the property owner protects and what you must safeguard yourself. Understanding this boundary is the first step toward true peace of mind and a smooth rental experience. The Financial Services Regulatory Authority of Ontario (FSRA) provides essential resources to help consumers understand these rights, ensuring you aren't left guessing when a crisis hits.
Think of the landlord’s policy as a shield for the "shell" of the building. It doesn't extend to the life you've built inside those walls. By recognizing where their responsibility ends and yours begins, you can avoid stressful disputes during a claim. Knowing exactly who is responsible for what empowers you to act quickly and confidently if something goes wrong.
The Landlord’s Insurance Responsibilities
The landlord is responsible for the physical structure and the common areas. This includes the roof, the hallways, the lobby, and the elevators. Their policy also covers the appliances they own, such as the refrigerator or stove provided in your lease. If a windstorm damages the roof of your Markham townhouse, the landlord’s insurer pays for the repairs. It also protects the owner against liability if someone is injured in a common area like a parking lot. However, this coverage stops at your front door. It won't pay a cent for your laptop, your designer wardrobe, or your temporary housing costs if you're displaced by a fire or flood.
The Tenant’s Insurance Responsibilities
Your responsibility starts with everything you brought into the home. When you secure tenant insurance ontario, you're protecting your personal property and your own legal liability. If you accidentally leave a bathtub overflowing and damage the apartment below, you're the one held responsible, not the landlord. Your policy steps in to handle those repair costs. It also ensures you have a place to stay if a building-wide disaster happens. While the landlord fixes the physical walls, your policy pays for your hotel and extra meals. This clear division of duties prevents legal friction and ensures both parties can recover without a total loss. By managing your tenant insurance ontario needs proactively, you maintain a professional relationship with your landlord and protect your financial future from high-cost accidents.
How to Find Affordable Tenant Insurance in Ontario
Finding the right price for your protection involves understanding how insurers view risk. While tenant insurance ontario is generally quite accessible, your specific location and building type are the primary drivers of cost. For instance, renting a modern condo in Markham or Richmond Hill often results in different premium levels compared to an older apartment in the heart of Toronto. Newer buildings often feature updated fire prevention systems and enhanced security, which can influence the likelihood of a claim. Every insurer uses its own specific formula, so your individual risk profile will always play a role in the final calculation.
One of the most effective ways to manage your costs is by reviewing your deductible. This is the amount you pay out of pocket before your coverage kicks in. If you choose to increase your deductible from C$500 to C$1,000, you will likely see a reduction in your monthly premium. Just ensure you have that amount set aside in an emergency fund so you aren't caught off guard. Additionally, staying claims-free is a major advantage. Many insurers offer significant incentives, sometimes up to 30% for those with a clean history, for maintaining long-term protection without a loss.
The "Storage Unit" Advantage
Many renters in the GTA find themselves short on space and turn to off-site storage. A common mistake is paying for the basic insurance plans offered by the storage facility itself, which can be expensive for the coverage provided. Most tenant insurance ontario policies actually extend your contents coverage to items kept in a secure, professional storage facility. This means you can protect your seasonal gear or extra furniture under your existing policy without the extra monthly fee. It's a simple way to maximize the value of your coverage. For a deeper look at how this works, you can read about Tenant Insurance for Storage Units.
Roommates and Student Housing
Sharing a home is a great way to handle the rising cost of living, but it complicates your insurance needs. You generally have two choices: share a single policy with your roommates or have everyone buy their own. While sharing a policy might seem convenient, it means your claims history is tied to theirs. If your roommate makes a claim, it could affect your future rates. Individual policies are often the cleaner choice, ensuring your personal belongings and liability remain entirely separate. You can explore the pros and cons further in our guide to Tenant Insurance for Roommates.
Get a customizable tenant insurance quote online
The Verdant Advantage: Working with an Ontario Insurance Broker
Choosing the right protection shouldn't feel like a part-time job. While many people think they have to call every insurance company in the GTA to find a fair rate, there's a much simpler way to manage your tenant insurance ontario requirements. The primary difference between a direct insurer and a broker like Verdant is choice. A direct insurer can only offer you their own specific products. In contrast, Verdant acts as your proactive guide, searching through a network of partner insurers to find the policy that fits your unique lifestyle in Markham, Richmond Hill, or Toronto.
This model turns us into your helpful ally. We aren't here to push a single brand; we're here to ensure you understand your options and feel secure in your decision. Our online platform is built for the modern renter who values efficiency but doesn't want to sacrifice the quality of their coverage. By working with a broker, you gain access to professional expertise that helps you navigate the fine print without the cold, bureaucratic feel of a traditional insurance corporation. We take pride in being a tech-forward entity that hasn't lost its human touch.
Customizable Policies for Your Life
Your life in the York Region is unique, and your insurance should reflect that. We focus on creating a transparent journey where you see exactly what you're paying for. If you've maintained a clean record, you might be eligible for significant incentives, such as a 30% savings for claims-free individuals. This is one of the many benefits of having a broker handle the legwork for you. We compare different partner insurers to find a match for your specific budget and risk profile, ensuring you don't pay for coverage you don't actually need.
Whether you're looking for basic liability to satisfy a lease or comprehensive protection for a high-value collection, we simplify the path forward. Our brokers understand the local market conditions in Vaughan and the surrounding GTA, allowing us to provide advice that is relevant to your neighborhood. We believe that by providing clarity and simplicity, we can make the process of securing insurance feel effortless rather than intimidating.
Next Steps: Get Your Ontario Tenant Quote
Ready to secure your peace of mind? Our online quote platform is designed for simplicity, allowing you to get started from your phone or laptop in just a few minutes. We've removed the friction from the process so you can get back to enjoying your home. If you have specific questions about your policy or prefer to talk through your options, our dedicated team in Markham is ready to provide the human touch you deserve. We're here to assist you every step of the way, ensuring you have a supportive partner in your corner.
Secure Your Future as an Ontario Renter
Renting in the GTA shouldn't come with constant financial worry. By now, it's clear that tenant insurance ontario is more than just a lease requirement; it's a vital shield for your savings and your lifestyle. Whether you're protecting your belongings in a Markham condo or ensuring you have a place to stay during building repairs in Richmond Hill, the right policy provides the stability you need to move forward with confidence.
Verdant Insurance makes this process effortless by connecting you with multiple top-tier Canadian insurance partners through one simple platform. If you have a clean driving and claims record, you may even qualify for savings of up to 30%, depending on insurer rules. Our team is proud to serve the Greater Toronto Area as your proactive guide, offering the expertise of a professional broker with the ease of a modern online experience.
Take the next step toward true peace of mind today. We're ready to help you find the coverage that fits your life perfectly.
Frequently Asked Questions
Is tenant insurance mandatory in Ontario by law?
No, it is not legally required by Ontario provincial law. However, most landlords in cities like Toronto and Markham include an insurance clause in the Ontario Standard Lease. If you sign a rental agreement with this requirement, it becomes a binding contractual obligation. Landlords typically insist on this to ensure you have liability coverage in case of accidental damage to the building or other units.
How much does tenant insurance typically cost in Ontario?
The cost of tenant insurance ontario depends on several individual factors rather than a flat provincial rate. Your premium is influenced by the location of your rental, the age of the building, and the total value of the belongings you wish to protect. Choosing a higher deductible or maintaining a claims-free record can also impact your final price. Since every insurer uses a different formula, it is best to get a personalized quote.
Does tenant insurance cover my roommates’ belongings?
Usually, your policy only protects the belongings of the people specifically named on the document. While some insurers allow roommates to share a policy, it often creates complications if one person moves out or makes a claim. We generally recommend that each roommate carries their own individual coverage. This ensures your personal liability and claims history remain separate and protected, avoiding potential disputes or coverage gaps in shared living situations.
What happens if I accidentally cause a flood in my apartment?
If you are held responsible for water damage to your unit or the units below you, the liability portion of your policy typically covers the repair costs. This is a critical safety net that prevents you from paying thousands of dollars out of pocket for building repairs. Additionally, if the damage makes your apartment uninhabitable, your Additional Living Expenses coverage can help pay for a hotel and extra food costs while repairs are completed.
Will my tenant insurance cover items stolen from my car?
Yes, personal items stolen from your vehicle are typically covered by your tenant policy, not your auto insurance. While your auto policy handles damage to the car itself, your renter's insurance protects the contents inside it, such as a laptop or sports equipment. This protection usually applies even when you are traveling away from home. Always check your specific policy limits to ensure high-value items are fully protected against theft.
Does tenant insurance cover a storage unit in Ontario?
Most standard policies extend coverage to your personal belongings while they are kept in a professional, off-site storage facility. This is often a more cost-effective solution than purchasing the basic insurance plans offered by storage companies. However, there are usually specific limits on the value of items stored away from your primary residence. It is important to notify your broker if you are using a storage unit to ensure your coverage limits are sufficient.
How do I choose the right deductible for my renter’s policy?
Choosing a deductible is a balance between your monthly budget and your ability to pay in an emergency. A higher deductible typically results in a lower monthly premium, which can save you money over time. However, you must be confident that you can afford the out-of-pocket cost if you ever need to make a claim. We suggest reviewing your emergency savings to find a comfortable middle ground that provides both savings and security.
Can I bundle my tenant insurance with my auto insurance at Verdant?
Yes, as a multi-line brokerage, Verdant can help you manage both your tenant and auto policies in one place. Bundling your coverage often unlocks additional savings and simplifies your insurance management through our online platform. We work with multiple partner insurers to find the best fit for your needs. Keeping your policies with one broker makes it easier to track your renewals and ensures there are no gaps in your overall protection.


