

What if the monthly cost of protecting everything you own in your Ontario rental was less than the price of a few takeout coffees? It's easy to feel like tenant insurance is just another "renter's tax" piled on top of high GTA rent. You want to satisfy your landlord's lease requirements without draining your monthly budget, yet the confusion over deductibles often feels overwhelming. Finding the cheapest apartment insurance that actually delivers when you need it shouldn't feel like a gamble. The key to securing an affordable premium in Ontario is a mix of strategic customization, selecting the right deductible, and comparing options through a local broker.
At Verdant Insurance, we know that every dollar counts when you're balancing life in Markham or Toronto. You deserve a policy that fits your lifestyle and your wallet. We promise to show you exactly how to secure affordable tenant coverage in Ontario without sacrificing the protection your belongings deserve. In this 2026 guide, we'll explore how to lower your premiums, explain what your policy covers under recent 2026 regulations, and help you find a plan that provides true peace of mind.
Key Takeaways
- Learn the three pillars of tenant coverage, including contents, liability, and additional living expenses, to ensure you meet lease requirements while protecting your belongings.
- Understand how your specific location in the GTA and your building’s construction materials directly impact the cost of your insurance premium.
- Discover how strategic choices like bundling policies or adjusting your deductible can help you find the cheapest apartment insurance without sacrificing essential protection.
- Compare the benefits of using an Ontario brokerage versus direct insurers to see which path offers the best balance of price and professional support.
- See how a streamlined online quote process combined with local expert guidance makes securing coverage in Markham and across Ontario fast and straightforward.
What is Apartment Insurance and Why Costs Vary in Ontario?
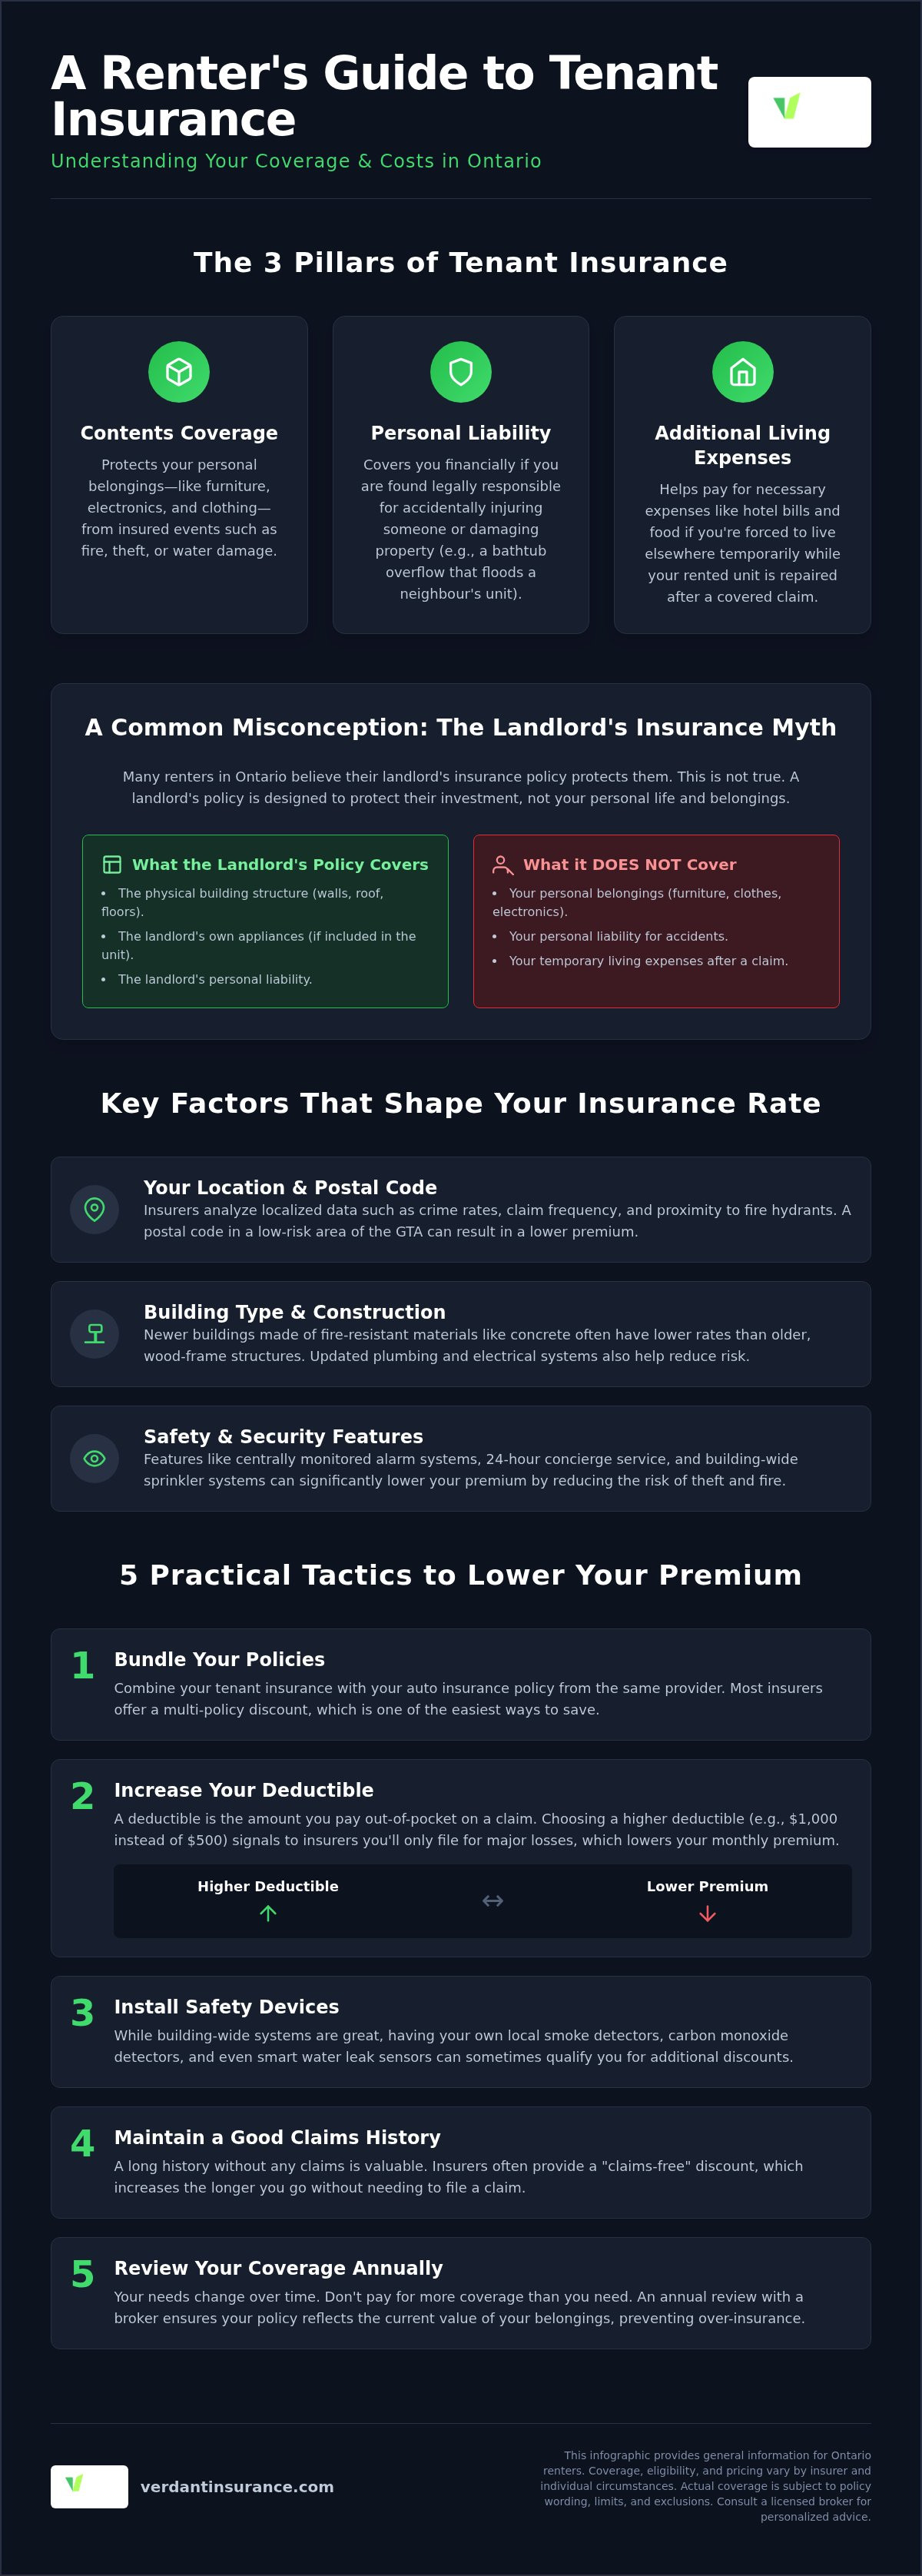
Understanding What is Apartment Insurance is the first step toward protecting your financial future. In Ontario, this coverage is often called tenant insurance. It isn't just about replacing a stolen laptop; it's a comprehensive safety net designed for anyone renting a home, condo, or apartment. While you might be searching for the cheapest apartment insurance to fit a tight budget, it's vital to know exactly what you're paying for. A standard policy stands on three specific pillars: your personal contents, your legal liability, and additional living expenses.
Ontario law doesn't technically require you to carry insurance as a renter. However, you'll find that most landlords in Markham, Vaughan, and across the GTA make it a mandatory condition of your lease. They want to see proof of insurance before handing over the keys. This requirement protects both parties. For you, the goal is finding a policy that meets these lease requirements without overspending. Even when hunting for the cheapest apartment insurance, your policy should provide enough liability coverage to protect your future earnings from potential lawsuits.
Contents vs. Liability: Where the Value Lies
Contents coverage is the part of the policy most people think of first. It protects your "stuff," such as your furniture, clothes, and expensive electronics. If a fire or a major pipe burst ruins your belongings, this coverage helps you replace them. However, liability coverage is often the most critical component of an affordable policy. It protects you if you're held legally responsible for injuring someone or damaging the building. For example, if you accidentally leave a tap running and it floods the unit below, liability coverage is what stands between you and a massive repair bill. Actual coverage is always subject to insurer eligibility, policy wording, and specific limits.
The 'Landlord Coverage' Myth
Many renters mistakenly believe their landlord's insurance covers them. This is a dangerous misconception. A landlord’s policy only protects the physical building structure and the landlord's own liability. It does not cover your personal items or your actions. If a fire breaks out, the landlord's insurance pays to fix the walls and the roof, but it won't give you a cent for your ruined bed or laptop. It also won't help if you're sued for an accident that happens inside your unit. A small monthly premium for tenant insurance prevents these massive out-of-pocket costs, giving you a level of security that the landlord's policy simply doesn't provide.
Factors That Impact Your Tenant Insurance Premium in Ontario
Securing the cheapest apartment insurance often feels like a puzzle where the pieces change depending on your address. Insurers don't just pick a number out of a hat; they analyze a variety of Factors That Impact Your Tenant Insurance Premium to determine the risk level. By understanding these variables, you can better navigate the market and find a policy that balances cost with the protection you need.
The Role of Your Neighbourhood and Postal Code
Your postal code is one of the most significant drivers of your insurance rate. For instance, a high-rise condo in downtown Toronto might carry different risks than a basement suite in Richmond Hill or a townhouse in Vaughan. Insurers use localized data to track everything from crime rates to the likelihood of water damage in specific areas. Proximity to fire hydrants and fire stations also plays a major role. If you live in a well-serviced part of Markham, your risk of a total fire loss is lower, which often leads to more favourable pricing compared to more remote areas.
Building Type and Safety Features
The physical structure of your home matters just as much as its location. Newer buildings made of fire-resistant materials like concrete and steel often qualify for better rates than older wood-frame low-rises. Safety features are another way to lower your costs. Monitored alarm systems, 24-hour concierge security, and modern sprinkler systems all reduce the chance of a major claim. If you're renting in an older Toronto building, check if the plumbing or electrical systems have been recently updated. Providing these details to your Ontario insurance broker ensures you aren't paying for risks that have already been mitigated.
Your personal history and choices also shape your premium. Staying claims-free is one of the most effective ways to keep your individual rate low over time. Additionally, your choice of deductible has a direct relationship with your monthly bill. A higher deductible means you agree to pay more out-of-pocket if a claim occurs, but it significantly reduces your ongoing premium. If you're looking for the cheapest apartment insurance, adjusting this balance is a quick way to find a price that fits your budget. If you're unsure how your building's features affect your rate, you can always speak with a broker to get personalized advice for your specific GTA neighbourhood.
Comparing Options: Aggregators vs. Direct Insurers vs. Brokers
When you start looking for the cheapest apartment insurance, you'll likely encounter three main ways to buy: aggregators, direct insurers, and brokers. Aggregators are popular because they offer a quick "snapshot" of the market. You enter your details once and see a list of prices. However, these sites often miss specialized discounts that require a human touch to uncover. They also might not account for specific Ontario regulations or the unique risks of your GTA neighbourhood, like localized flood patterns or theft rates in specific Markham postal codes.
Direct insurers are companies that sell their own products without an intermediary. While this can feel simple, you're limited to their specific underwriting rules. If that company's data suggests your Toronto low-rise is a higher risk, they'll charge you more; you'll then have to start the whole process over with another company to find a better price. You're effectively doing all the legwork yourself without any professional guidance to ensure the policy actually fits your needs.
Choosing an online insurance broker Canada renters trust, like Verdant Insurance, offers a different path. We act as your advocate, connecting you to multiple partner insurers at once. This model combines the speed of digital tools with the expertise of a local professional who knows the Ontario market inside and out. We help you find a balance between a low premium and reliable protection.
Why a Broker is Often the Path to Better Value
A broker doesn't just look for a low number; they look for the best fit. Since we work with several Ontario-licensed insurers, we can compare multiple quotes on your behalf. This saves you the time of filling out dozens of forms. We also provide personalized advice on coverage limits. You shouldn't pay for $50,000 in contents coverage if you only have $20,000 worth of belongings. We can help you identify:
- Specialized discounts for claim-free renters in the York Region.
- Specific coverage limits tailored to your actual inventory of electronics and furniture.
- Options for high-value items that standard automated quotes might exclude.
Having a local advocate in Markham or Richmond Hill also helps if you ever need to file a claim. We're here to help you understand the process and ensure you're treated fairly by the insurer.
Avoiding the Pitfalls of 'Price-Only' Shopping
If you're hunting for the cheapest apartment insurance, it's easy to overlook exclusions that leave you vulnerable. The absolute lowest quote you find online might use "Actual Cash Value" instead of "Replacement Cost." This means if your five-year-old laptop is stolen, the insurer only pays what it's worth today, not what it costs to buy a new one. A broker helps you read the fine print that automated sites often skip. We ensure your policy aligns with Consumer Protection Ontario standards and fair practices. By focusing on value rather than just the initial price, you avoid the anxiety of choosing a policy that doesn't actually protect you when it matters most.
5 Practical Tactics to Lower Your Apartment Insurance Rates
Finding the cheapest apartment insurance in Ontario doesn't mean you have to settle for a bare-bones policy. It's about being smart with your choices. Small adjustments to your coverage can lead to noticeable savings on your monthly bill. By working with an Ontario broker, you can uncover discounts that automated systems often overlook, ensuring your premium stays as low as possible while your protection remains robust.
The Power of Bundling in Ontario
One of the most effective strategies for saving money is linking your cheap car insurance Canada with your tenant policy. Most Ontario insurers offer a multi-policy discount when you keep your business in one place. This doesn't just lower your rates; it also simplifies your life by putting all your premiums on a single billing cycle. It's a convenient way to manage your household expenses while securing a better overall rate for both your vehicle and your home. Eligibility for these bundles varies by insurer, so it’s a good idea to have your broker check which partner offers the best combined value for your situation.
Optimizing Your Coverage Limits
Many renters pay for more coverage than they actually need. If you're looking for tenant insurance affordable Canada, start by performing a quick home inventory. Walk through your apartment and estimate the real value of your belongings. Don't pay for $50,000 in contents if your furniture, electronics, and clothes only total $20,000. However, be sure to mention any high-value items like jewellery or high-end bicycles. These may need specialized riders to ensure they're fully protected, but adjusting your general limits to match your lifestyle is a key part of finding the "sweet spot" for your budget.
Another powerful tactic is adjusting your deductible. Moving from a $500 to a $1,000 deductible often reduces your monthly bill because you're taking on a bit more of the initial risk yourself. You should also tell your broker about your home security. Functional smoke detectors, carbon monoxide alarms, and monitored burglar systems can qualify you for safety discounts. Don't forget to ask about "Professional" or "Claims-Free" discounts. Many insurers offer lower rates to members of certain professional associations or those who haven't filed a claim in several years. If you use a storage unit in Markham or Vaughan, your tenant policy often extends coverage to those items, meaning you might not need the extra insurance the storage facility tries to sell you. This is a great way to secure the cheapest apartment insurance without leaving your property vulnerable.
Securing Affordable Tenant Insurance with Verdant Insurance
Verdant Insurance is an Ontario-based brokerage located right in the heart of Markham. We understand that living in the GTA comes with significant costs, and we believe your insurance shouldn't be an overwhelming "tax" on your lifestyle. While you are searching for the cheapest apartment insurance to satisfy a landlord or protect your budget, our role is to make that search simple and transparent. As a brokerage, we don't work for a single insurance company; we work for you. We use our access to a wide network of partner insurers to compare options and find a policy that balances a low monthly premium with the actual protection your belongings deserve.
Our process is designed to be tech-forward but human-centred. You can start with an easy online quote to get a sense of your options, but you are never left to figure it out alone. Every quote is backed by the support of a dedicated broker who can answer questions about deductibles, liability limits, and specific policy exclusions. This combination of digital speed and professional guidance ensures you don't accidentally choose a policy that leaves you vulnerable just to save a few dollars a month.
Our Approach to Renter Security
We leverage our deep roots in the York Region to help Ontario tenants find competitive rates. Whether you are renting a high-rise condo in Vaughan, a townhouse in Richmond Hill, or a basement suite in Toronto, we understand the localized risks that insurers look at. Our brokerage model allows us to scan the market for specific discounts that automated aggregators might miss, such as those for certain professions or claim-free histories. Transparency is at the heart of every policy we broker. We take the time to explain the difference between replacement cost and actual cash value, ensuring you have total clarity before you sign your lease agreement.
Next Steps for Ontario Renters
Getting the right coverage shouldn't be a chore. To start, gather your lease details; most Ontario landlords will specify a minimum liability requirement, often $1 million or $2 million. You should also create a rough estimate of what it would cost to replace your furniture, electronics, and clothing. With this information ready, you can request a tenant insurance quote online or speak directly with a Verdant broker in Markham. We will help you customize your limits and deductibles to find the "sweet spot" where your premium is affordable and your peace of mind is secure. Protecting your future earnings and your personal items doesn't have to be expensive when you have a proactive guide on your side.
Finding a plan that fits a tight monthly budget is possible when you move away from one-size-fits-all insurance. By focusing on your specific needs and leveraging local expertise, you can meet your lease requirements quickly and move into your new home with confidence. Reach out to our team today to see how we can simplify your insurance experience.
Secure Your Ontario Rental with Confidence
Finding the cheapest apartment insurance in Ontario is about more than just the lowest price; it's about finding the right balance of protection and value. By using strategic tactics like bundling your policies or adjusting your deductible, you can secure a rate that fits your monthly budget. Whether you're moving into a new condo in Vaughan or a long-term rental in Toronto, having a local expert to guide you through the fine print makes all the difference.
Verdant Insurance offers the Ontario-based expertise and dedicated brokerage support you need to feel secure. We pride ourselves on providing customizable policies that offer real peace of mind without the cold, bureaucratic feel of traditional insurance. Our team is ready to help you navigate your options and find a solution tailored to your unique risk profile.
Your home is your sanctuary, and protecting it should be simple and stress-free. We're here to ensure you have the coverage you need so you can focus on enjoying your life in the GTA.
Frequently Asked Questions
Is tenant insurance mandatory for all apartments in Ontario?
No, tenant insurance isn't mandatory under the Ontario Residential Tenancies Act. However, it's standard practice for landlords in cities like Toronto and Markham to require proof of insurance as a condition of your lease agreement. If your lease includes this clause, you must maintain a policy to stay in compliance with your rental contract. Landlords often request a minimum of $1 million or $2 million in personal liability coverage.
Does 'cheapest' apartment insurance cover my roommate's belongings?
Typically, a policy only covers the individuals named on the document. While some insurers allow roommates to share a single policy, it's often safer for each person to have their own. Sharing a policy means a claim made by your roommate could negatively impact your own insurance history and future rates. To find the cheapest apartment insurance for your specific needs, individual policies are usually the most straightforward choice.
How much does the average tenant insurance policy cost in the GTA?
As of September 2026, the average cost for tenant insurance in Ontario is approximately $21 to $27 per month. In Toronto specifically, the average premium is about $309 per year, which is roughly 4% higher than the provincial average. Rates in municipalities like Markham or Ajax may be slightly lower. Your actual premium will vary based on your specific building, contents value, and chosen deductible.
Does my apartment insurance cover items kept in a storage unit?
Yes, most standard tenant policies in Ontario extend coverage to personal property kept in a storage unit. This is a great way to avoid the expensive insurance plans often sold by storage facilities. However, coverage for items off-premises is usually limited to a percentage of your total contents limit, such as 10%. It's a good idea to check your specific policy wording to ensure your off-site belongings are fully protected.
Can I get a discount if I have a smoke-free or alarm-equipped apartment?
You can often secure discounts for having safety features like monitored burglar alarms, fire sprinklers, or smoke detectors. Many Ontario insurers also offer lower rates for smoke-free buildings because they represent a lower fire risk. When you're looking for the cheapest apartment insurance, always mention these features to your broker. These small details can lead to meaningful reductions in your monthly premium while improving your home's safety.
What happens if I don't have insurance and there is a fire in my building?
If a fire occurs and you don't have insurance, you'll be responsible for replacing all your personal belongings out of pocket. The landlord's insurance only covers the building structure, not your furniture or electronics. Additionally, you'd have no coverage for "Additional Living Expenses," meaning you'd have to pay for your own hotel and food if your unit becomes uninhabitable. You also face massive financial risk if you are found liable for the fire.
Is it cheaper to pay my tenant insurance premium monthly or annually?
Paying your premium annually is typically cheaper than paying monthly. Most insurance companies in Ontario charge a small administrative fee or interest for processing monthly installments. By paying the full year upfront, you avoid these extra costs and ensure your coverage stays active without the risk of a missed payment. If your budget allows for it, the annual option is the most cost-effective way to manage your policy.
How do I switch to a cheaper insurance provider without a lapse in coverage?
To switch providers without a lapse, you should first secure and bind your new policy with an effective date that matches your current policy's expiry. Once your new coverage is confirmed, you can notify your current insurer to cancel your old plan. Working with a brokerage like Verdant Insurance simplifies this process. We can help you compare options and handle the transition to ensure you're never left without protection during the move.


