

Your landlord just handed you a lease for a new place in Markham or downtown Toronto, and there's a clause requiring proof of tenant insurance before you can even pick up the keys. It feels like just another hurdle in an already expensive rental market. While many people search for the best renters insurance Canada has to offer, the reality is that the right policy depends entirely on your specific lifestyle and the value of the items you're moving.
You've probably wondered if your landlord's policy covers your electronics or if you're paying for protection you don't actually need. It's a common worry, but the truth is that a landlord's insurance only protects the building, not your personal possessions or your personal liability. This guide will help you evaluate different coverage options, understand Ontario legal requirements, and show you how a professional broker can simplify the comparison process. We'll break down everything from liability limits to protecting your most prized belongings, ensuring you feel confident and secure in your Ontario rental.
Key Takeaways
- Understand the three essential pillars of tenant insurance, which protect your personal belongings, liability, and additional living expenses if you're displaced.
- Learn how your specific GTA neighborhood and your building's safety features, such as fire alarms and security systems, influence your monthly premiums.
- Discover the advantages of using an Ontario broker to compare multiple partner insurers rather than being limited to a single direct insurer's rules.
- Identify how to choose the best renters insurance Canada residents rely on to satisfy landlord requirements while securing professional broker advocacy.
- Find out how claim-free tenants in Ontario can access significant savings by bundling their tenant policy with their auto insurance.
What is Renters Insurance and Why is it Essential in Ontario?
Renters insurance is a financial safety net designed for anyone leasing a house, apartment, or condo. In Ontario, you'll often hear this referred to as tenant insurance or apartment insurance. At its core, it's a contract that protects your personal belongings, provides liability coverage, and helps with relocation costs if your home becomes uninhabitable due to a covered event. While many people search for the best renters insurance Canada has to offer, the most important factor is finding a policy that fits your specific Ontario living situation and satisfies your landlord's requirements.
It's a common misconception that insurance is legally required for tenants in Ontario. Unlike auto insurance, the provincial government doesn't mandate it. However, the reality on the ground is quite different. Most landlords in cities like Markham and Toronto won't hand over the keys without proof of a valid policy. It's a standard business requirement used to protect both the tenant and the property owner from unexpected financial loss.
Tenant Insurance vs. Landlord Insurance
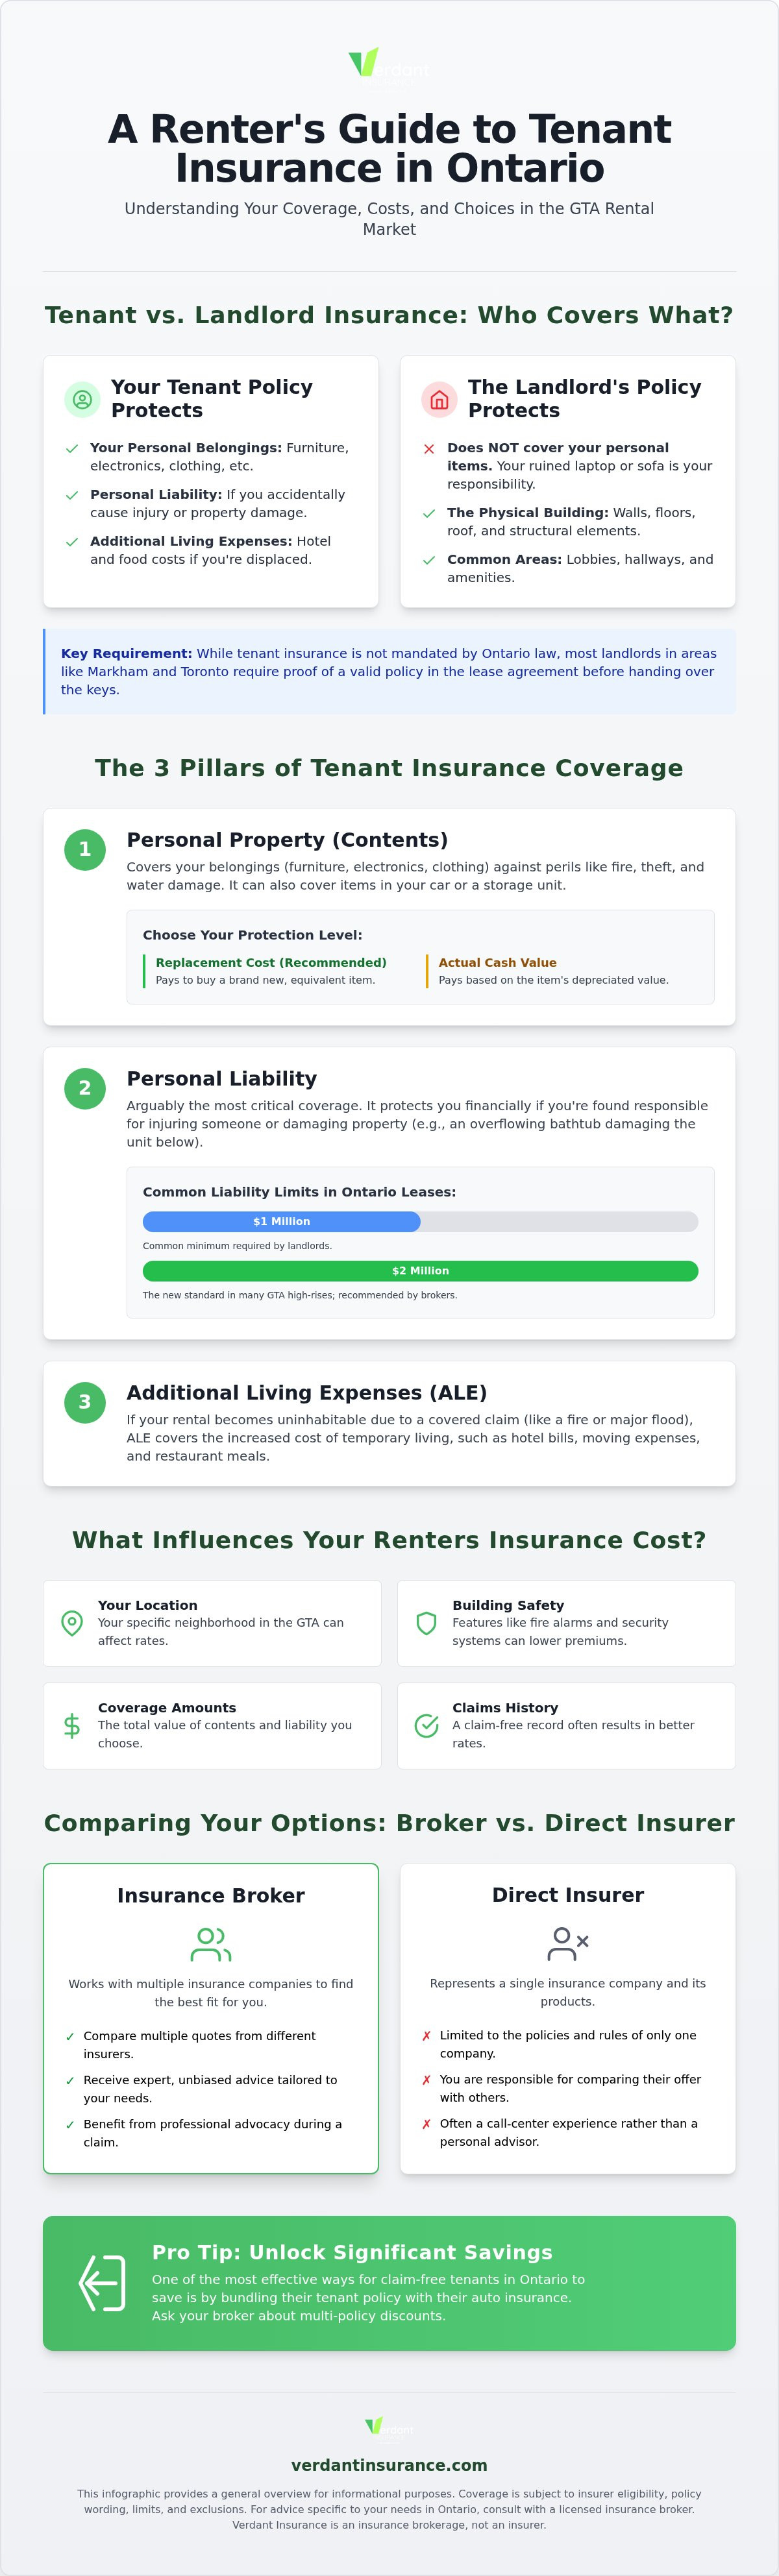
Many tenants assume their landlord's policy covers them. This is never the case. A landlord's insurance protects the physical building structure, the roof, and the common areas. It doesn't cover your laptop, your furniture, or your clothing. If a pipe bursts in your Richmond Hill apartment, the landlord's insurer pays to fix the floor and the walls. You're responsible for your ruined electronics and water-damaged sofa. Without your own tenant policy, you'd have to pay out of pocket to replace everything you own after a fire or major leak.
Meeting Your Lease Requirements in the GTA
The Ontario Standard Lease usually includes a section where the landlord specifies their insurance requirements. In the GTA, it's typical for landlords to request a minimum of $1 million in personal liability coverage; however, $2 million is becoming the new standard in many high-rise buildings. This protects you if you accidentally cause damage to the building, such as a kitchen fire or an overflowing bathtub that leaks into the unit below. Working with an insurance broker makes this process simple. We help you interpret these lease clauses and ensure your policy meets every requirement so your move-in day is stress-free.
Core Coverage: What Your Policy Actually Protects
A standard policy isn't just a piece of paper for your landlord; it's a bundle of four distinct protections. When searching for the best renters insurance Canada residents can find, you'll see that policies are generally built on the same foundation. These pillars include protection for your stuff, your legal liability, your living costs during an emergency, and minor medical bills for guests.
Understanding Contents Coverage Limits
Your personal property coverage covers items like your clothing, furniture, and electronics from "perils" such as fire, theft, and smoke damage. You'll need to choose between Actual Cash Value, which pays based on depreciated value, and Replacement Cost, which pays for a brand new equivalent item. Most modern Ontario policies default to replacement cost because it provides much better security. If you have a high-end bicycle or expensive jewellery, insurers often set "special limits" on these categories. You can learn more about how to find tenant insurance in Ontario that specifically accounts for these high-value items. Most policies also extend this protection to items kept in a storage unit or even inside your car.
The Importance of Personal Liability
Liability is arguably the most critical part of your policy. It protects your financial future if you're found responsible for injuring someone or damaging their property. A common example in the GTA involves a bathtub overflowing in a Richmond Hill condo and causing water damage to three floors below. Without liability coverage, those repair costs could follow you for years. Most Ontario landlords now require a minimum of $1 million in liability, but many brokers recommend $2 million to account for the rising costs of legal settlements and property repairs. If you're unsure about your requirements, you can speak with a broker about tenant insurance to review your lease terms.
Additional Living Expenses (ALE) in High-Density Areas
If a fire or building-wide flood in a Toronto high-rise makes your unit uninhabitable, ALE pays for your hotel stays, moving costs, and even the increase in your grocery bill. This coverage is essential in high-density areas where a single incident can displace hundreds of residents. It also kicks in during mass evacuations or if a government authority denies access to your building. While you wait for repairs, ALE ensures you aren't stuck with a massive credit card bill for temporary housing.
Finally, your policy includes voluntary medical payments. This covers minor injuries to guests, like a trip over a rug, without requiring a lawsuit. It's a small but helpful way to handle minor accidents quickly and maintain good relationships with your friends and neighbours.
Comparing Options: Insurance Brokers vs. Direct Insurers
When you start your search for the best renters insurance Canada provides, you'll quickly realize there are two main ways to buy a policy. You can go through a direct insurer or work with an insurance broker. A direct insurer is a single company that sells its own branded products. They set their own rules and underwriting requirements. This model is often highly automated, which appeals to those looking for a quick transaction, but it limits your choices to whatever that specific company offers.
An insurance broker operates differently. As independent experts, brokers represent multiple partner insurers. Instead of trying to fit you into one specific product, they compare several options to find the coverage that matches your Markham or Toronto lifestyle. Brokers are regulated by the Financial Services Regulatory Authority of Ontario, ensuring they act in your best interest. This independence is a major advantage because the broker doesn't work for the insurance company; they work for you.
The Benefits of Using an Ontario Broker
Working with a local expert means you get more than just a price. A broker understands the nuances of the GTA rental market, from the specific risks of high-rise condos in North York to the requirements of basement apartments in Vaughan. You get access to multiple quotes through a single point of contact, saving you the time of filling out five different forms. Beyond the initial purchase, a broker acts as your advocate. If you ever need to file a complex claim, you have a human being to call who can guide you through the process and help ensure the insurer treats you fairly.
Direct-to-Consumer Digital Platforms
Many tenants are drawn to mobile-only platforms because of the promise of "instant" quotes. While these digital tools are convenient for simple tasks, they can fall short when life gets complicated. If you're dealing with a stressful water damage claim or a liability dispute, a chatbot often can't provide the reassurance or nuanced advice you need. A hybrid approach is often the most effective solution for Ontario residents. You can enjoy the convenience of modern digital tools while still having the security of professional broker support. If you're ready to see how these options compare for your specific situation, you can speak with an Ontario broker to get personalized advice.
What Influences the Cost of Renters Insurance in Ontario?
Finding the best renters insurance Canada provides means understanding that prices aren't one-size-fits-all. In Ontario, insurers look at a variety of factors to determine your premium. These range from the physical location of your rental to your personal history as a policyholder. While the search for the best renters insurance Canada residents can buy often starts with price, it's the specific details of your GTA living situation that ultimately set the rate.
Location and Risk Factors in the GTA
Your address is one of the biggest drivers of your rate. Insurers look at how close your rental is to a fire hydrant and a responding fire station. In a high-density area like downtown Toronto, fire response times might be excellent, but crime rates or localized flood risks could be higher than in a quieter pocket of Markham. Richmond Hill and Vaughan often see different rates because their environmental risks, such as the likelihood of sewer backup during a heavy storm, vary based on local infrastructure. Postal codes are more than just a mailing address; they're a map of risk data for insurance companies.
Building characteristics play a huge role too. A modern condo with a 24/7 concierge, monitored fire sprinklers, and a gated parking garage is generally seen as a lower risk than an older walk-up without these security systems. These features don't just provide peace of mind. They often result in lower premiums because they reduce the chance of a successful theft or a catastrophic fire. When you're comparing quotes, a broker can help you identify which building features might qualify you for specific credits.
How to Secure Affordable Tenant Insurance
One of the most effective ways to lower your costs is through bundling. Many Ontario insurers offer a multi-policy discount if you combine your tenant coverage with your auto insurance. This is a simple way to streamline your bills while keeping your protection intact. It also simplifies your life by having one point of contact for both your car and your home.
You can also influence your premium by adjusting your deductible. The deductible is the amount you pay out of pocket before your insurance kicks in. By choosing a higher deductible, you take on a bit more of the initial risk, which usually results in a lower monthly payment. Your history matters as well. Staying claim-free is one of the best ways to keep your rates stable over time. Insurers value tenants who show a history of responsible home management and offer better rates to those with a clean record.
Compare Ontario tenant insurance quotes with a Markham broker
Securing Your Policy with Verdant Insurance
Choosing a policy shouldn't feel like a second job. While you've likely spent time searching for the best renters insurance Canada has to offer, the most effective solution is often found right in your own backyard. At Verdant Insurance, we combine the speed of modern digital tools with the deep, localized expertise of our Markham-based team. We don't just provide a single quote; we act as your personal advocate by comparing multiple partner insurers to find the specific coverage that aligns with your lifestyle and budget.
Our goal is to make the insurance process as transparent and effortless as possible for Ontario tenants. We know that whether you're moving into a new condo in Vaughan or renewing a lease in downtown Toronto, you need a partner who understands the unique risks of the GTA. By working with a brokerage rather than a direct insurer, you gain access to a wider variety of options and a human expert who is ready to explain the fine print without the confusing industry jargon.
Getting started is straightforward. We've designed a simple 5-step process to help you secure your Ontario tenant quote online:
- Provide your address: Enter your specific Ontario rental location so we can assess local risk factors.
- Describe your building: Tell us about your home's safety features, such as sprinklers or a monitored alarm system.
- Estimate your contents: Calculate the total value of your electronics, furniture, and clothing.
- Review your options: Our brokers present you with vetted choices from our partner insurers.
- Finalize and bind: Select your preferred policy and receive your digital proof of insurance immediately.
The Verdant Experience: From Quote to Claim
We've built our service model around the needs of busy Ontario professionals. Our online interface allows you to manage your details on your own schedule, while our dedicated brokers provide the human support that digital-only platforms lack. If you ever need to file a claim, you won't be dealing with a faceless corporation. You'll speak with a professional who lives and works in your community, ensuring you receive supportive guidance when you need it most. We take pride in offering clear, honest explanations of policy wording so you always know exactly what is protected.
Next Steps for Ontario Renters
Before you reach out, take a few minutes to gather your rental details. Having your building type, approximate contents value, and your landlord's specific liability requirements on hand will speed up the process. You can then contact a Verdant broker to discuss tenant insurance affordable Canada residents can rely on for long-term security. Once you've finalized your coverage, we'll provide the formal proof of insurance your landlord requires, allowing you to focus on your move with complete peace of mind.
Protecting Your Ontario Home and Financial Future
Finding the right coverage doesn't have to be a stressful part of your move. By choosing a policy that balances contents protection with robust liability limits, you're securing your belongings and your long-term financial stability. Working with a Markham-based broker gives you a local advantage. You gain access to top-tier Canadian insurance partners and expert advice tailored specifically to the GTA market.
While you might start your search for the best renters insurance Canada offers, the real value lies in a personalized Ontario policy that satisfies your landlord and protects your unique lifestyle. Claim-free tenants can often access savings of up to 30% when bundling their tenant and auto insurance through our brokerage. We're here to make the process simple, transparent, and supportive.
You deserve to feel confident and secure in your rental home. Let our team of experts help you find the peace of mind you need for the years ahead.
Frequently Asked Questions
Is tenant insurance mandatory in Ontario?
Tenant insurance is not legally mandatory under Ontario provincial law, but it's a standard requirement in most lease agreements. Landlords in the GTA often insist on proof of insurance before handing over the keys. This requirement protects both parties from the high costs of property damage or legal liability. If your lease specifies you must have coverage, failing to maintain a policy could lead to a breach of your rental contract.
How much does the best renters insurance in Canada typically cost?
The cost of what many consider the best renters insurance Canada provides varies significantly based on your specific location and the value of your belongings. Factors like your postal code in Markham or Richmond Hill, the age of your building, and your chosen deductible all influence the final premium. Because every insurer uses a different formula, working with a broker is the most effective way to compare rates across multiple partner companies for your unique situation.
Does my roommates' insurance cover my belongings too?
Your roommate's policy usually only protects their own personal possessions and liability. In Ontario, insurance companies typically require each adult occupant to have their own separate policy unless they are a spouse or a direct family member. If you're sharing a condo in Toronto, it's important for each person to secure their own coverage to ensure their electronics, furniture, and legal liability are fully protected in the event of an unexpected claim.
What happens if I don't have renters insurance and there is a fire?
Without a policy, you'll be personally responsible for replacing all your belongings and covering your own temporary housing costs after a fire. Perhaps more importantly, you'll be legally liable for any damage caused to the building or other units if the fire started in your apartment. These costs can easily reach hundreds of thousands of dollars, making a tenant policy a critical safeguard for your financial future in the GTA and beyond.
Does tenant insurance cover my bike if it's stolen outside my apartment?
Most tenant insurance policies in Ontario provide coverage for your personal property even when it's temporarily away from your home. This means if your bicycle is stolen from a rack in downtown Toronto or from your car in Markham, it's typically covered up to the limits specified in your policy. You should check your specific policy wording for any sub-limits or exclusions that might apply to high-value sporting equipment or specialized professional bicycles.
Can I get a discount if I bundle my car and tenant insurance?
You can definitely access significant savings by bundling your tenant and auto insurance policies. At Verdant Insurance, we help claim-free and conviction-free clients save up to 30% on their premiums through these multi-line discounts. Bundling is one of the most effective strategies for Ontario residents to lower their total insurance costs while simplifying their monthly billing through a single, reliable brokerage that understands the local market and your specific coverage needs.
What information do I need to provide for a tenant insurance quote?
To get an accurate quote, you'll need to provide your full rental address, the type of building you live in, and an estimate of your contents' total value. Insurers also ask about the age of the building, the proximity to fire hydrants, and whether you have monitored security or fire alarms. Providing your previous claims history is also essential, as staying claim-free is a major factor in securing more competitive rates from our partner insurers.
Does renters insurance cover damage I accidentally cause to the building?
Yes, the personal liability portion of your policy is designed to cover accidental damage you cause to the rental property. Common examples include a kitchen fire or an overflowing sink that damages the floors or the unit below yours. In high-density areas like North York or Markham, these accidents can lead to expensive repair bills. Having a policy ensures your insurer handles the costs, subject to your policy limits, eligibility, and specific exclusions.


