

Did you know that less than 50% of Canadian renters carry insurance, even though the renter insurance Canada cost is often much lower than people expect? It's a surprising gap in protection, especially when you consider that there were over 120,000 reported burglaries across the country recently. We understand why you might be hesitant. With rental prices in provinces like Ontario climbing by 27% since 2016, your budget is likely already stretched thin. You don't want to pay for coverage you don't need, and 2026 inflation has many people worried about the rising cost of replacing their personal belongings.
We're here to help you find clarity and peace of mind. Our goal is to show you exactly what influences your premium so you can secure comprehensive protection without overpaying. It's about finding that perfect balance between safety and savings. In this guide, we'll provide a clear breakdown of monthly price estimates across the country, explain the factors that landlords actually require, and give you a proven checklist of ways to lower your costs by up to 30%. Whether you're in a downtown high-rise or a suburban basement suite, we'll make sure you have the tools to protect your space with confidence.
Key Takeaways
- Learn how your policy functions as a tripartite protection plan, ensuring you aren't paying for coverage that doesn't fit your lifestyle.
- Compare your premiums against updated 2026 provincial averages to see how the renter insurance Canada cost varies from coast to coast.
- Identify the five primary factors that influence your monthly rate, including the "hidden" impact of your personal insurance history.
- Follow a practical roadmap to secure significant savings of up to 30% without sacrificing the quality of your protection.
- Discover how a proactive broker can act as your helpful ally, handling the shopping process to find your ideal balance of price and care.
Understanding Renter Insurance Costs in Canada for 2026
Many tenants view insurance as just another monthly bill to manage. However, the renter insurance Canada cost is more than just a flat fee; it's a reflection of a tripartite protection plan designed to shield you from three distinct types of financial risk. When you pay your premium, you're actually contributing to three different "risk pools" that cover your belongings, your legal liability, and your living security. Understanding this structure is the first step toward ensuring you aren't paying for more than you need.
It's a common mistake to assume that a landlord's insurance policy has your back. While their policy protects the physical structure of the building, it offers zero protection for your furniture, electronics, or personal liability. If a pipe bursts and ruins your laptop, the landlord's insurance covers the pipe, but you're responsible for the computer. This is where Renter's insurance steps in to fill the gap. In 2026, we're also seeing a significant shift in how these costs are calculated due to remote work. With more Canadians working from home, the value of equipment kept inside apartments has spiked, making accurate contents coverage more important than ever before.
The Three Pillars of Your Premium
Your total monthly rate is built on three specific foundations. Each one addresses a different "what if" scenario that could otherwise derail your finances:
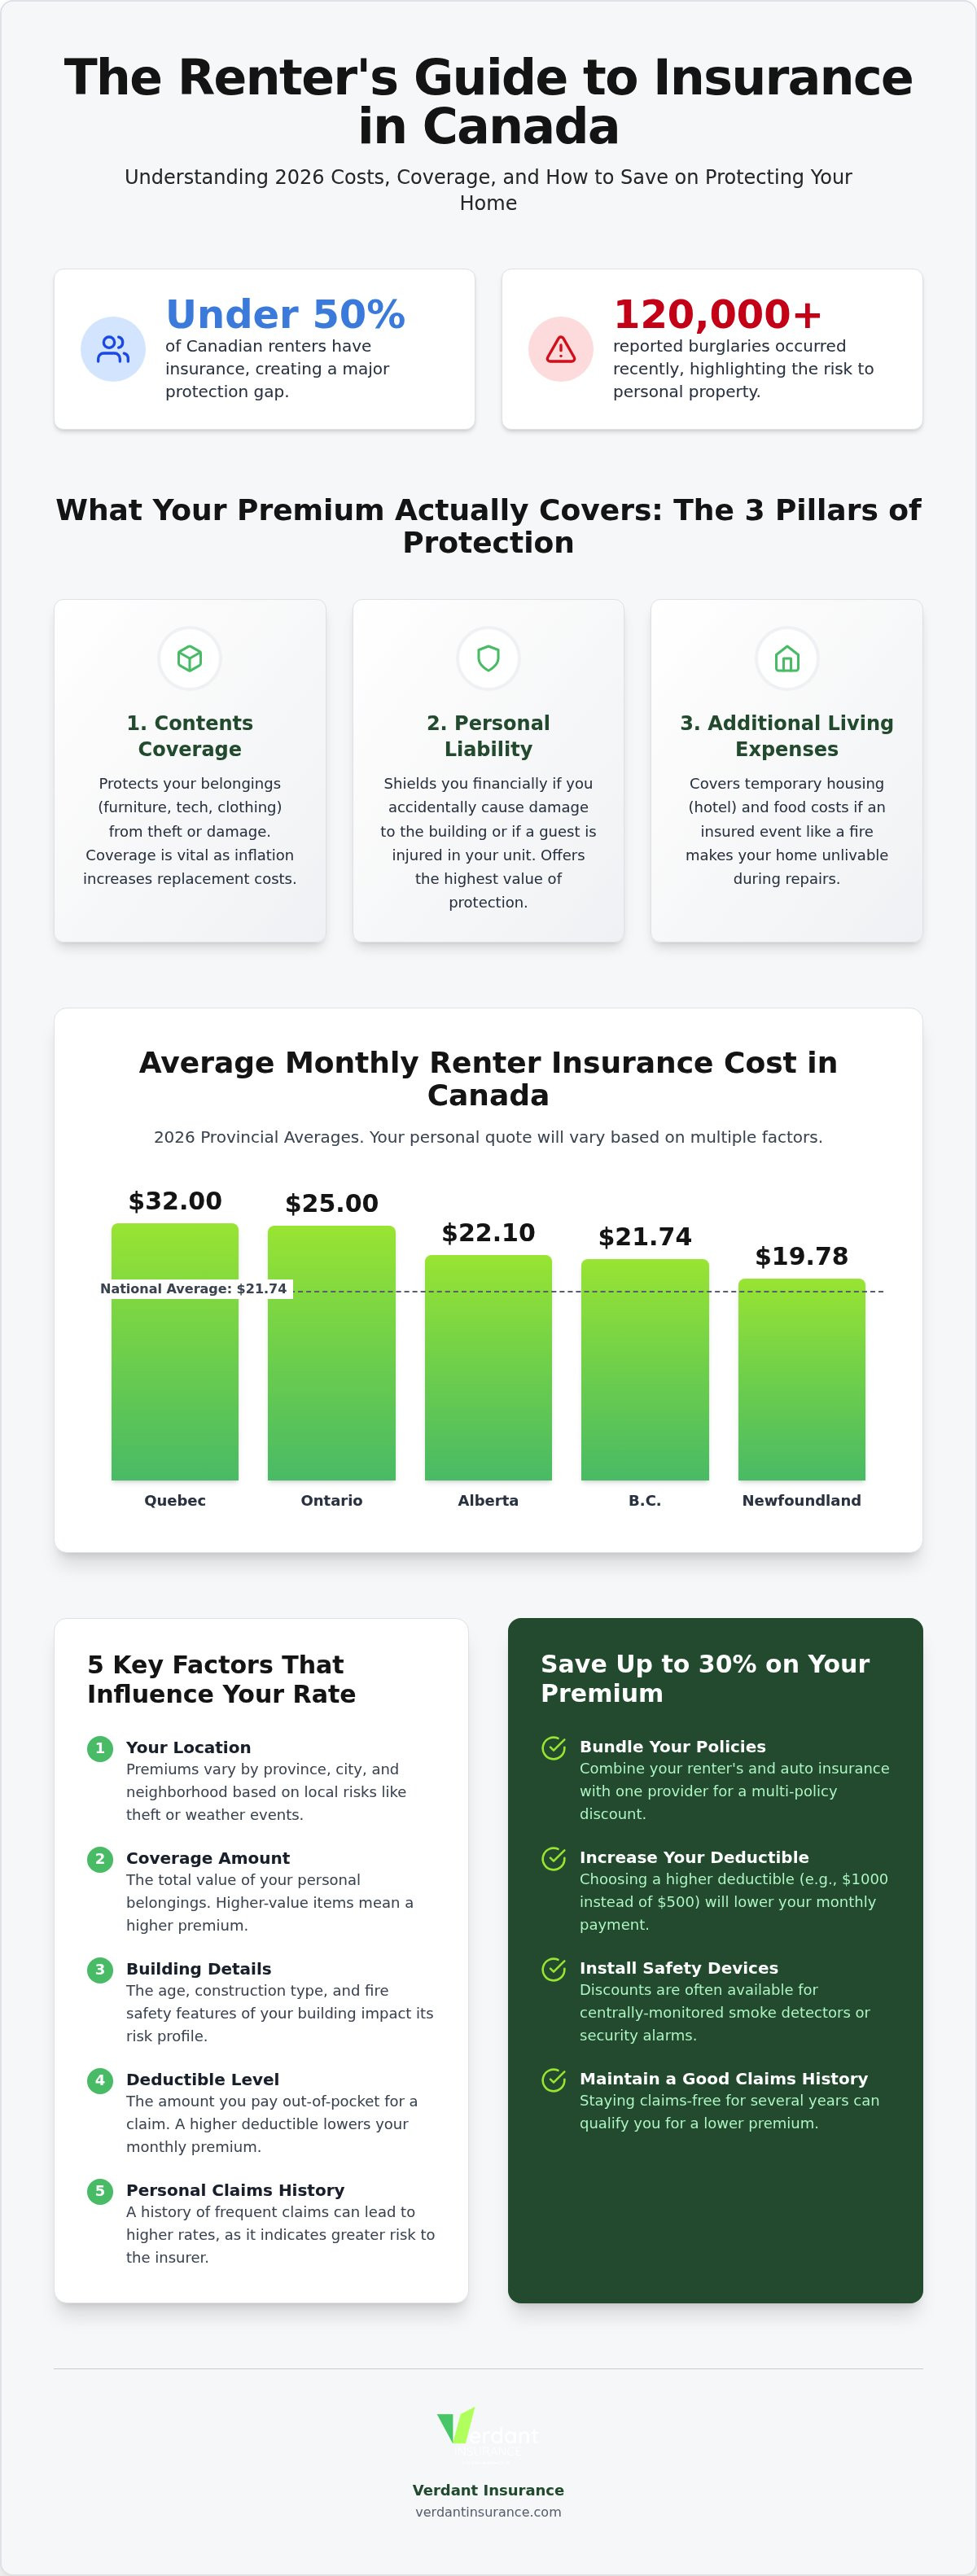
- Contents Coverage: This protects your tech, furniture, and clothing. With 2026 inflation affecting replacement costs, it's vital to have enough coverage to buy new items at today's prices rather than what you originally paid.
- Personal Liability: This shields you if you're held responsible for accidental damage to the building or if a guest is injured in your home. It's often the most overlooked part of the renter insurance Canada cost, yet it provides the highest dollar value of protection.
- Additional Living Expenses (ALE): If a fire or flood makes your unit unlivable, ALE covers the cost of a hotel and extra food expenses while repairs are underway.
Is Tenant Insurance Mandatory in Canada?
Technically, no Canadian law forces you to buy tenant insurance. You won't be fined by the government for skipping it. However, the reality on the ground is quite different. The vast majority of landlords now include a mandatory insurance clause in their lease agreements. In Ontario, for instance, most landlords require proof of insurance before they'll even hand over the keys. They do this to protect themselves from liability claims and to ensure their tenants aren't left homeless after a disaster. In a high-cost rental market where prices have jumped 27% since 2016, the financial risk of going uninsured is simply too high for most people to ignore.
Average Monthly Premiums: What Renters Pay Across Canada
While the national average renter insurance Canada cost sits at approximately $21.74 per month, this figure only tells part of the story. The Canadian insurance landscape in 2026 is a patchwork of regional variables, where your specific province and city can shift your premium by several dollars. Urbanization remains the primary driver of these differences. As more people move into dense city centres, the collective risk of theft or accidental damage increases, which naturally influences the local "price of admission" for protection.
It's helpful to remember that an average is just a starting point. Your personal quote will be a custom reflection of your building's age, your proximity to a fire hydrant, and even the specific floor you live on. Seeing how your neighbours are faring across the country can help you determine if your current quote is a fair deal or if there's room to save. A quick online comparison can show you how your specific postal code stacks up against these national benchmarks.
2026 Cost Breakdown by Province
Ontario currently sits in the middle of the pack with an average premium of $25 per month. This is largely due to the high volume of renters in Toronto and Ottawa balancing out lower rates in more rural areas. In Western Canada, British Columbia ($21.74) and Alberta ($22.10) maintain relatively stable rates, though regional weather risks like hail or flash flooding can cause minor fluctuations. Interestingly, Newfoundland offers the most accessible entry point in the country at just $19.78 per month. Quebec presents a different profile; with an average of $32 per month, rates reflect a market where higher standard deductibles are common to offset the rising cost of property claims in Montreal and Quebec City.
City Spotlight: Toronto vs. Smaller Ontario Hubs
In Ontario, your specific postal code is one of the most powerful factors in your quote. Downtown Toronto averages around $26 per month, while hubs like London or Windsor often see lower rates. However, the type of home you choose matters just as much as the city. Many renters are surprised to learn that a downtown high-rise is often cheaper to insure than a suburban basement suite or a wood-frame low-rise. This is because modern towers are built with concrete and equipped with advanced sprinkler systems, which significantly reduces the risk of fire spreading. In 2026, we're also seeing more tenants add specific riders for high-value items like e-bikes and home office tech. While these additions increase the renter insurance Canada cost slightly, they ensure that your most essential tools are protected against modern risks.
The 5 Key Factors That Influence Your Quote
Your monthly premium isn't a random number. It's the result of a sophisticated algorithm designed to predict risk. In 2026, these calculations have become even more precise, looking at everything from your building's plumbing to your remote work setup. Understanding these variables helps you see why the renter insurance Canada cost can vary so much between two people living on the same street. While every insurer weights factors differently, we've ranked the most impactful drivers below.
The ranking of influence typically follows this order: your personal claims history, the age and infrastructure of the building, your chosen coverage limits, the geographic location, and finally, your deductible. A major trend in 2026 is the surge in electronics value. With high-end home offices now standard, many tenants are increasing their content limits to protect expensive monitors and ergonomic setups, which naturally nudges the premium upward. However, accurately calculating your content value prevents you from over-insuring and wasting money on coverage you'll never use.
Building Characteristics and Location
Insurers look closely at what your home is made of and how it's maintained. Older buildings with galvanized steel plumbing or knob and tube wiring carry a higher risk of leaks and fires, leading to higher quotes. Conversely, modern concrete high-rises often enjoy lower rates. Proximity to emergency services is another critical factor; being within 300 metres of a fire hydrant or close to a fire station can significantly lower your costs. Security features also play a massive role. Buildings with monitored alarms, 24/7 concierges, or secure fob access are viewed as lower risks for theft, which can translate into a direct discount on your monthly bill.
Personal Profile and Coverage Limits
Your personal history is often the "hidden" driver of your renter insurance Canada cost. Staying claim-free for three or more years is one of the most effective ways to keep your rates low. If you have a history of frequent claims, insurers view you as a higher risk. You also have direct control over your premium through your deductible. Choosing a $1,000 deductible instead of $500 can lower your monthly payment, but you must be certain you have those funds tucked away in case of an emergency. Finally, while it varies by province, a solid credit score can sometimes help you secure a more favourable rate, as it's often used as a proxy for financial responsibility and care.
How to Lower Your Renter Insurance Cost Without Sacrificing Coverage
Lowering your renter insurance Canada cost isn't about finding the most stripped-down policy available. It's about being smart with your selections. We often see tenants paying for "one-size-fits-all" plans that include coverage they simply don't need. A "right-sized" approach ensures that every dollar you spend is working to protect your specific lifestyle. This is where the "Broker Advantage" truly shines. Unlike a single insurance company, a broker acts as a helpful ally who can scan the entire market to find niche discounts tailored to your profession, your building's security upgrades, or even your alumni status.
If you're looking for a comprehensive roadmap to value, our guide on tenant insurance affordable Canada offers deeper context on balancing price and protection. By focusing on efficiency rather than just the lowest sticker price, you'll gain the peace of mind that comes from knowing you're actually covered when it counts.
Smart Bundling and Loyalty Discounts
The most powerful tool in your savings arsenal is bundling. When you combine your tenant coverage with cheap car insurance Canada, many insurers will reward you with a multi-policy discount. For claim-free and conviction-free clients, these savings can reach up to 30%. It's a significant reduction that effectively puts money back in your pocket every month. Beyond the initial bundle, staying with a consistent broker helps you build a "safe record" history. Over time, this proven track record of responsibility makes you a more attractive client, often leading to lower renewal rates that a new customer wouldn't be able to access.
Policy Tweaks for Immediate Savings
You can also make immediate changes to your policy to nudge your renter insurance Canada cost downward. Start by reviewing your deductible. If you have a healthy emergency fund, increasing your deductible from $500 to $1,000 can lower your premium. You're essentially betting on your own safety, which insurers love to see. Next, take a hard look at your contents list. Don't pay for $50,000 in coverage if your furniture, tech, and clothing only total $20,000. Finally, check your payment frequency. Many insurers charge a small administrative fee for monthly processing. If your budget allows, paying your premium annually can eliminate these extra costs entirely. Start your online quote with Verdant Insurance today to see which of these savings strategies fits your life best.
Choosing the Right Policy with Verdant Insurance
Finding the right balance between protection and price shouldn't feel like a part-time job. While we've explored the various factors that dictate the renter insurance Canada cost, navigating these variables on your own can be overwhelming. Verdant Insurance acts as your proactive guide, blending a digital-first platform with the genuine human support you need when things get complicated. We don't just give you a number; we help you understand the value behind it.
Our broker model is designed specifically for the modern renter. Instead of forcing you into a rigid, pre-packaged plan, we do the heavy lifting by comparing multiple partner insurers to find the best value for your specific situation. This means you benefit from a tailored approach that respects your budget while ensuring your peace of mind is never compromised. It's about getting the coverage you actually need, delivered with the transparency you deserve.
The Verdant Difference: More Than Just a Quote
We believe that insurance should grow with you. Your needs as a first-time renter in a studio apartment are different from those of someone moving into a larger shared space with friends. If you're living with others, our specialized guide for tenant insurance for roommates provides essential tips for managing shared liabilities and contents. At Verdant, we offer customizable policies that adapt to your journey, ensuring you're always protected without overpaying for redundant features.
Our commitment to you doesn't end once the policy is signed. We provide dedicated support for every stage of your rental life. Whether you have a simple question about your coverage limits or you need help navigating a claim, our team is present and ready to assist. We take pride in being a tech-forward broker that hasn't lost its human touch, making the entire process feel effortless from start to finish.
Start Your 2026 Savings Journey Today
If you're currently with a high-cost provider, switching is simpler than you might think. We handle the complexities so you can focus on enjoying your home. Our digital platform allows you to get a tailored quote in minutes, providing a clear view of your potential savings. Remember, claim-free and conviction-free clients can save up to 30%, making it the perfect time to review your options and secure a better rate.
Don't let confusion over the renter insurance Canada cost keep you from the protection you need. It’s time to move forward with a partner who prioritizes your security and your wallet. Take the first step toward a more secure and affordable 2026 by connecting with our team. Get your personalized renter insurance quote today and discover how easy it is to protect what matters most.
Secure Your Space for 2026
Protecting your home shouldn't be a source of stress. We've seen that while the renter insurance Canada cost stays relatively stable, the real value comes from a policy that fits your specific needs. By right-sizing your coverage and understanding the impact of your building's safety features, you can avoid overpaying for protection you'll never use. Remember that staying claim-free and bundling your services remain your most effective tools for keeping monthly rates manageable. You have the power to control your premiums without leaving your belongings at risk.
It's time to stop guessing and start saving. At Verdant Insurance, we help you compare rates from Canada's top insurance partners instantly to ensure you get the best possible deal. We're already trusted by thousands of Ontario renters for their 2026 coverage, and we'd love to help you too. If you have a clean driving and insurance record, you could save up to 30% on your premium. Get a personalized renter insurance quote in minutes and enjoy the peace of mind that comes with knowing your home is truly protected. You've worked hard for what you own; let's make sure it's safe.
Frequently Asked Questions
What is the average cost of renter insurance in Canada in 2026?
The average cost for renter insurance in Canada in 2026 is approximately $21.74 per month. While many tenants pay between $19 and $50, your final price depends on your province and the amount of contents coverage you select. For example, renters in Newfoundland often see the lowest rates. Those in Quebec might pay slightly more due to different standard deductibles. It's always wise to compare quotes to see where your specific unit falls.
Can I lower my renter insurance cost if I have a roommate?
Sharing a policy with a roommate can often reduce the individual renter insurance Canada cost for each person. When you split a single premium, the total amount is typically higher than a solo policy because there are more belongings to cover. However, the cost per person is significantly lower. Check your lease requirements first. Some landlords prefer each tenant to hold their own separate liability coverage to avoid legal complications.
Does renter insurance cost more for basement apartments?
Basement apartments can sometimes command higher premiums due to an increased risk of water damage and sewer backups. Insurers view below-grade units as more susceptible to flooding during heavy rain or pipe bursts within the building's infrastructure. To keep your costs manageable, ask about specific water protection endorsements. You might find that installing a water leak sensor or a sump pump alarm helps reassure your provider and keeps your monthly rate lower.
How much coverage do I need for my personal belongings?
You should aim for a coverage limit that reflects the total replacement cost of everything you own at today's retail prices. Most Canadian renters find that $20,000 to $30,000 is a standard starting point for a one-bedroom apartment. Don't forget to include high-value items like laptops, e-bikes, and furniture. Conducting a quick room-by-room inventory is the most accurate way to ensure you aren't paying for extra coverage you don't need.
Will my renter insurance cost go down if I have a security system?
Yes, having a monitored security system or a 24/7 concierge can lead to a noticeable discount on your premium. Insurers reward tenants who take proactive steps to reduce the risk of theft and vandalism. Even simple features like deadbolts, smoke detectors, and fire extinguishers contribute to a safer profile. Mention any smart home security devices you've installed when you request your quote. These modern tech additions are increasingly recognized by 2026 insurance algorithms.
What happens to my insurance cost if I move to a different city in Ontario?
Your insurance cost will likely change because premiums are heavily tied to your specific postal code and local crime statistics. Moving from a smaller hub like Ottawa to downtown Toronto often results in a slight increase because of the higher density and associated risks. However, moving to a newer building in a different city might actually lower your rate if the new structure has better fire protection or security features than your previous home.
Is it cheaper to pay for tenant insurance monthly or annually?
Paying your premium annually is almost always cheaper than choosing a monthly payment plan. Most insurance providers apply a small administrative or processing fee to each monthly transaction to cover the extra billing work. By paying the full amount upfront, you eliminate these recurring fees. This can often save you the equivalent of one full month of coverage over the course of the year. It's a simple way to optimize your budget.
Does my credit score affect my renter insurance quote in Ontario?
In Ontario, insurers are permitted to use your credit score as a factor when determining your renter insurance Canada cost. A higher score is often seen as an indicator of financial responsibility. This can lead to more competitive rates. While it's not the only factor, a healthy credit history helps you access lower quotes. If you prefer not to share this info, some providers still offer coverage, though the rate might be higher.


