

What if a decade of safe driving experience in your home country didn't simply vanish the moment you landed at Pearson International? For many arriving in Markham or Toronto, the excitement of a new start is often dampened by the realization that finding car insurance for newcomers in Ontario can feel like starting from zero. It's frustrating to be treated like a teenager behind the wheel when you've spent years driving in busy city centres elsewhere. You're likely dealing with the confusing G1, G2, and G licensing tiers while trying to track down elusive driving records from home just to avoid sky-high premiums.
We understand that you want to get on the road quickly and affordably. This guide will show you exactly how to bridge the gap between your past experience and your new life in the province, ensuring your international history counts toward your new policy. We'll walk through the licence exchange process, explain how to secure a valid Ontario pink slip, and share tips for finding a policy that respects your budget. By the end, you'll have a clear path to getting the coverage you need without the unnecessary stress.
Key Takeaways
- Identify if your home country has a reciprocal agreement with Ontario for an immediate licence exchange.
- Understand the specific components of the Ontario Automobile Policy (OAP 1) that are mandatory for all drivers.
- Learn how to leverage your international driving history to help secure a better rate for car insurance for newcomers in Ontario.
- Discover how your local neighbourhood and vehicle choice play a significant role in determining your insurance premiums.
- Find out why partnering with a broker helps you access insurance companies that specialize in helping new residents.
Understanding Mandatory Car Insurance in Ontario for Newcomers
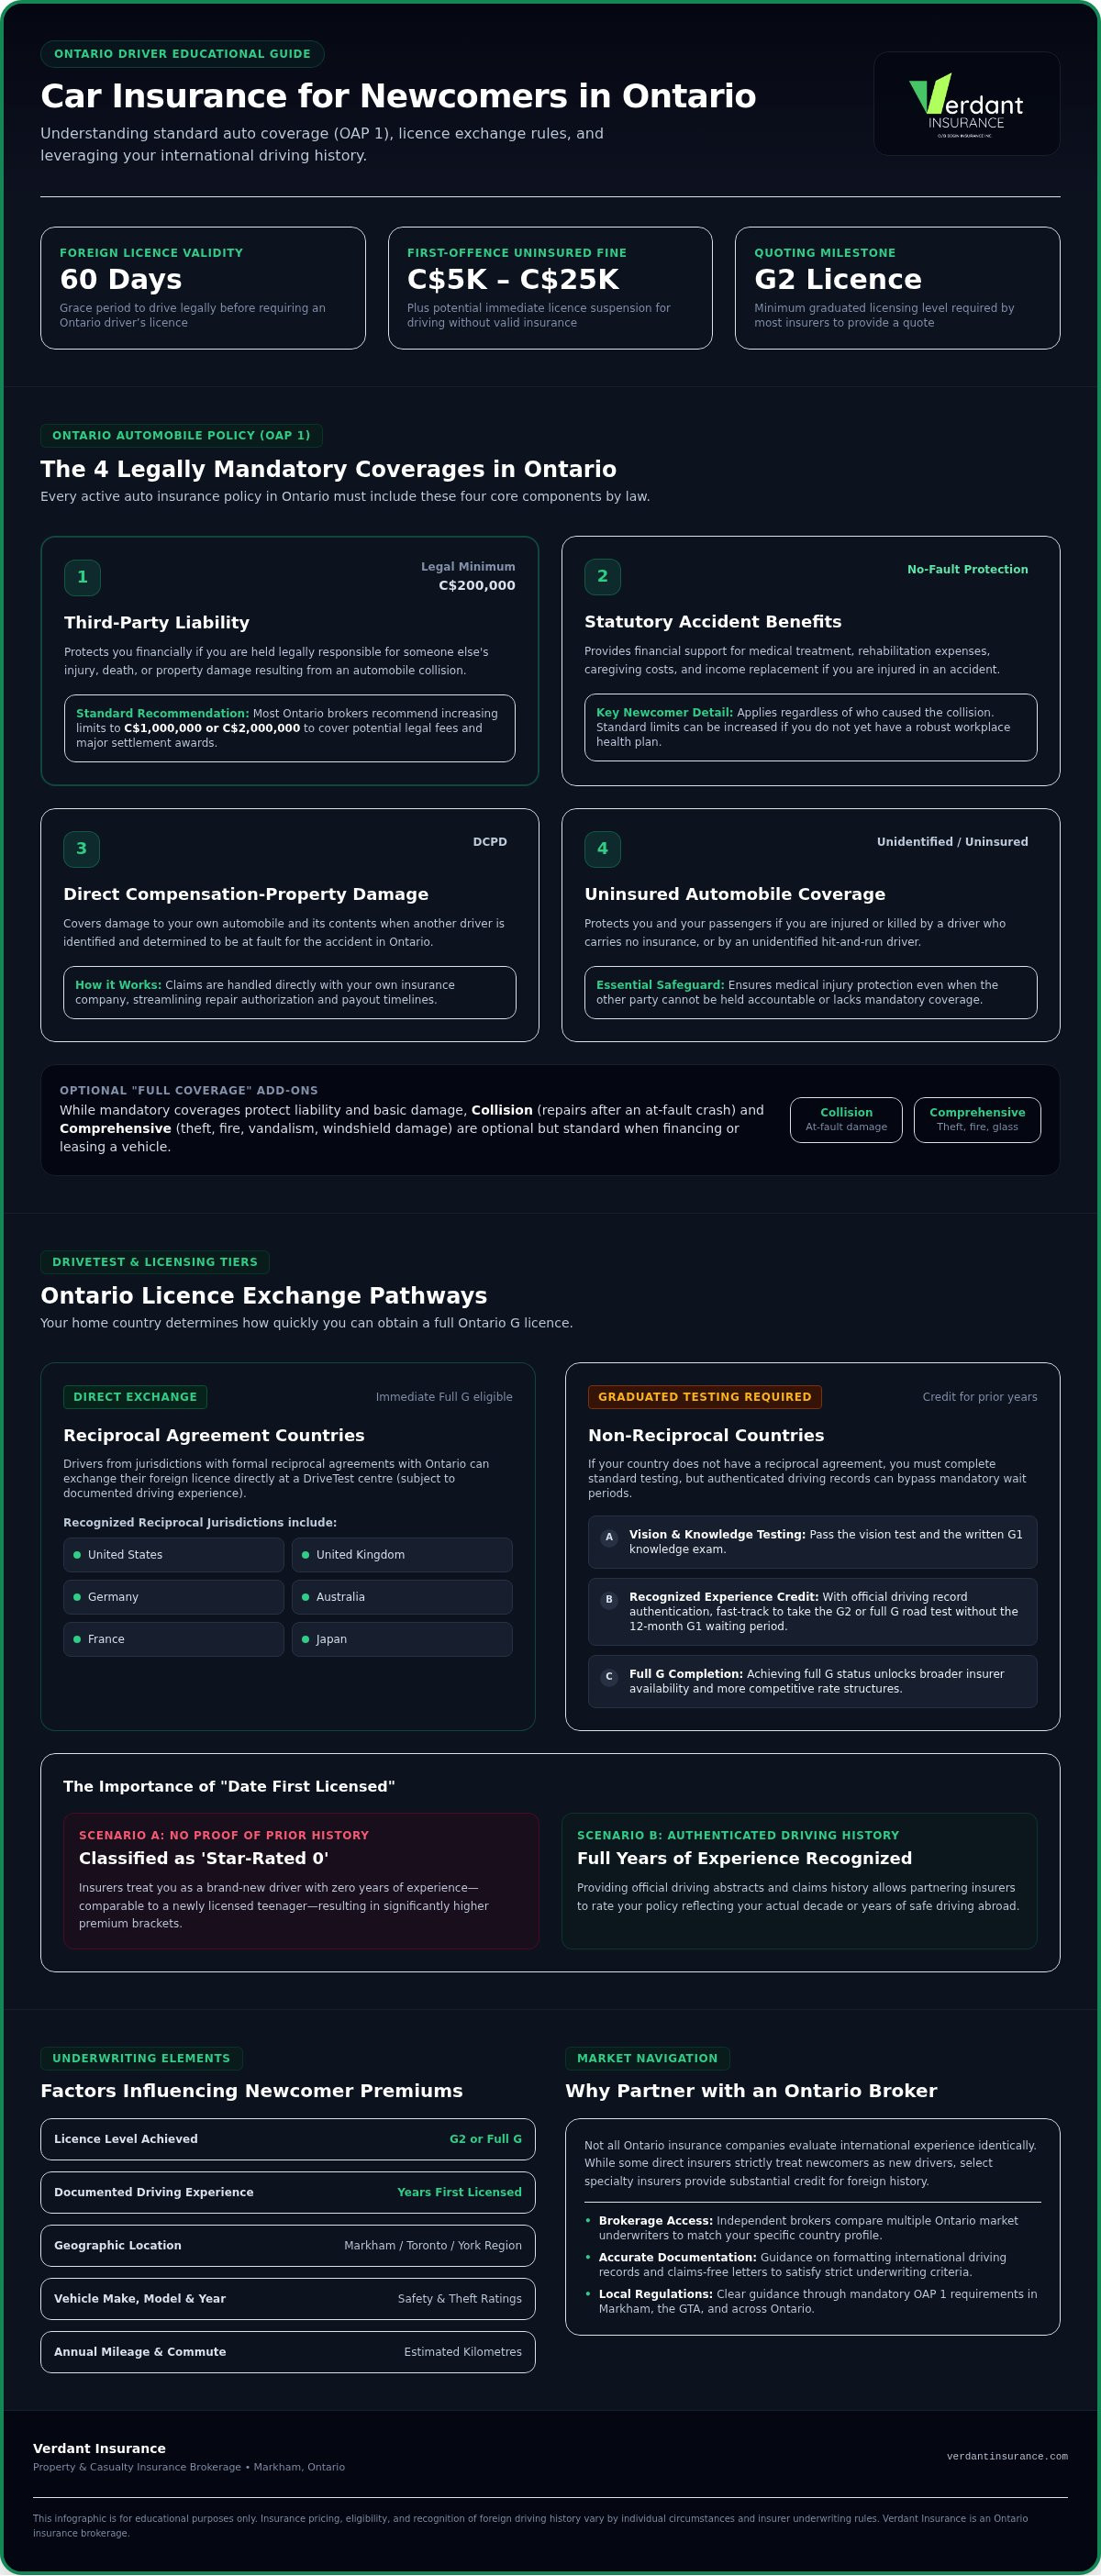
Every driver in the province must follow the rules set out in the Ontario Automobile Policy (OAP 1). This is the standard document that defines your rights and responsibilities. When searching for car insurance for newcomers in Ontario, you'll find that while every policy looks slightly different, the foundational coverages remain the same across all insurers because they are required by law. These regulations ensure that everyone on the road has a basic level of protection.
Ontario law requires four specific types of coverage. First, Third-Party Liability protects you if you're responsible for someone else's injury or property damage. Second, Statutory Accident Benefits provide medical and rehabilitation care. Third, Uninsured Automobile coverage protects you if you're hit by a driver who doesn't have insurance or by a hit-and-run vehicle. Finally, Direct Compensation-Property Damage (DCPD) covers damage to your vehicle when another driver is at fault. These four components form the base of every valid policy in the province.
Don't take these requirements lightly. Driving without a valid policy is a serious offence in Ontario. Fines for a first conviction can range from C$5,000 to C$25,000, and you could face an immediate licence suspension. It's much safer and more affordable to secure a policy before you hit the road. Getting your insurance sorted is one of the most important steps in your relocation journey.
Statutory Accident Benefits in Ontario
These benefits are a cornerstone of Ontario's insurance system. They provide financial support for medical expenses, income replacement, and caregiving if you're injured in an accident. The best part? These benefits apply regardless of who caused the crash. While there are standard limits set by the government, you can choose to increase your coverage. Newcomers should carefully consider their personal health needs when setting up car insurance for newcomers in Ontario. If you don't have a robust workplace health plan yet, increasing these limits can provide essential peace of mind during your first few years in Canada.
Third-Party Liability: Protecting Your Assets
This coverage is designed to protect your financial future. If you're involved in a lawsuit following a collision, liability coverage pays for legal costs and settlements. While the legal minimum in Ontario is C$200,000, most brokers recommend C$1 million or C$2 million. In a world where medical costs and legal fees are high, the minimum is rarely enough to cover a serious claim. Even though Ontario uses a no-fault system for most claims, you can still be sued for significant amounts in certain cases. Most standard vehicle insurance coverage models prioritize this protection because it safeguards your savings and future earnings from a single mistake on the road.
Beyond the mandatory items, you'll often hear about "full coverage." This usually refers to adding Collision and Comprehensive options to your policy. Collision pays for repairs to your own car after an accident, while Comprehensive covers non-collision events like theft, fire, or windshield damage. While not required by law, these are highly recommended if your vehicle has significant value or if you are financing your car through a dealership.
The Ontario Driver’s Licence Exchange: How It Affects Your Rates
Your foreign licence is valid for 60 days after you arrive in the province. After that grace period, you must have an Ontario licence to continue driving legally. This transition is a major factor in securing car insurance for newcomers in Ontario. The province uses a graduated licensing system consisting of G1, G2, and full G licences. Most insurers won't provide a quote until you have at least a G2. The speed at which you move through these levels depends entirely on where you're moving from and your documented history.
Insurers look closely at your 'Date First Licensed' from your home country. This date determines your years of experience, which is a primary driver of your premium. If you can't prove you've been driving for years, you'll likely be rated as a 'star-rated' 0 driver. This classification treats you the same as a brand-new teenage driver, regardless of your actual age. Getting your Ontario licence quickly is the first step to unlocking lower premiums.
Reciprocal Countries vs. Non-Reciprocal
Ontario has agreements with several countries, including the United States, United Kingdom, Germany, Australia, France, and Japan. If you're from one of these reciprocal nations, you can often swap your foreign licence for a full G licence immediately at a DriveTest centre. If your country isn't on the list, you'll need to pass a vision test and a written knowledge test to get a G1. From there, you can often book a road test immediately if you have proof of previous experience. Following the Ontario driver's licence exchange rules precisely helps you avoid unnecessary waiting periods and gets you insured faster.
Proving Your Driving History
A clean history abroad is your best asset. You'll need a Driver's Abstract or a 'Letter of Experience' from your previous insurance company to prove your record. This document should detail how long you've been insured and whether you've had any claims or accidents. It's the only way to bridge the gap between your past and your new life in Ontario. Not all Ontario insurers accept foreign letters of experience, making a broker's help vital. A knowledgeable Ontario broker can identify the specific companies that recognize your international record, ensuring you don't pay more than necessary. This expert guidance helps you find a policy that fits your budget while you settle into your new home.
Factors That Influence Insurance Costs for New Residents
While your driving history is a major piece of the puzzle, several local factors determine the final price of car insurance for newcomers in Ontario. Insurers use complex calculations to assess risk, and many of these variables are specific to your new life in the province. Understanding these can help you make choices that keep your premiums manageable as you settle in.
Your Ontario postal code is one of the first things an insurer looks at. If you live in a high-traffic area like downtown Toronto, your rates will likely be higher than if you settled in a quieter part of Markham or York Region. This isn't personal; it's based on local claim statistics, theft rates, and traffic density. Similarly, your daily commute across the GTA plays a role. A short drive to a local GO Station usually costs less than a long daily trek on the 401 or 407. Be honest about your annual mileage to ensure your coverage remains valid.
The vehicle you choose also impacts your costs through the CLEAR (Canadian Loss Experience Automobile Rating) system. This system rates every car based on how likely it is to be stolen, its safety features, and the cost of repairs. A car that is expensive to fix or popular with thieves will always cost more to insure. Many people believe there is a "Newcomer Surcharge" designed to penalize them, but this is a myth. High initial rates are usually due to a lack of local actuarial data. As you build a Canadian track record, these costs typically stabilize according to the Financial Services Regulatory Authority of Ontario auto insurance guidelines.
Standard vs. High-Risk Insurers
Newcomers are often categorized into two different markets. Standard insurers prefer drivers with several years of verifiable North American experience. If your international history isn't recognized or you're from a non-reciprocal country, you might start in the "non-standard" or high-risk market. In rare cases where no private company will offer a policy, you may be referred to Facility Association, the insurer of last resort. The good news is that this isn't permanent. After just one year of clean driving in Ontario, you can often move back to a standard market with much more competitive pricing.
Temporary Car Insurance for Visitors to Ontario
It's a common misconception that you can buy a 30-day "temporary" policy in Ontario. The private insurance system here isn't set up for short-term residents in that way. If you're visiting for a few months, your best option is usually to rely on the insurance provided by a rental car company. If you're staying with family and using their vehicle, they must contact their broker to add you as a secondary driver. For visitors staying up to six months, some insurers might offer a short-term policy, but these are rare and subject to strict eligibility rules. Always confirm these details before you get behind the wheel to avoid a gap in coverage.
Step-by-Step: Getting Your First Ontario Auto Insurance Policy
Securing your first policy is a major milestone in your relocation journey. You've likely already visited a DriveTest centre and started the licence exchange process. Now, you need to turn that piece of plastic into a valid insurance pink slip. The process of finding car insurance for newcomers in Ontario is straightforward if you have your paperwork ready and understand what insurers are looking for.
Once you have your documents, you need to decide on your coverage levels. If you've bought an older car for cash, you might choose to stick closer to the mandatory minimums. However, if your vehicle is newer or financed, you'll almost certainly need Collision and Comprehensive protection. It's vital to get multiple quotes to compare how different insurers treat international experience. Some companies are much more flexible than others when it comes to recognizing your history, and a broker can help you identify these specific insurers quickly.
The Documentation Checklist
Accuracy is your best friend when applying for a policy. If your foreign driving record is in a language other than English or French, ensure it's translated by a certified translator. You'll also need your Vehicle Identification Number (VIN) and your vehicle's purchase agreement or bill of sale. Most importantly, ensure your 'Letter of Experience' is on official company letterhead from your previous insurer. This professional documentation is what allows a broker to advocate for your years of safe driving abroad, potentially saving you from being rated as a brand-new driver.
Ways to Save as a Newcomer
While premiums can be higher during your first year, there are several ways to lower your costs. Bundling your auto insurance with tenant or home insurance is one of the most effective methods to secure a multi-policy discount. In Ontario, installing winter tires between November and April also earns you a specific discount with most companies. You might also consider Usage-Based Insurance (UBI). This involves letting an app track your safe driving habits to earn a personalized discount over time. Finally, choosing a higher deductible can reduce your monthly premium, provided you have enough savings to cover that amount if an accident happens.
Before you finalize your policy, review the wording carefully. You have a legal obligation to disclose all licensed drivers in your household, even if they don't plan to drive your car. Failing to disclose this information can lead to a denied claim or even policy cancellation. Taking the time to be thorough now ensures you're fully protected as you start your life on Ontario roads.
Why Working with an Ontario Insurance Broker is Vital for Newcomers
Unlike a direct insurance company that only sells its own products, a brokerage like Verdant Insurance works for you. This distinction is vital when searching for car insurance for newcomers in Ontario because it opens doors to multiple companies at once. We maintain relationships with a wide network of partner insurers, each with different rules for international experience. Some companies are rigid, while others have developed flexible underwriting specifically for new residents. We know exactly where to look to find the right fit for your situation.
A broker acts as your personal advocate during the application process. When you provide a foreign letter of experience or a translated driving record, we ensure the insurer interprets those documents correctly. We push to make sure your years of safe driving abroad are applied to your premium calculation. This support continues long after you sign your first policy. As you build your Canadian credit history and local driving record, we monitor your renewals to see if you've become eligible for more competitive rates in the standard market.
Personalized Advice for the Ontario Market
Living in the GTA comes with unique challenges that a computer algorithm might miss. Whether it's the high traffic volume on the 401 or specific theft risks in certain neighbourhoods, local expertise matters. Understanding the digital advantage of choosing an online insurance broker in Canada helps you see how modern tools and human expertise work together. You get the speed of a digital quote with a professional who understands the nuances of Markham, Richmond Hill, and Toronto. We help you navigate these local risks so your coverage is never a guessing game.
Your Path to Peace of Mind
Moving to a new country involves a mountain of paperwork for housing, employment, and schooling. Our goal is to simplify the insurance piece of that puzzle. By building a long-term relationship with a broker in Markham or the York Region, you gain a partner who tracks your progress as a driver. As you move from your first year to your fifth in Canada, your insurance needs will naturally evolve. Having a professional who knows your history from day one makes every policy change feel effortless. Speak with a Verdant Insurance broker today to find a policy that honours your driving history and provides the security your family deserves.
Driving Forward in Your New Home
Navigating the insurance market doesn't have to be a roadblock in your relocation journey. By securing your official driving records and exchanging your licence promptly, you've already handled the most difficult parts of the transition. Remember that car insurance for newcomers in Ontario is highly individual. Your choice of vehicle, your specific GTA neighbourhood, and how well you document your past history all play a role in your final premium. It's about more than just finding a policy; it's about finding a partner who understands your unique path.
Partnering with a local expert ensures you aren't just another number in a database. We take pride in serving Markham and the wider GTA by connecting you with multiple Ontario insurers who value international experience. We advocate for your history so you can focus on building your new life with total peace of mind. Our expertise in international experience credits means we know which companies are ready to welcome you to the road.
Welcome to the province. We're ready to help you get behind the wheel with confidence and security.
Frequently Asked Questions
How long can I drive with my foreign licence in Ontario?
You can legally drive in Ontario for up to 60 days using your valid foreign driver's licence. Once this initial 60-day period ends, you must obtain an Ontario driver's licence to continue operating a vehicle. It's best to start the exchange or testing process immediately upon arrival to avoid a gap in your ability to drive. This ensures you have the necessary provincial identification that most insurers require before they can bind a policy.
Can I get car insurance in Ontario with a G2 licence as a newcomer?
Yes, you can obtain car insurance for newcomers in Ontario once you have earned your G2 licence. While a full G licence is preferred by many companies and may lead to lower premiums, the G2 allows you to be the primary driver on a policy. Most insurance companies in the province won't provide a quote if you only hold a G1 learner's permit. G1 drivers always require a fully licensed supervisor in the vehicle.
Does my driving experience from my home country count in Ontario?
Your international driving experience can count toward your Ontario record, but its impact varies by insurer and your country of origin. Drivers from reciprocal countries often get immediate credit. For others, providing a certified driving history can help convince certain companies to recognize your years behind the wheel. Working with a broker is essential here; they know which specific companies are most likely to honour your previous history and apply the appropriate experience credits.
What is a 'Letter of Experience' and why do I need one?
A Letter of Experience is an official document from your previous insurance provider that details your coverage history and claims record. It's a critical tool for newcomers because it proves you aren't a new driver, despite being new to Canada. Without this letter, insurers may treat you as having zero experience, which typically results in higher premiums. Ensure it's on official company letterhead and translated by a certified professional if it isn't in English.
Is there such a thing as temporary car insurance for visitors in Ontario?
Ontario's private insurance system doesn't typically offer short-term or temporary 30-day policies for visitors. If you're visiting for a few weeks, your best option is the insurance provided through a rental car agency. If you're staying with family and using their vehicle, they must add you as a secondary driver on their existing policy. Always verify coverage with a broker before you drive a friend's car to ensure the policy remains valid during your stay.
Why is car insurance so expensive for new immigrants in the GTA?
High premiums for newcomers in the GTA are usually due to a lack of local Canadian driving and credit history. Insurers view this missing data as a higher risk. Additionally, areas like Toronto and Markham have high traffic density and higher claim frequencies, which naturally elevates costs for everyone in those postal codes. Building a clean local record over your first year is the most effective way to see these rates begin to decrease as insurers gain more data.
Do I need to tell my insurer if I have an international driver's permit?
You should inform your broker about your International Driver's Permit (IDP), but remember that it isn't a replacement for your actual licence. The IDP acts only as a certified translation of your home country's permit. While it helps police understand your credentials if you're pulled over, Ontario insurers still require your original foreign licence or a new Ontario licence to bind a policy. It doesn't grant extra experience points on its own but helps verify your current status.
Can international students get car insurance in Ontario?
International students can definitely secure car insurance for newcomers in Ontario, provided they have a valid Ontario licence and a vehicle registered in their name. Like any other resident, students should provide their previous driving history to help lower their costs. If you're living in a student residence or a rental apartment, bundling your auto policy with tenant insurance is an excellent way to access additional discounts while protecting your belongings from theft or damage during your studies.


