

If you just handed your teenager the keys to the family car, did you also just hand over your financial peace of mind? Most Ontario families feel a mix of excitement and dread when that G2 licence arrives. You're likely worried about the "high-risk" label that often comes with young drivers, or perhaps you're confused about how to find affordable car insurance for G2 drivers Ontario. It's a stressful time, but you aren't alone. In most cases, a new driver doesn't need a separate policy if they live at home, but they must be added to your existing coverage to stay legal.
We're here to show you that a G2 licence is a strategic investment in your future insurability. This 2026 guide will help you navigate the July 1 reforms to Statutory Accident Benefits and explain how the OPCF 49 opt-out might affect your Ontario household. We'll walk through passenger restrictions for young drivers and provide clear steps to help you manage premiums while building a clean driving record. From understanding household disclosure rules to comparing coverage options, you'll gain the clarity you need to keep your new driver protected and your budget intact.
Key Takeaways
- Understand the legal requirement to list G2 drivers on your policy and how the 2026 SABS reforms impact your mandatory accident benefits.
- Learn how to correctly structure car insurance for G2 drivers Ontario by distinguishing between primary and secondary driver roles based on vehicle ownership and use.
- Identify key factors that influence premiums, such as your location in the GTA and the lack of a prior driving history.
- Discover how MTO-approved training courses and telematics programs can help you manage costs while building a clean insurance record.
- Explore the benefits of working with an Ontario insurance broker to compare options from various insurers that are friendly to novice drivers.
Understanding Insurance Requirements for G2 Drivers in Ontario
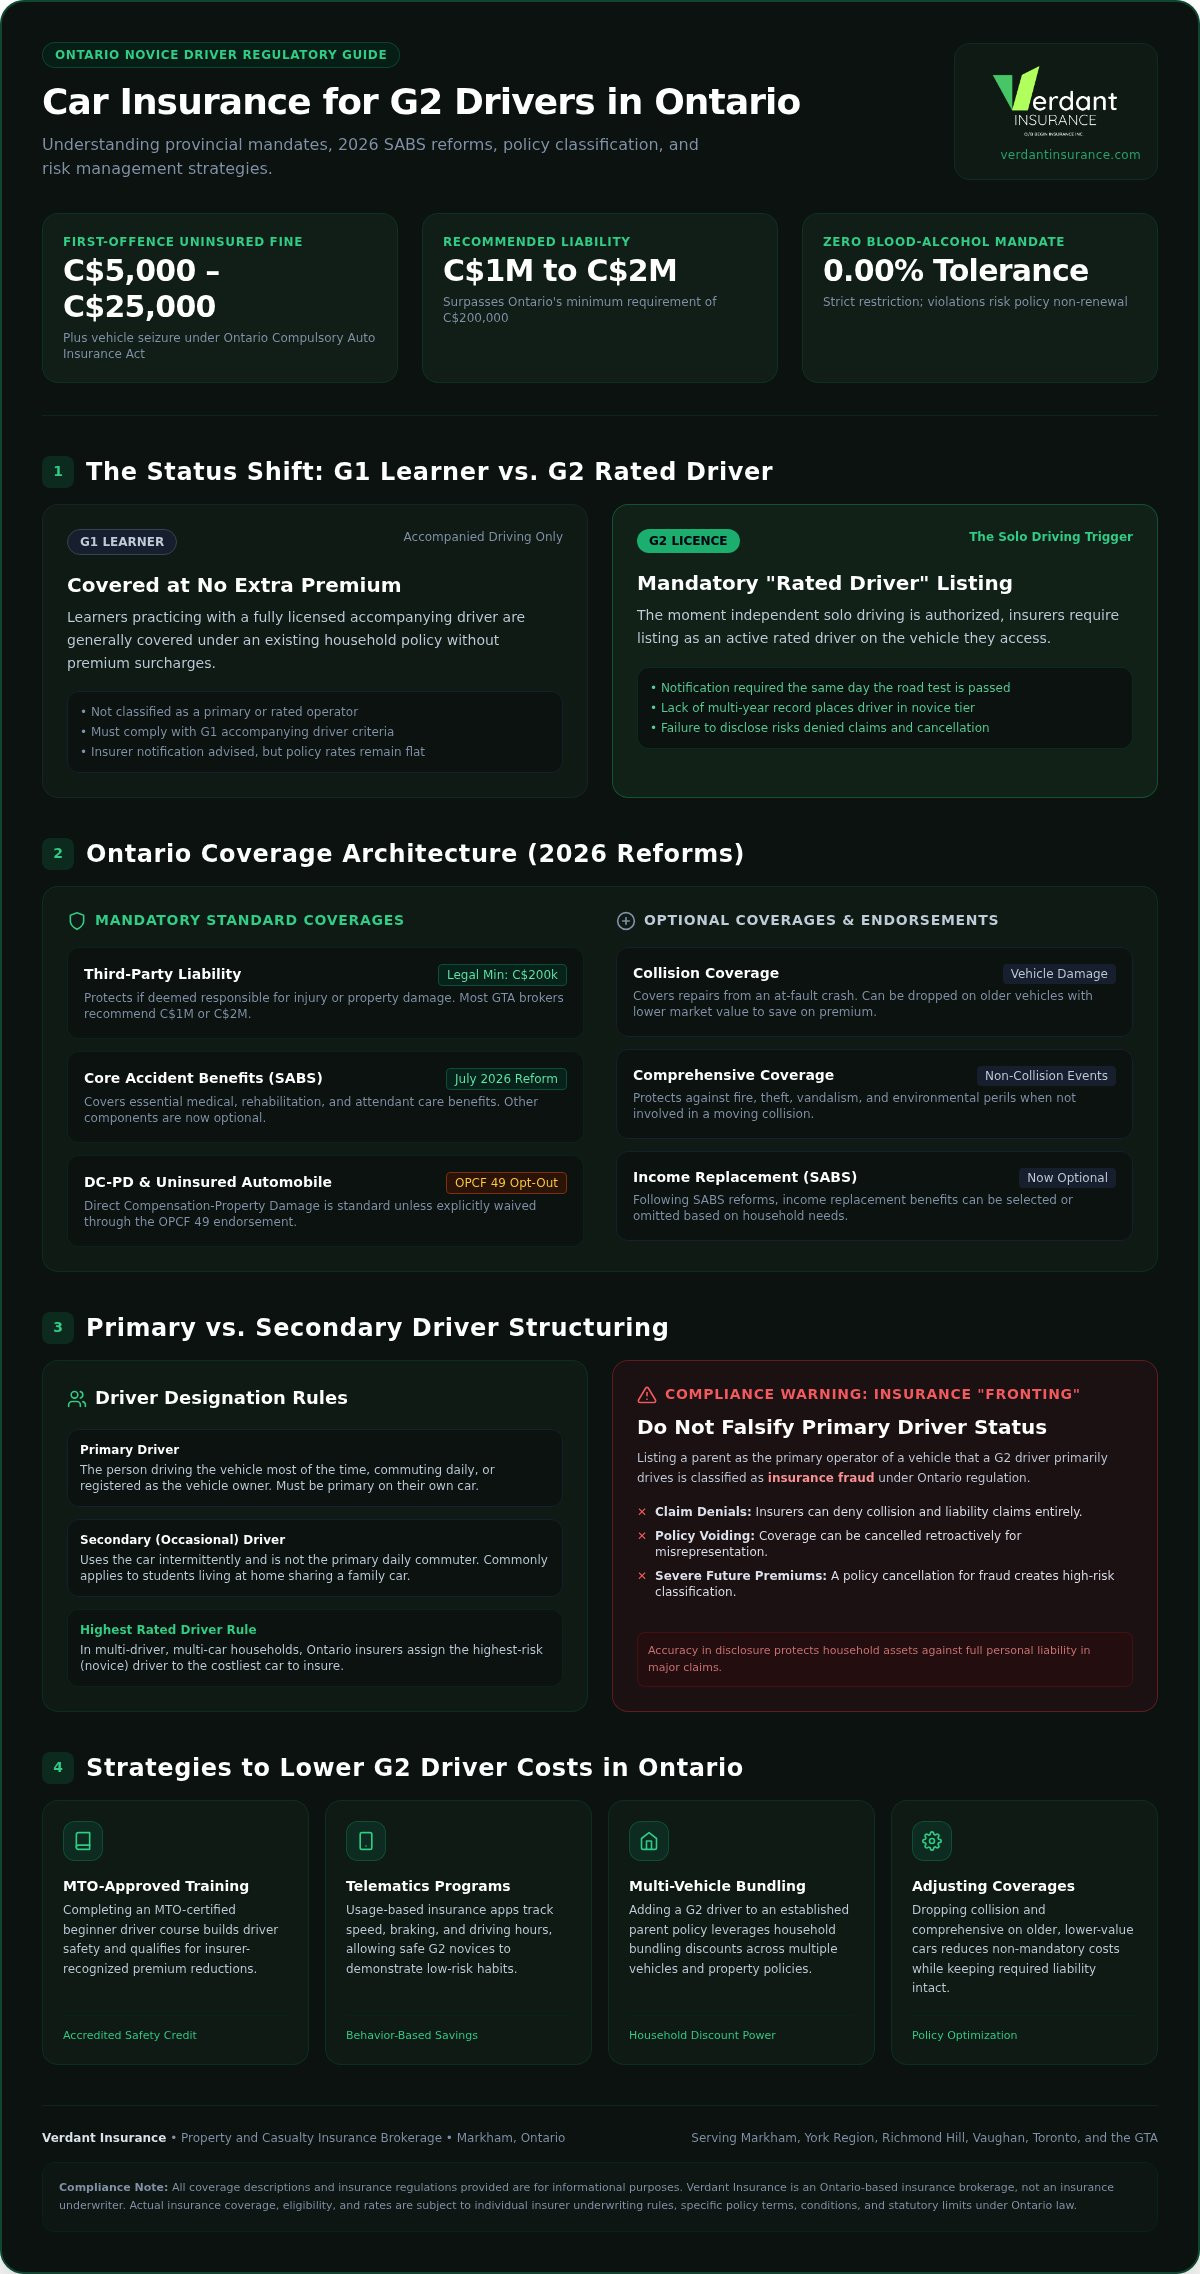
Passing your road test is a major milestone for any resident, but it also changes your legal relationship with the road. Under the Ontario Compulsory Automobile Insurance Act, every vehicle operated on public roads must be insured. While G1 learners are generally covered under a parent’s existing policy at no extra cost, the transition to a G2 licence is the "solo driving" trigger. Once you have the ability to drive independently, insurers require you to be listed as a rated driver. Failing to update your status isn't just a minor oversight; it can lead to denied claims or even policy cancellation. Finding the right car insurance for G2 drivers Ontario starts with understanding these baseline legal obligations.
Ontario uses a graduated driver licensing system to help novice drivers gain experience in lower-risk environments. Even though this system is designed to improve safety, insurers still view G2 drivers as higher risk because they lack a multi-year track record. Driving without valid insurance in Ontario carries severe penalties, including vehicle seizure and fines ranging from C$5,000 to C$25,000 for a first offence. These convictions also make it much harder to find affordable coverage in the future. It is important to remember that all coverage descriptions provided here are for informational purposes; actual coverage is subject to insurer eligibility, specific policy wording, limits, and exclusions.
The Difference Between G1 and G2 Insurance Status
You don't need to wait for your physical licence to arrive in the mail to notify your broker. You should call your brokerage the same day you pass your test. While your household likely didn't see a rate increase while you held a G1, the shift to G2 means you are now a "rated driver." This status reflects your new ability to drive alone at any time, within the standard provincial restrictions. It is your responsibility to ensure the insurer knows you have access to the vehicle to maintain continuous, valid protection.
Mandatory vs. Optional Coverages for New Drivers
Every Ontario policy must include Third-Party Liability, Uninsured Automobile coverage, and Direct Compensation-Property Damage (DC-PD), unless you specifically opt out of DC-PD via the OPCF 49 form. Since the July 2026 reforms, only core medical, rehabilitation, and attendant care benefits are mandatory within the Statutory Accident Benefits Schedule. Other benefits, like income replacement, are now optional. While the legal minimum for liability is C$200,000, most brokers in Markham and the GTA strongly recommend C$1 million or C$2 million to protect against rising litigation costs. If you're driving an older vehicle, you might choose to skip optional Collision or Comprehensive coverage to keep your car insurance for G2 drivers Ontario more manageable.
Primary vs. Secondary Driver: How to Structure Your Coverage
Choosing the right way to list a new driver on a policy is one of the most important decisions you'll make for your household budget. In Ontario, a secondary or occasional driver is someone who uses the vehicle but isn't the person driving it most of the time. This usually applies to students or young adults living at home. Conversely, a primary driver is the individual who uses the car for daily commuting or has the highest annual mileage. If a G2 driver owns their own vehicle, they must be listed as the primary driver, whether on their own policy or a household one.
Insurers in Ontario often use the "Highest Rated Driver" rule. This means if there are three drivers and three cars in a household, the insurer will typically assign the driver with the highest risk profile, usually the novice, to the vehicle that costs the most to insure. It's a way for companies to manage risk, but it can lead to unexpected premium jumps. Some families try to avoid this by "fronting," which is listing a parent as the primary driver of a car that a child actually drives every day. This is considered insurance fraud. If you're caught, the insurer can void the policy or deny a claim entirely, leaving you with massive out-of-pocket costs.
Being Added to a Parent’s Policy in Ontario
For most families in Markham or Vaughan, adding a teen to an existing policy is the most cost-effective path for car insurance for G2 drivers Ontario. It allows the new driver to benefit from the family's multi-vehicle and multi-policy discounts. However, parents should understand that any accidents or tickets the G2 driver receives will impact the entire policy. Since novice drivers must follow strict Ontario G2 licence restrictions, such as the zero blood-alcohol rule, any breach can lead to immediate policy non-renewal for the whole family. If you're unsure how a new driver will affect your current rates, it's helpful to speak with an Ontario insurance broker who can review your specific household needs.
Getting Your Own G2 Insurance Policy
Sometimes, independence is the better choice. Getting a standalone policy for a G2 driver allows them to build their own insurance history without risking a parent's clean record. To start, you'll need the vehicle's VIN, proof of ownership, and the driver's licensing details. Be aware that many Ontario insurers are hesitant to offer standalone car insurance for G2 drivers Ontario unless there is a supporting household policy, such as a parent's home or auto insurance, with the same company. While it's often more expensive, it ensures the young driver is fully responsible for their own premiums and driving habits from day one.
Factors That Drive Car Insurance Costs for G2 Drivers
Why does a G2 licence often come with a higher price tag? It's largely due to a lack of data. Insurers rely on historical driving records to predict future risk. Since a new driver hasn't built a multi-year history of safe habits, companies start with a higher baseline premium to account for that uncertainty. However, you aren't stuck with a high rate forever. One of the most effective ways to offset this initial cost is by completing an MTO-approved Beginner Driver Education (BDE) course. Most Ontario insurers recognize this training as the equivalent of three years of driving experience, which can lead to more manageable premiums right from the start.
As you look at the mandatory auto insurance coverage requirements, you'll see that every driver starts with a baseline risk profile. Beyond your experience level, insurers look at your vehicle's safety rating through the Canadian Loss Experience Automobile Rating (CLEAR) system. This system tracks how often specific car models are involved in claims, how much they cost to repair, and how well they protect passengers. Choosing a vehicle with a strong CLEAR rating is a proactive way to lower your car insurance for G2 drivers Ontario before you even hit the road.
The GTA Factor: Geography and Your Premium
In Ontario, where you park your car at night matters just as much as how you drive. Geographic Rating Territories allow insurers to set rates based on the claim frequency and traffic density of specific areas. If you live in Markham or elsewhere in York Region, you're driving in some of the busiest corridors in Canada. High traffic volume leads to more frequent "fender benders" and higher theft rates compared to a rural town or a city like Ottawa. Brokers use your postal code as a critical data point because it tells them about the local risks you face every day, from congested intersections to regional weather patterns.
Vehicle Selection for the G2 Driver
The type of car you choose can make or break your budget. While a brand-new SUV might have the latest safety tech, it's also more expensive to repair or replace if it's stolen. For many young people looking for car insurance for G2 drivers Ontario, a reliable used sedan is often the most practical choice. If the vehicle's market value is low, you might decide to carry only the mandatory liability and accident benefits, skipping optional collision and comprehensive coverage. This "liability-only" approach can significantly reduce your monthly costs while you focus on building a clean, claim-free record for the first few years of your driving career.
Strategies to Lower G2 Insurance Premiums in Ontario
Finding manageable car insurance for G2 drivers Ontario requires a proactive approach. You aren't just paying for today’s coverage; you're building a profile that insurers will reward for decades. One of the most effective strategies is the "Student Away at School" discount. If a G2 driver attends a university or college more than 100 kilometres from home and doesn't have a car at school, many insurers will reduce their portion of the premium. This keeps their insurance history active while acknowledging they only drive during holidays or visits home.
Bundling is another powerful tool for Ontario households. By combining the G2 driver's auto coverage with a parent's home insurance or the student's own tenant insurance, you can often secure a multi-policy discount. This simplifies your billing and shows the insurer that you're a loyal, multi-line client. While we previously discussed how an MTO-approved course reduces your road test wait time, its real value is the "three-year credit" it adds to your driver rating. This credit stays with you, helping you bypass the "zero-experience" pricing tier that many new drivers face.
Building a "Safe Driver" Profile from Day One
Your insurance history is one of your most valuable financial assets. Many people don't realize that being listed as a secondary driver on a G2 licence today is what makes your insurance affordable when you eventually get your G licence. You're building a "paper trail" of experience. To protect this, you must avoid minor convictions. A single speeding ticket can wipe out a "Conviction-Free" discount, which is one of the most significant savings opportunities in the Ontario market. At Verdant, we prioritize helping claim-free drivers maintain these discounts by providing advice on how to keep your record spotless as you transition through the graduated licensing stages.
Usage-Based Insurance (UBI) for G2 Drivers
If you're a safe driver, why wait years to prove it? Telematics or Usage-Based Insurance (UBI) allows Ontario insurers to track your driving habits in real-time through a mobile app. These programs monitor hard braking, rapid acceleration, and the time of day you drive. For a G2 driver, this is often the fastest way to earn a lower rate because it replaces general statistics with your actual performance. While some drivers have privacy concerns about sharing GPS data, the trade-off is a personalized premium based on your safety. It's a transparent way to take control of your costs while reinforcing the safe habits you learned in driver training.
How an Ontario Insurance Broker Helps G2 Drivers
Choosing a direct insurer means you're limited to their specific rules and pricing models. If you don't fit their ideal "risk profile," your rates might be higher than necessary. An Ontario insurance broker works differently. We act as a bridge to a wide marketplace of insurance companies, searching for the ones that specifically cater to novice drivers. This is especially helpful for finding car insurance for G2 drivers Ontario because different companies have different appetites for young drivers. Some might offer better discounts for telematics, while others specialize in families with multiple vehicles in the GTA.
Having a local expert in Markham or Richmond Hill means you get advice tailored to the York Region market. If the unexpected happens, you aren't calling a faceless call centre; you're speaking with an advocate who understands the local roads and claims process. We help you navigate the transition from G2 to a full G licence, ensuring your policy updates at the right time to capture any available rating improvements. This proactive guidance is essential for managing your long term costs as you move through the graduated licensing system.
Why One Size Does Not Fit All
Every G2 driver has a unique situation. A university student in Toronto has different needs than a young professional commuting from Vaughan. Brokers identify insurers with "New Driver" niches, which are specific programs designed to help novice drivers build history without excessive costs. We compare quotes across multiple partners to find the coverage limits that fit your budget while maintaining legal compliance. This customization ensures you aren't paying for extras you don't need, like rental car coverage if you have access to a second family vehicle, while still protecting your future insurability.
Next Steps: Getting Your G2 Quote
Ready to see your options? The process is straightforward when you have the right information prepared. To get an accurate quote for car insurance for G2 drivers Ontario, you'll need your licence issue date, the Vehicle Identification Number (VIN) for the car you'll be driving, and your MTO-approved driver training certificate. Once we have these details, we can typically provide a range of options within a business day. Binding coverage in Ontario is a methodical process, but we handle the heavy lifting so you can focus on driving safely.
Secure Your Future on the Ontario Roads
Transitioning into the G2 phase is a pivotal step toward long-term independence. As we've explored, managing your premiums involves more than just finding a policy; it requires a strategic approach to vehicle selection, driver training, and understanding the 2026 SABS reforms. By prioritizing a clean record and exploring options like telematics or the "Away at School" discount, you can effectively navigate the complexities of car insurance for G2 drivers Ontario.
At Verdant Insurance, our Markham-based team serves families across the GTA with a focus on professional reliability and personal care. We act as your advocate, providing access to a wide network of insurance partners to ensure your coverage is customized to your household's unique needs. We emphasize finding significant discounts for drivers who remain claim-free and conviction-free, helping you build a strong insurance foundation for the years ahead.
The road ahead is full of opportunity. With the right guidance and a commitment to safe driving habits, you can protect your financial future while enjoying the freedom that comes with your new licence.
Frequently Asked Questions
Do G2 drivers need their own insurance if they use a parent’s car?
You don't typically need a separate policy if you live in the same household as the vehicle owner. Instead, Ontario law requires that you be added to the existing household policy as a rated driver. Most families list novice drivers as secondary or occasional operators to ensure they're legally protected while driving. It's vital to notify your broker immediately after passing your road test to ensure the policy remains valid and accurate.
How much does car insurance cost for a G2 driver in Ontario in 2026?
The cost of car insurance for G2 drivers Ontario is highly individualized and depends on several factors. Insurers evaluate your specific postal code in the GTA, the safety rating of your vehicle, and your personal driving record. Since each insurance company uses different formulas to calculate risk for new drivers, premiums vary widely across the province. A broker can help you navigate these variables to find a policy that fits your specific budget and coverage needs.
Does a G2 driver’s insurance rate go down after they get their G licence?
Yes, graduating to a full G licence usually results in a premium reduction because it signals to insurers that you've gained experience and passed advanced testing. While the exact change varies by insurer, moving out of the graduated licensing system often removes novice driver surcharges. To ensure you see these benefits, it's important to maintain a clean record during your G2 phase, as tickets or accidents can quickly offset the benefit of a licence upgrade.
Can a G2 driver be the primary driver on a vehicle?
A G2 driver must be listed as the primary driver if they're the main operator of the vehicle or the registered owner. While some families try to list a parent as the primary driver for a car that a teen uses daily, this is considered "fronting" and is a form of insurance fraud. Correctly identifying the primary operator ensures your coverage remains valid and protects your financial interests if you ever need to file a claim.
Will a driver training course really lower my G2 insurance premiums?
Completing an MTO-approved Beginner Driver Education (BDE) course is an effective way to manage your initial rates. Most Ontario insurers recognize this certificate as the equivalent of three years of driving experience, which can lead to lower premiums for several years. Additionally, finishing the course allows you to take your G2 road test in just 8 months instead of 12, helping you build a continuous insurance history much faster.
What happens to my insurance if I get a ticket with a G2 licence?
A ticket can have a major impact on your insurance and your right to drive in Ontario. Novice drivers face stricter demerit point thresholds, with an automatic 60-day suspension at 9 points. Beyond legal penalties, a conviction usually results in the loss of safe-driver discounts at your next renewal. Maintaining a clean abstract is the most effective way to keep your premiums manageable as you work toward your full G licence.
Can I get insurance as a G2 driver if I don’t own a car?
You generally cannot purchase a standard auto policy for a vehicle you don't own. However, if you live at home and drive a family vehicle, you must be added to that policy as an occasional driver. This is the standard way to build a history of car insurance for G2 drivers Ontario. If you're a student away at school, being a listed driver on a parent's policy helps you earn future credits for continuous coverage.
Are there specific G2 licence restrictions that affect my insurance coverage?
Yes, breaching Ontario’s graduated licensing rules can lead to a denied claim or policy cancellation. G2 drivers must adhere to zero blood-alcohol requirements and specific passenger limits for those under 19 during late-night hours. If an accident occurs while you are violating these legal conditions, an insurer may determine that you have breached your policy contract. This could leave you personally responsible for any resulting damages or legal costs.


