

Did you know that sticking with your current provider during your next car insurance renewal in Ontario might actually leave you with less protection than you had last year? With the major regulatory shifts that took effect on July 1, 2026, many drivers in Markham and across the GTA are discovering that their standard policies look very different. It's completely natural to feel a bit of anxiety about moving your coverage, especially when you're worried about "short-rate" cancellation penalties or the risk of a coverage gap during the transition.
We understand that you want to find a better value without sacrificing the safety net your family relies on. This guide will show you the exact steps to switch your provider seamlessly while navigating the new landscape of optional benefits. You'll learn how to avoid unexpected fees, understand the 2026 reform changes to the OAP 1, and time your move perfectly to maximize your benefits. We'll break down the process into simple, manageable stages so you can feel confident that your new policy fits your life and your budget without any unnecessary stress.
Key Takeaways
- Identify the optimal window for switching to avoid short-rate cancellation penalties by aligning your move with your upcoming car insurance renewal ontario date.
- Learn how to calculate the true cost of a transition. This includes accounting for mid-term fees and the potential loss of multi-policy or loyalty discounts.
- Follow a clear five-step plan to ensure a seamless transition between providers. This helps you maintain the continuous coverage required by Ontario law.
- Recognize the risks of even a one-day coverage gap. It's important to understand how your policy history influences future eligibility and rates with Ontario insurers.
- Discover the advantages of working with an Ontario brokerage to compare multiple carriers and receive professional guidance through the 2026 regulatory changes.
Understanding When to Switch Your Car Insurance in Ontario
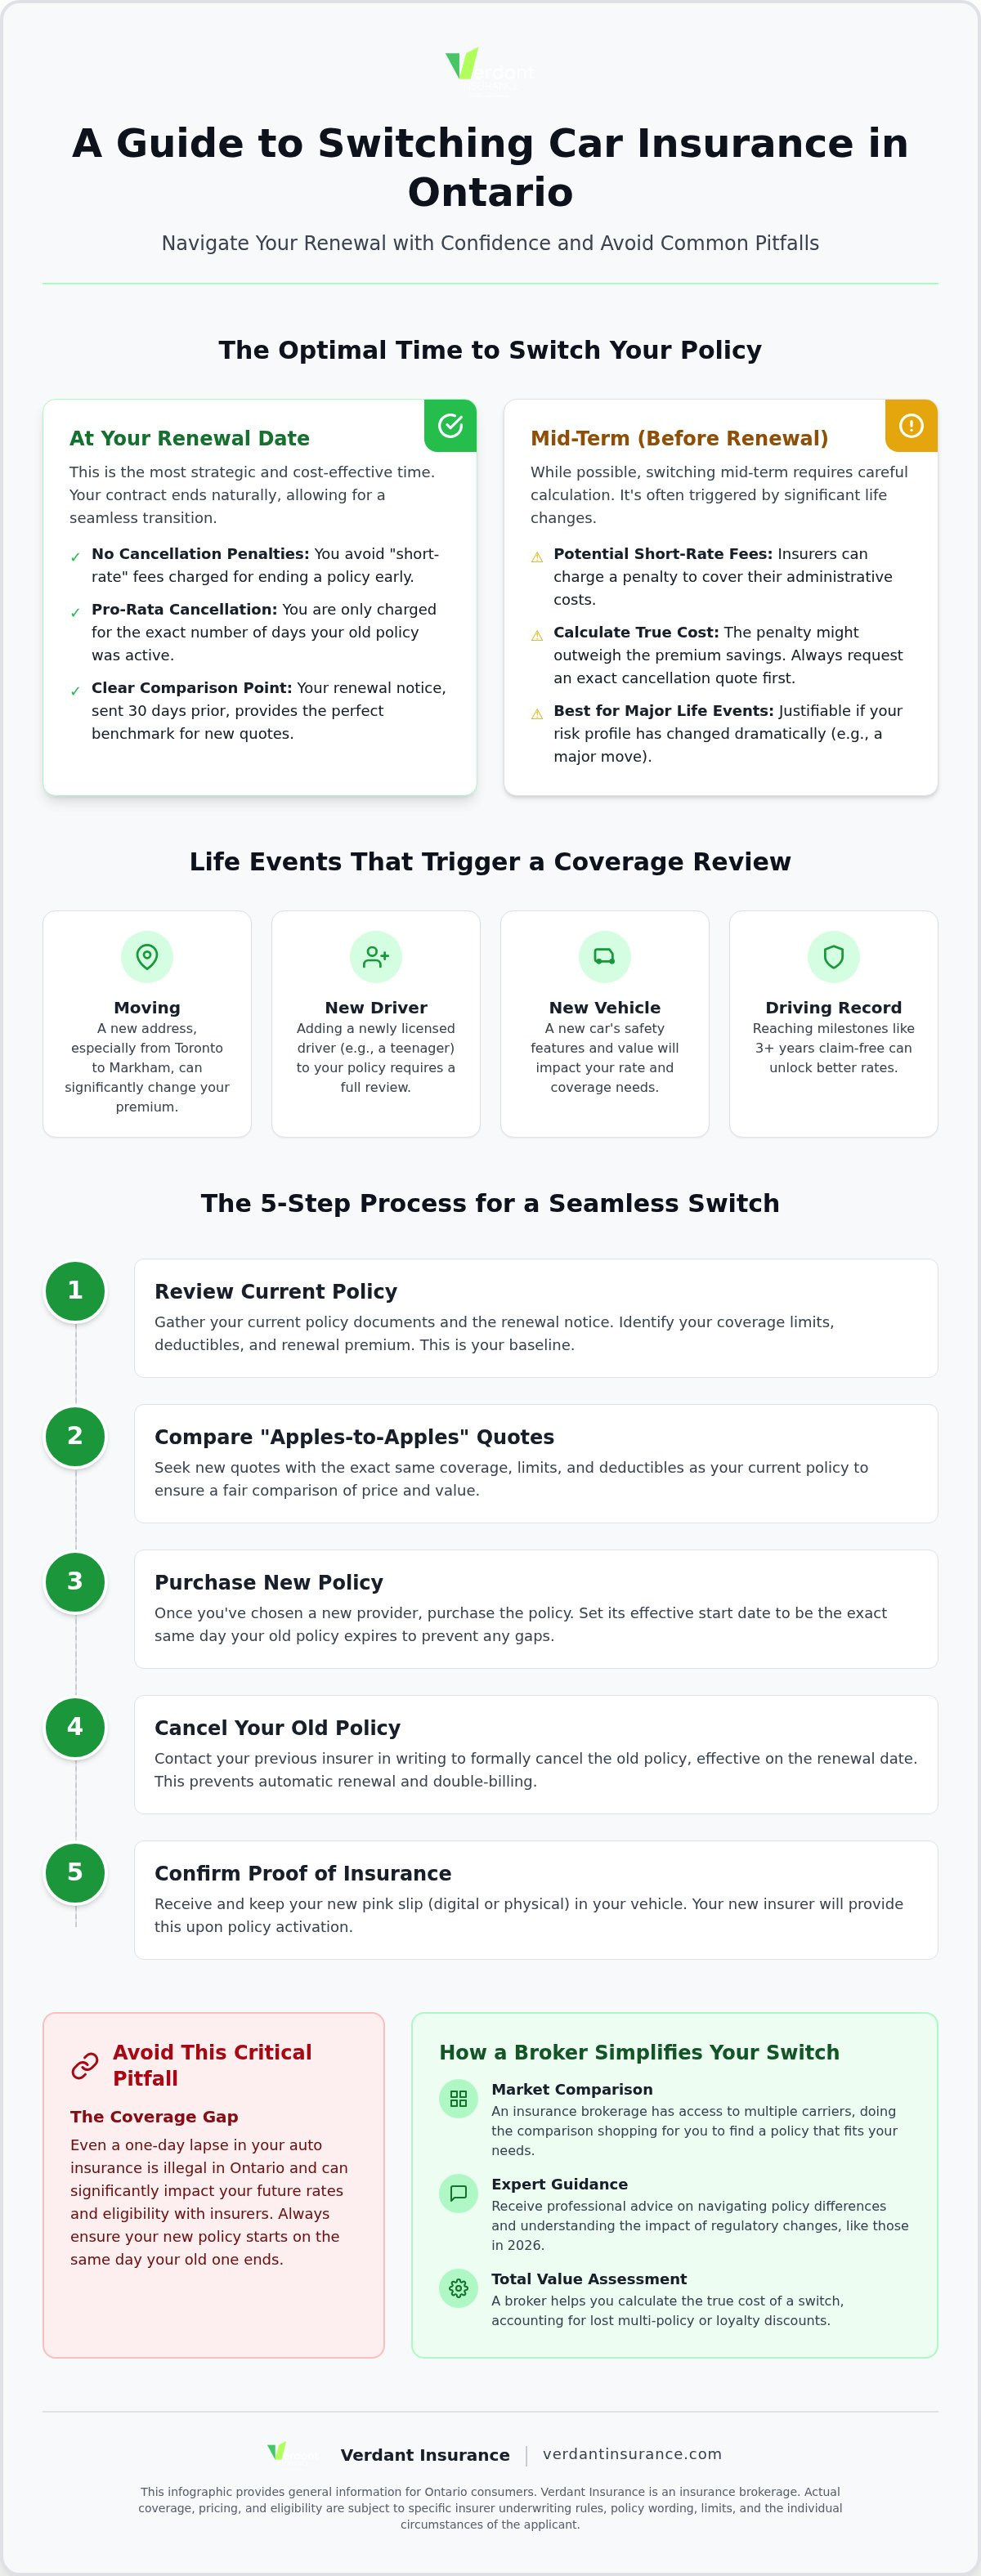
Are you wondering if there's a "perfect" time to move your policy? In Ontario, the most strategic time to explore your options is during your car insurance renewal ontario window. While you have the legal right to change providers at any time, doing so mid-term often involves administrative hurdles and financial penalties. Every driver in the province is protected by the Ontario Auto Policy (OAP 1), which is the standard contract used by all insurers. Even though the contract language is standardized, the pricing and service levels vary significantly between companies. Gaining a clear understanding your auto insurance policy is the first step toward making a move that actually benefits your bottom line.
Switching at Renewal vs. Mid-Term
Choosing to switch on your exact renewal date is generally the smoothest path forward. This is because insurers typically charge "short-rate" cancellation fees if you leave before the term ends. These fees are designed to cover the company's administrative costs and are calculated as a percentage of your remaining premium. If you wait for your renewal, you'll benefit from a pro-rata cancellation. A pro-rata cancellation means you are only charged for the exact number of days you were covered, with no additional administrative penalties applied. You can find your specific renewal date on your current pink slip or within the 30-day renewal notice that Ontario insurers are required by law to send you. This notice is a valuable document; it outlines your upcoming premium and any changes to your coverage, giving you a perfect benchmark for comparison.
Life Events That Trigger a Coverage Review
Sometimes, waiting for a renewal doesn't make sense if your circumstances have shifted. Major life changes often mean your old policy no longer fits your current reality. For example, moving from a high-traffic area in Toronto to a quieter neighbourhood in Markham or Richmond Hill can significantly change your risk profile. These geographic shifts often result in different rating factors being applied to your file. Other common triggers include:
- Adding a secondary driver, such as a teenager who just received their G2 license.
- Purchasing a new vehicle with advanced safety features that may qualify for different rates.
- Reaching a milestone like three or five years of claim-free and conviction-free driving.
In these cases, the potential benefits of a more tailored policy might outweigh any mid-term cancellation fees. An experienced broker can help you run the numbers to see if a mid-term move is financially sound. We focus on making sure your coverage reflects your actual life in the GTA, ensuring you aren't paying for risks that no longer apply to you.
Calculating the Costs and Benefits of a Change
Switching providers involves more than just finding a lower monthly bill. To understand if a move is truly beneficial, you must look at the "Total Annual Value" of your coverage. This means accounting for the potential loss of multi-policy or loyalty discounts that your current insurer provides. If you move your auto policy but leave your home or tenant insurance behind, the price of that remaining policy might increase. We often find that the most significant savings happen when you bundle multiple lines of business, but every situation is unique. A broker's role is to evaluate these moving parts across multiple carriers to ensure the math actually works in your favour.
Navigating Ontario Cancellation Fees
If you decide to switch before your car insurance renewal ontario date, you'll likely encounter a "short-rate" cancellation fee. Unlike a simple daily calculation, a short-rate table allows insurers to keep a higher percentage of the premium to cover administrative costs. These fees are typically front-loaded; the earlier you cancel in your policy term, the higher the penalty will be. We recommend calling your current company to ask for an exact "cancellation quote" for a specific date. This removes the guesswork and tells you exactly how much equity you have left in your policy. In certain circumstances, such as the sale of a vehicle without a replacement or the passing of a policyholder, some Ontario insurers may choose to waive these administrative fees. According to Ontario's insurance regulations, companies must be transparent about how they calculate these costs, so don't hesitate to ask for a breakdown.
The "Total Value" Comparison
A fair comparison requires an "apples-to-apples" look at your coverage. Ensure that the liability limits, accident benefits, and deductibles on your new quote are identical to your current policy. A lower price might simply reflect a higher deductible or lower coverage limits, which could cost you more in the long run. You should also consider the claims reputation of the new partner insurer. Some carriers are more lenient with minor convictions or first-time accidents than others. If you have a clean record, you may be eligible for specific "claim-free" protections that vary by company. Before you sign a new contract, it's helpful to speak with a Markham insurance broker who can explain how different insurers treat your specific driving history. This ensures you aren't just getting a cheaper rate, but a policy that offers the stability you need when it matters most.
The 5-Step Process to Switch Your Auto Policy
Once you've decided to move forward with a new provider, following a structured order of operations is vital for a stress-free transition. In Ontario, maintaining continuous auto insurance is a legal requirement; even a single day of lapsed coverage can lead to higher premiums or limited options in the future. As your Markham-based brokerage, we take the heavy lifting out of this transition by managing the communication between carriers. This ensures your coverage remains seamless as you approach your car insurance renewal ontario date.
Gathering Your Ontario Driving History
Start by gathering your current documentation to ensure your new quotes are accurate. You'll need your existing OAP 1 policy number and the driver's license numbers for everyone in your household. Brokers use specialized Ontario databases to verify your claims history and any past convictions, so having these details ready speeds up the verification process. If you've recently moved to the GTA from another province, you'll also need to request a "Letter of Experience" from your previous insurer. This document proves your history of safe driving and helps us secure the best possible rating for your new policy.
Securing New Coverage Before Cancelling
The most critical part of this process is what we call the "Golden Rule" of insurance: never cancel your existing policy until the new one is officially bound. You want to coordinate the effective date of your new policy to match the expiry of the old one perfectly. In Ontario, policies almost always begin and end at 12:01 AM. By setting your new policy to start at the exact moment the old one expires, you eliminate any risk of being uninsured. Before you send a cancellation request to your current company, confirm that you've received your new digital or physical pink slips. This document is your legal proof of insurance and is an essential part of Understanding Your Auto Insurance Policy and its specific limits.
Finally, you'll need to manage your payment transition. If you use automatic withdrawals (PAP), notify your bank and your old insurer about the change once the new policy is active. It's common for a final payment to be processed if the cancellation happens close to a withdrawal date, but any overpayment will be refunded to you by the insurer. We handle the administrative paperwork to ensure your new provider has the correct banking information, making the switch as frictionless as possible. By following these steps, you can move toward your next renewal with total peace of mind.
Avoiding Common Switching Pitfalls in Ontario
Switching providers requires attention to detail to avoid administrative traps that can cost you more than you save. If you're driving a financed or leased vehicle in the GTA, your lender must be listed as a loss payee or additional insured on your new policy. Failing to update this information can lead to complications with your lease or loan agreement. Similarly, verify that any vehicle modifications are disclosed. Whether you've added a specialized security system or performance upgrades in Markham, your new insurer needs an accurate picture of the vehicle to ensure your claims are handled correctly. When you approach your car insurance renewal ontario, it's the perfect time to audit these details and ensure your records are up to date.
Preventing a Gap in Coverage
Maintaining a clean, continuous insurance record is one of the most effective ways to keep your premiums manageable. A lapse of even twenty-four hours can trigger a re-classification into the high-risk category by many Ontario underwriters. This shift often results in the loss of "continuous insurance" discounts and limits your access to standard market rates. Insurers also look closely at your payment history. If you have a previous cancellation for non-payment on your record, many companies will require you to pay your annual premium in full upfront. Beyond the financial impact, the legal stakes are high. Driving without valid insurance in Ontario is a serious offence. It carries mandatory fines ranging from C$5,000 to C$25,000 for a first conviction, along with a potential license suspension and vehicle impoundment.
Matching Coverage to Your Actual Needs
A common mistake is focusing solely on the premium while overlooking the specific protections that matter in a crisis. While a C$1 million liability limit is a standard starting point, many drivers in Richmond Hill and Toronto choose C$2 million to better protect their personal assets from rising settlement costs. You should also look for essential Ontario endorsements like OPCF 20. This endorsement covers the cost of a rental vehicle while your car is being repaired after a claim, which is vital given the current repair timelines in the GTA. Understanding the distinction between comprehensive and collision coverage is equally important. Collision handles damage from accidents, while comprehensive covers theft, fire, or windshield damage. Ensuring these match your risk tolerance is better than simply chasing the lowest price during your car insurance renewal ontario. A broker acts as your second set of eyes, verifying that your "Loss of Use" limits are sufficient and your deductibles are set at a comfortable level.
How an Ontario Broker Simplifies Your Switch
Dealing with a direct insurer often means you're only seeing a fraction of the available options. A brokerage operates on a fundamentally different model by connecting you to a broad network of partner carriers. This structure ensures that during your car insurance renewal ontario, you aren't limited to a single quote that might not be competitive. We act as your professional advocate, offering a layer of reliability and warmth that transforms a complex transaction into a clear, supportive experience. Our team focuses on providing peace of mind by simplifying the logistics of moving your coverage from one provider to another.
The Advantage of the Brokerage Model
Brokers don't work for the insurance companies; we work for you. By shopping multiple partner carriers, we identify the specific policy that aligns with your household budget and unique risk profile. You receive personalized advice that isn't tied to the sales targets of a single insurance brand. This independence is a cornerstone of smart cheap car insurance Canada strategies, where the priority is finding high-quality coverage at a sustainable price. Beyond the initial switch, a broker remains your point of contact for policy adjustments and claims support, ensuring you never have to face a large corporation alone during a stressful time.
Local Expertise for GTA Drivers
Regional rating factors are incredibly specific in Ontario. A Markham-based team understands why insurance costs in Vaughan or Toronto might differ significantly from those in Richmond Hill or Stouffville. We recognize how local traffic patterns and theft statistics in York Region influence your premiums. By combining this deep local insight with the modern convenience of an online insurance broker Canada, we provide a steady and logical path to better coverage. You get the speed of digital tools backed by the integrity of a neighbor who knows your community and its specific driving challenges.
At Verdant Insurance, we take pride in being a proactive guide for drivers across the GTA. We specialize in identifying savings for claim-free and conviction-free drivers, often uncovering discounts that direct insurers might not mention. Our mission is to make your next car insurance renewal ontario feel entirely frictionless. We handle the market research, manage the administrative paperwork, and facilitate the transition between carriers so you can enjoy the security you deserve. If you're ready to explore your options before your next renewal date, we invite you to speak with a Verdant broker for a personalized policy review.
Taking the Next Step Toward Peace of Mind
Switching doesn't have to be a source of stress. By aligning your move with your next car insurance renewal ontario date, you avoid unnecessary administrative fees and ensure a seamless transition between providers. It's about more than just a lower monthly bill; it's about finding a policy that truly reflects your actual life in the GTA. As a Markham-based brokerage, we offer personalized service and access to multiple leading insurance carriers. We specialize in identifying substantial savings for safe drivers, with discounts of up to 30% available for those who are claim-free and conviction-free.
You deserve an insurance partner that prioritizes your security and simplifies every complex detail. We're ready to help you navigate the 2026 regulatory changes with confidence and clarity. Whether you're in Markham, Vaughan, or Toronto, our team is here to support your needs. Your path to better value and reliable protection starts with a simple, supportive conversation. We look forward to helping you feel secure and well-cared for on the road ahead.
Frequently Asked Questions
Can I switch car insurance companies at any time in Ontario?
You can switch car insurance companies at any time in Ontario, as you aren't legally bound to stay with one provider for the full term. While you have the freedom to move whenever you find a better fit, the timing affects your costs. Cancelling mid-term often triggers administrative fees, whereas switching during your car insurance renewal ontario window allows for a clean break without penalties. We recommend reviewing your options thirty days before your current policy expires.
Will I be charged a fee for switching my car insurance mid-term?
Most private insurers in Ontario apply a "short-rate" cancellation fee if you terminate your policy before the expiry date. This fee isn't a flat rate; it's a percentage of your remaining premium used to cover the company's administrative expenses. The penalty is typically higher if you cancel very early in the policy term. To avoid these costs, many drivers wait until their renewal date, where a pro-rata cancellation allows them to leave without any extra charges.
Does switching car insurance companies affect my driving record or credit score?
Switching providers has no impact on your official Ontario driving record, as your claims and conviction history remain with you regardless of your insurer. Regarding your credit score, most insurers perform a "soft" credit check to determine eligibility for certain payment plans or discounts. Unlike a "hard" pull used for loans, a soft inquiry doesn't lower your credit score. It's a standard part of the quoting process that helps brokers find the most accurate rates for your profile.
How much notice do I need to give my current insurer before switching?
There is no specific legal minimum for notice, but providing at least thirty days is highly recommended. This window aligns with when you receive your renewal offer, giving you enough time to compare quotes and secure new coverage. Since Ontario law requires continuous insurance, you must have your new policy "bound" and active before you send the final cancellation notice. A broker can coordinate this timeline to ensure you don't face a single day without protection.
Is it better to switch car insurance at my renewal date?
It is almost always better to switch at your car insurance renewal ontario date to avoid short-rate cancellation penalties. By waiting for the policy to expire naturally, you ensure a pro-rata cancellation, meaning you only paid for the days you were covered. However, if you've recently moved to a lower-rated area like Markham or reached a major claim-free milestone, the potential savings with a new provider might outweigh the mid-term fee. A broker can help you calculate the break-even point.
Can a broker help me switch my car insurance if I have an open claim?
You can still switch insurers with an open claim, but it requires careful handling. Your current insurer will continue to manage and pay out the existing claim until it's resolved, even after you move your policy elsewhere. However, an open claim might affect your eligibility or rates with new carriers. As a brokerage, we work with multiple partner carriers to find those who are most receptive to your situation, ensuring you still have access to competitive options during the transition.
What happens to my multi-policy discount if I only switch my auto insurance?
If you move your auto insurance but keep your home or tenant policy with the original company, you will likely lose the multi-policy discount on that remaining line. This often leads to a premium increase for your home insurance. To prevent this, we usually recommend moving all your policies together. Bundling auto, home, and tenant insurance under one brokerage platform not only simplifies your management but often unlocks deeper discounts that offset the cost of the move.
How do I get my new pink slip after switching insurers?
Your new insurer or broker will provide your pink slips immediately after your policy is "bound" or officially activated. Most providers now offer digital pink slips that you can store on your smartphone; these are legally accepted in Ontario. You can also request a physical copy to be sent via mail to your home in the GTA. It's essential to have this document ready before your new policy's effective date, as it serves as your legal proof of insurance.


