
The city where you insure your vehicle can be just as important as the badge on its grille. Luxury car insurance costs in Ontario depend on factors such as where you live, your driving history, the vehicle’s repair and theft risks, and the coverage you choose. To bring your premium down, focus on the details you can influence, including your driving record, annual mileage, deductible and anti-theft protections.
It’s understandable to expect a high-performance or high-value car to cost more to insure. But the make and model are only part of the picture: two drivers insuring similar vehicles can receive very different quotes, and rates can vary between Ontario cities. A lower premium also needs to be weighed against the coverage and out-of-pocket costs you’d face after a claim.
This guide compares how location and driver profiles can affect luxury-car premiums, explains what insurers consider, and outlines practical ways to manage costs without overlooking protection. You’ll also find a straightforward decision guide to help you compare options based on your vehicle, driving habits and coverage priorities.
Key Takeaways
- See how premiums for luxury vehicles can vary with the model, repair costs, theft risk and the coverage selected.
- Compare Ontario city estimates with care: the driver and vehicle assumptions behind each figure matter.
- Learn why driving history and other personal details can lead to different quotes for the same vehicle.
- Explore practical ways to manage premiums, including reviewing mileage, deductibles and anti-theft measures.
- Use the decision guide to weigh price against the protection and repair options that matter for your car.
How much does luxury car insurance cost in Ontario?
Luxury vehicle premiums in Ontario vary with the car, driver, location and coverage. Toronto examples show how the same vehicle can receive different annual quotes when driver details change.
Sample Driver and Vehicle Estimates
These are sample quotes, not prices for every driver or policy.
| Option | Driver profile | Vehicle | Quoted annual premium |
|---|---|---|---|
| Sample A | 42-year-old, married, one minor ticket | 2021 Mercedes-Benz GLC43 | |
| Sample B | 34-year-old, divorced, one minor ticket, one at-fault incident | 2021 Mercedes-Benz GLC43 |
Choose comparisons with matching driver details, vehicle and coverage, then assess the deductible alongside the premium.
Luxury Vehicle Eligibility and Value
That threshold is a guide, not a universal eligibility rule: insurers may also weigh the vehicle’s year, make, model, performance, uniqueness, value, and maintenance and repair costs.
For example, a high-value Lexus and a distinctive Ferrari can differ in performance and repair needs, even if both meet the value threshold. A clean driving record describes the driver’s history; it does not, by itself, determine whether a vehicle qualifies.
Model and Theft Premium Differences
Model-specific quotes demonstrate why a luxury badge alone doesn’t predict a premium. In the 42-year-old Toronto sample, the Lexus RX450h quote was C$2,069, compared with for the Mercedes-Benz GLC43. A different driver profile shifted both prices substantially.
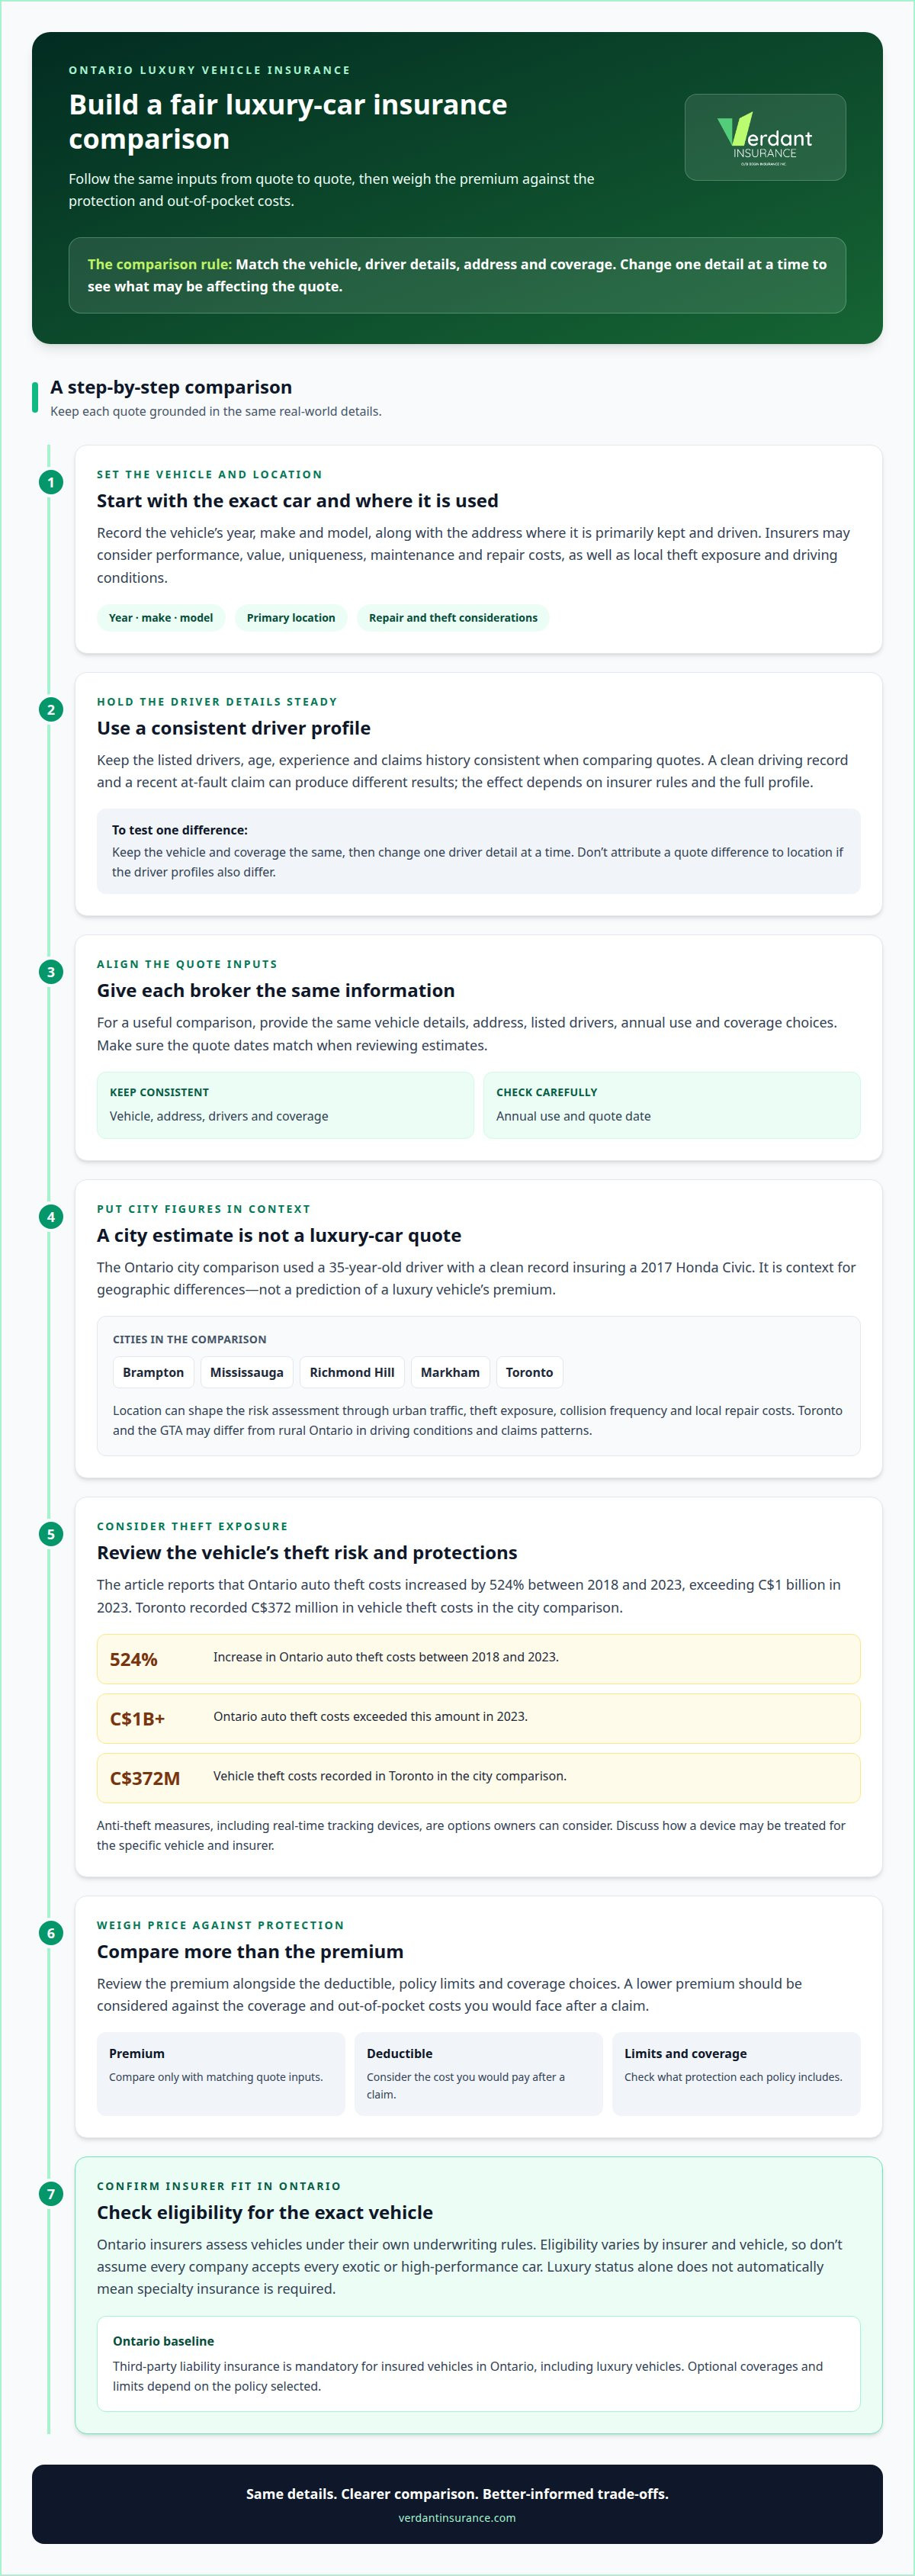
Theft exposure also matters. Ontario’s auto theft costs increased by 524% between 2018 and 2023, exceeding C$1 billion in 2023; Toronto recorded C$372 million in vehicle theft costs in the city comparison. Anti-theft devices, including real-time tracking devices, are one measure owners can consider.
Insurers for High-Value Vehicles
Which Ontario insurers offer coverage for luxury and high-value vehicles? Coverage is available through Ontario auto insurers that accept the specific vehicle under their underwriting rules; eligibility varies by insurer and vehicle. Compare the insurer’s terms for the exact year, make and model rather than assuming every company accepts every exotic car.
Do luxury, exotic, or high-performance cars require specialty insurance in Ontario? Not solely because of their category: the vehicle’s value, performance, repair needs and insurer eligibility help determine the appropriate policy. Alberta insurance terms don’t determine Ontario requirements.
Ontario’s mandatory auto insurance requirements apply to luxury vehicles as they do to other insured vehicles; third-party liability insurance is mandatory. The vehicle’s luxury status does not remove that requirement, while optional coverages and limits depend on the policy selected.
Which cities in Ontario have the most expensive car insurance rates?
City comparisons show where premiums can be higher, but they don’t predict a luxury-car quote on their own. That estimate used a 35-year-old driver with a clean record insuring a 2017 Honda Civic, not a luxury vehicle.
| City | Estimated annual premium | What the comparison represents |
|---|---|---|
| Brampton | 2017 Honda Civic, 35-year-old driver with clean record | |
| Mississauga | Same driver and vehicle assumptions | |
| Richmond Hill | Same driver and vehicle assumptions | |
| Markham | Same driver and vehicle assumptions | |
| Toronto | Same driver and vehicle assumptions |
These city estimates help illustrate geographic differences, not today’s luxury-car rates. The vehicle, coverage, driver details and quote date must match before comparing insurance quotes meaningfully.
How Location Shapes Premiums
Insurance companies assess where a vehicle is primarily kept and driven. Urban traffic, theft exposure, collision frequency and local repair costs can influence the risk picture. Toronto and the GTA also differ from rural Ontario in driving conditions and claims patterns, so a city-wide estimate shouldn’t be treated as a personal premium.
Hamilton illustrates another regional factor: industrial traffic, congestion on the QEW and Highway 403, and mixed urban-suburban driving conditions. For a luxury vehicle, repair costs and theft exposure can add further considerations to the local risk assessment.
Compare Driver Profiles and Claims History
A useful comparison holds the vehicle and coverage constant, then changes one driver detail at a time. For example, the city estimates above use a clean-record driver; they don’t show how the same vehicle would rate for someone with tickets or an at-fault accident. Age, experience, listed drivers and claims history can all affect how insurance companies assess a quote.
Claims history matters because insurers consider past losses when assessing future risk. A recent at-fault claim can produce a different result from a claim-free record, while the effect depends on insurer rules and the full driver profile. Don’t compare a clean-record quote with one that includes an accident as if location alone caused the difference.
Make Quote Comparisons Useful
For a fair comparison, provide each insurance broker with the same vehicle details, address, listed drivers, annual use and coverage choices. Then compare the premium alongside the deductible and policy limits. Installing an anti-theft device may also be worth discussing for a high-value vehicle, since theft risk can influence pricing.
Use city figures as context, not a shortcut: the clearest comparison comes from matching vehicle and driver details across quotes.
Luxury car insurance costs and premiums
Luxury vehicle rates can be higher, but the difference depends on the vehicle, driver, location and coverage.
How do luxury car insurance rates compare with standard car insurance in Ontario? Luxury vehicles can cost more to insure because their value, repair costs and theft exposure affect potential claims. The actual difference depends on the vehicle and driver profile.
Ontario Average Auto Premiums
The provincial typical-vehicle range offers a useful baseline, not a luxury-car quote. Rural Ontario averaged 21.1% below the provincial figure, while other urban areas averaged 4.4% below it.
These estimates reflect regional differences, not a guaranteed premium for a particular driver. Toronto’s GTA location, vehicle and coverage can all affect an individual quote.
Luxury SUV Premium Comparisons
Luxury SUVs can vary substantially by make and model. These figures show brand-level differences, not a matched quote comparison for identical drivers, coverage and vehicles.
For an SUV comparison, line up the same driver details, location, coverage limits and deductible. Then compare the quoted premium with the vehicle’s value and likely repair needs.
Luxury and Standard Car Insurance
Standard-vehicle averages help set context, but they don’t account for the higher replacement or repair costs associated with some luxury cars. It should not be treated as the expected premium for every luxury model.
Model-level factors matter: vehicle value, performance, parts and repair expertise can affect the insurer’s assessment. A Toronto driver’s quote may also differ from a rural Ontario quote, even for the same car.
Drivers can review practical choices that may affect premiums. Paying annually rather than monthly, choosing a higher deductible, driving fewer kilometres, maintaining a clean record and comparing quotes can help manage costs. A higher deductible means paying more out of pocket for a covered claim, so weigh that trade-off against the premium.
Bundling auto and home policies may also affect the total cost, depending on the insurer’s terms. Compare the combined premium and coverage rather than focusing on a possible discount alone. Claims history, annual driving and the vehicle’s repair profile remain important parts of the assessment.
Driver demographics and insurance rates
Driver information helps insurers assess who will use a luxury vehicle and how it fits the household’s driving needs. A quote can change if the principal operator is identified incorrectly or a regular driver is left off the application. Before comparing insurance rates, make sure each quote reflects the same people and the same roles.
| Profile detail | What to clarify | Why it matters to a comparison |
|---|---|---|
| Principal operator | Who drives the vehicle most often? | Quotes should identify the same primary user. |
| Other household drivers | Who may use the vehicle regularly? | Different listed drivers can change the risk profile. |
| Licence experience | What licence class and driving experience apply? | Driver experience forms part of the profile insurers assess. |
| Vehicle use | Is it used for regular commuting, occasional trips, or another purpose? | Usage details should be consistent across quotes. |
Age and marital status may also appear in a quote application. Treat these as profile details to report accurately, not as a simple formula for predicting a premium. Insurers use their own rating approaches, and the impact of each detail can differ between companies.
Licence experience deserves careful attention in households with new drivers. If a newly licensed or G2 driver may use the luxury car, include that information when requesting quotes. Don’t assume a driver’s occasional use makes the detail irrelevant. Accurate information gives the insurer a clearer picture of the household and helps avoid comparing quotes built on different assumptions.
A driving record should also be reviewed for accuracy. Gather the relevant driver and vehicle details before starting an application, and answer questions consistently. If the vehicle changes hands or household driving arrangements shift, update the information used for the policy discussion rather than relying on an earlier quote.
For a practical comparison, prepare these details first:
- Each driver’s role and licence experience.
- Who regularly uses the vehicle and for what purpose.
- Any recent change in household drivers or vehicle use.
- The same vehicle information for every quote request.
An Ontario insurance broker can help you find comparable options and explain how insurers treated the details you provided. Ask what information distinguishes the quotes, then check that each option reflects the actual drivers and intended use. This makes the comparison more useful than choosing a rate based on demographic labels alone.
Most expensive Ontario cities for auto insurance
Ontario’s city estimates show that premiums aren’t highest only in the Greater Toronto Area. These figures offer another perspective on how location can shape auto insurance costs across the province.
| Ontario city | Estimated annual premium | Estimate year |
|---|---|---|
| London | $1,850 | 2020 |
| Windsor | $1,980 | 2020 |
| Kitchener | $1,720 | 2020 |
| Ottawa | $1,450 | 2020 |
The comparison used a 35-year-old driver with a clean driving record insuring a 2017 Honda Civic. It isn’t a luxury-vehicle rate table. Use it to understand the comparison’s assumptions, not to estimate what a current luxury-car policy will cost in any of those cities.
City estimates can also change with the basis of comparison. Those are different comparison figures from the 2020 estimates above, so they shouldn’t be combined into one ranking or treated as current quotes.
For a luxury vehicle, when analyzing luxury car insurance costs Ontario drivers must factor in the address where the car is usually kept. Keep the model, year, drivers, coverage and deductible consistent across quotes. Then note each quote’s date and assumptions. This makes it easier to distinguish location-related variation from differences in vehicle or policy details.
Before choosing a policy, compare more than the headline insurance rate. Check that each quote reflects the same coverage limits, optional protections and deductible. A lower figure may reflect different coverage rather than a more suitable policy. If the vehicle is stolen or involved in a collision, the policy wording and selected protections determine what applies.
Use city estimates as context, then base your decision on comparable quotes for your actual vehicle and address. This approach is more useful than assuming one Ontario city always has the highest rate for every driver.
Verdant Insurance: Auto Insurance
Verdant Insurance can help Ontario drivers compare auto insurance options for a luxury vehicle. As a brokerage, it can help you review quotes and consider how the vehicle, listed drivers, location, deductible and coverage choices affect the policy.
This can be useful when you’re buying a high-value car, renewing after a change in driving history, or comparing coverage for a vehicle with specialized repair needs. Premiums and eligibility vary by insurer and individual circumstances; policy wording, limits and exclusions also shape the protection available.
To discuss auto insurance for your vehicle, contact Verdant Insurance or visit verdantinsurance.com.
Make your next insurance review count
Use your next renewal or vehicle purchase as a chance to reassess what protection matters most. Consider how you use the car, who drives it, where it’s kept, and what repair arrangements you’d want after a loss. These priorities can help focus a conversation about coverage instead of choosing on premium alone.
Understanding luxury car insurance costs in Ontario is one part of protecting a high-value vehicle. The next step is to compare policy details against your needs, including limits, deductibles and applicable exclusions. Verdant Insurance offers Auto Insurance, Homeowner Insurance and Business Insurance, supporting insurance discussions around your vehicle and other property needs.
For a personal review of your Ontario auto insurance options, reach out to Verdant Insurance.
A clear comparison can help you move forward with confidence and make an informed choice for your vehicle.
Frequently Asked Questions
How can I save on exotic car insurance in Ontario?
Start before buying the car: request a quote for the exact vehicle, trim and intended use. Luxury car insurance costs in Ontario can differ between insurers for the same vehicle and driver, so compare the policy details as well as the premium. If you already own the car, review your renewal documents and correct outdated driver, vehicle-use or mileage details before requesting updated quotes.
Do large cities have higher rates?
City averages may be higher in some urban areas, but they don’t mean every resident pays more than every rural driver. A citywide figure groups different vehicles, drivers and policies together. For a useful personal comparison, use the address where the vehicle is normally kept and the same policy details across quotes. An affluent neighbourhood name alone doesn’t establish an individual insurance rate.
How much to insure these luxury vehicles in Toronto’s most affluent neighbourhoods?
There isn’t one premium that applies to Toronto’s affluent neighbourhoods. A quote needs the specific vehicle and the address where it is kept, along with driver and policy information. If the vehicle is parked at a different location than the driver’s home, provide accurate details for its usual location. This helps avoid relying on a neighbourhood-level estimate that may not match the actual risk information.
What are some specifics of luxury car insurance coverage?
Before choosing optional protections, ask how a total-loss settlement is valued and what conditions apply to agreed value or a waiver of depreciation. For repair coverage, clarify whether original equipment manufacturer parts and a preferred repair facility are options under that policy. Loss-of-use and rental-car coverage also have policy terms. Compare the written limits, triggers and exclusions rather than relying on a coverage label alone.
What is the average cost of luxury car insurance in Ontario per year?
No single annual average represents every luxury car and driver in Ontario. Published estimates can use different vehicle models, locations, coverage and driver profiles, making a simple average a poor guide for an individual budget. For a relevant figure, request a quote for the exact vehicle and intended policy. Treat a general market estimate as context, not as a price you should expect to receive.
How much does insurance cost for popular luxury car models in Ontario?
There isn’t one price for a model across Ontario. Even the same model name can refer to different years, trims and powertrains, so identify the exact version before comparing premiums. If you’re shopping for a vehicle, get a quote before completing the purchase. Keep the policy details consistent when comparing models, and note the quote date so later comparisons use the same basis.
What factors affect luxury car insurance rates in Ontario?
Insurers consider the vehicle and driver information provided, along with their own rating factors. Changes can matter at renewal: moving, adding a household driver, changing how the vehicle is used, or replacing the car may alter the information insurers assess. Tell the insurer about relevant changes rather than assuming an older quote still reflects your situation. Eligibility and pricing depend on the insurer’s assessment.
What coverage limits and optional protections are recommended for luxury cars in Ontario?
Ontario providers recommend at least C$1 million in third-party liability coverage for luxury vehicles, and often C$2 million or more. Liability coverage addresses claims made against you; it isn’t the same as protection for damage to your own vehicle. Consider collision and comprehensive alongside optional protections, then compare their limits and exclusions. The policy wording determines how each protection applies to a covered claim.


