

To understand how to get cheap car insurance in Brampton, compare quotes with the same coverage details, then consider how your postal code, deductible, driving history, vehicle, and licensing experience affect your options.
It’s understandable to want a clear price before comparing policies, especially when Brampton rates can differ from other parts of Ontario. A postal-area figure can’t predict your own premium, so focus on the factors insurers consider and compare quotes that reflect your circumstances.
This guide explains how Brampton costs compare across Ontario and why your location within the city can matter. You’ll learn how deductibles, driving and licensing history, and coverage choices affect comparisons. With those details in hand, you can make an informed decision without sacrificing protection just to chase a lower price.
Key Takeaways
- Compare quotes using the same coverage details so you can judge differences more fairly.
- Your Brampton postal code can affect the premium, so consider location alongside your driving history and vehicle.
- A higher deductible may lower your premium, but it also means paying more out of pocket after a claim.
- Review your licensing and driving history when comparing options, as these details can influence available rates.
- A broker can help you compare auto insurance options and understand the trade-offs that fit your needs.
Why is comparing car insurance quotes particularly important for Brampton drivers?
Brampton premiums are higher than Ontario and GTA averages, but individual quotes vary. Compare equivalent coverage and policy details to see how your circumstances affect the price.
The figures use different periods and measurements, so treat them as comparisons, not a personal quote.
A median is the midpoint of quoted premiums, not the amount every driver pays. The difference between average and median figures shows why a headline rate can’t predict an individual premium. Compare quotes with matching coverage, vehicles, and driver details for a more useful picture.
Postal Code Premium Differences
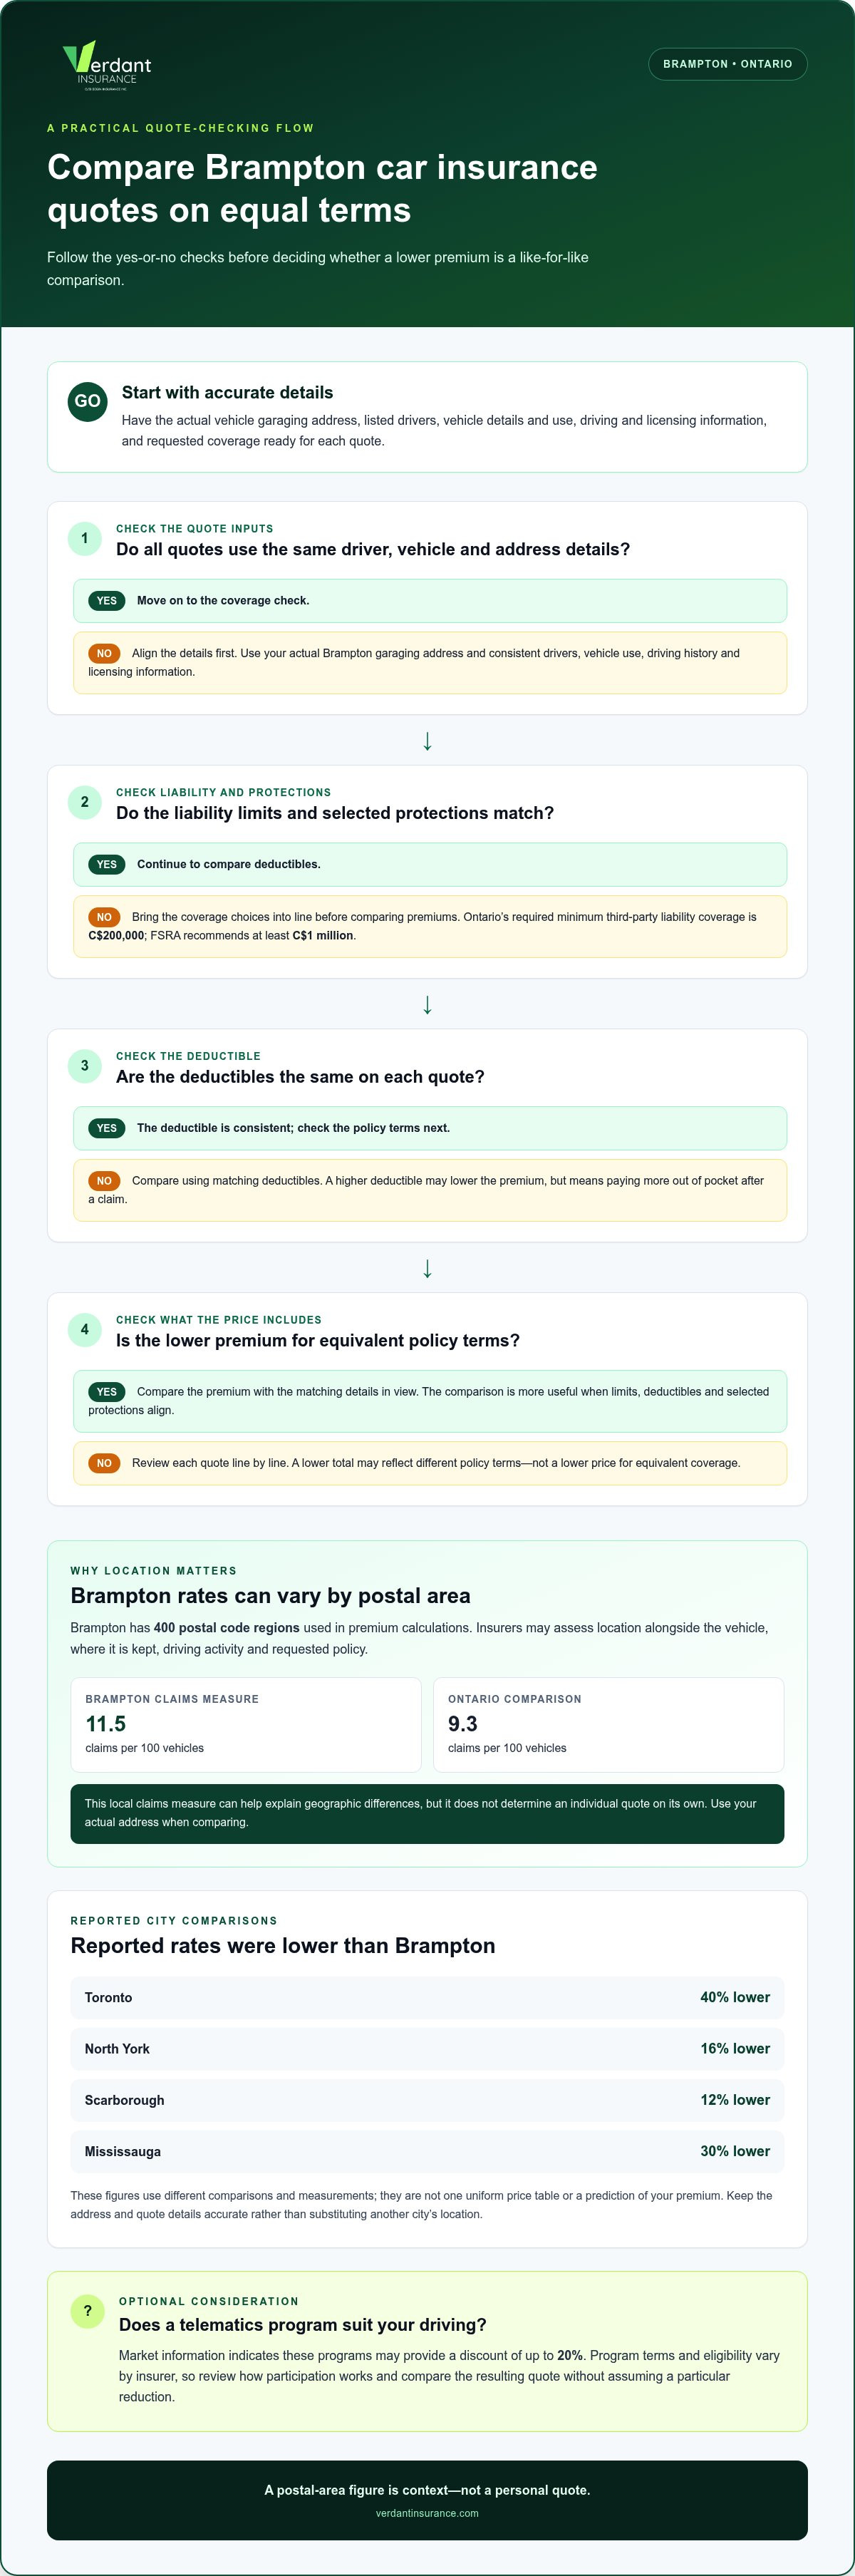
Location within Brampton can affect an auto insurance rate. Brampton has 400 postal code regions used in premium calculations, and listed postal areas show different results. Compare the same type of figure and period, rather than treating averages and medians as equivalent.
Factors Behind Premium Costs
Insurers assess details such as where a vehicle is kept, the vehicle itself, driving activity, and the requested insurance policy. Brampton recorded 11.5 claims per 100 vehicles, compared with Ontario’s 9.3. That local claims measure is one reason premiums can differ by location, but it doesn’t determine an individual quote on its own. Compare quotes with consistent coverage and vehicle information to understand how each insurer weighs your profile.
Driving History and Premiums
Driving records can create substantial differences between Brampton premiums. These examples show why quote comparisons should use accurate, consistent driver details.
Before comparing, gather each driver’s licensing and driving information, vehicle details, postal code, and preferred coverage. Request quotes using the same limits and deductibles. A lower premium may reflect different policy terms, so compare what each policy includes, not just its total cost. This helps Brampton drivers judge whether a price difference reflects their profile or a change in coverage.
Brampton insurance costs compared with other Ontario cities
Ontario’s minimum required third-party liability coverage is C$200,000. City comparisons help put local insurance costs in context, but use matching coverage and driver details for meaningful quote comparisons.
Rates Across Ontario Cities
Reported rates and estimated annual quotes place Brampton above several Ontario cities. Rates in Toronto are 40% lower than in Brampton, while North York rates are 16% lower.
These city figures reflect different comparisons and shouldn’t be treated as one uniform price table. A median premium and an estimated quote are different measures. Compare figures only when their periods, coverage, and driver profiles align.
Rates in Nearby Cities
Nearby-city comparisons also show geographic variation. Rates in Scarborough are 12% lower than in Brampton, and Mississauga rates are 30% lower. These figures use different measures, so avoid reading the percentages and medians as directly interchangeable.
For a useful local comparison, keep your postal code, vehicles, driving history, and requested coverage consistent across quotes. Changing the listed address to another city won’t create a valid comparison if the vehicle is kept in Brampton. Location is one rating factor, not a substitute for accurate application details.
Quote and Coverage Comparisons
Compare quotes line by line, including liability limits, deductibles, and selected protections. A lower total can reflect a different insurance policy rather than a better price for equivalent coverage. Start with the C$200,000 legal minimum for third-party liability, then assess whether your needs call for higher limits. Ontario’s Financial Services Regulatory Authority recommends at least C$1 million in third-party liability coverage.
Driving history and vehicle details also affect comparisons. Request quotes using the same drivers, vehicle use, address, and coverage choices. Check that each quote has matching limits and deductibles before comparing premiums. This makes differences easier to identify without judging coverage by price alone.
Insurance prices across provinces aren’t directly comparable because provincial rules and insurance systems differ. If you compare an Ontario quote with an estimate from another province, separate regulatory and coverage differences from the premium itself. For Ontario decisions, focus on comparable quotes from cities relevant to your commute, residence, or vehicle use, while keeping required liability coverage in view.
Which Brampton postal codes have the cheapest car insurance?
No Brampton postal code guarantees the lowest car insurance rate for every driver. Insurers assess location alongside vehicle and driver details. For a fair comparison, use your actual garaging address and request quotes with consistent coverage, deductibles, and listed drivers. When considering how to get cheap car insurance in Brampton, accurate address details are more useful than choosing a postal area based on a general ranking.
Postal-area estimates offer context, but they don’t predict an individual premium. A city may include areas with different claims patterns, which insurers may assess differently. Focus on quotes calculated for your address rather than assuming a nearby postal code will produce the same rate. If you move within Brampton, update your address and compare policy terms using the new location.
Telematics is another option to consider. These programs assess driving activity, and market information indicates that they may provide a discount of up to 20%. Program terms and eligibility vary by insurer, so understand how participation works before comparing the resulting quote. The point is to assess whether the program suits your driving, not to assume a particular reduction in your premium.
Placing auto and property insurance with the same insurer may qualify for a multi-policy discount. Compare the total cost and policy details with separate quotes, and check that the coverage and deductibles suit each need. A combined price is useful only when you understand what each policy includes and how the insurer applies its terms. Eligibility and discount amounts vary by insurer.
PC Optimum membership alone doesn’t establish that a particular insurance offer applies. Treat an affinity offer as a specific quote detail: compare its stated eligibility and terms with the full premium and policy wording. Don’t assume membership automatically changes your car insurance rate. Apply the same care to other promotions, since discounts and eligibility can vary by insurer and province.
Driving history remains relevant when insurers assess risk. Accidents and convictions may affect a quote, and Ontario Highway Traffic Act convictions remain on a driver’s record for six years. Provide accurate history when comparing offers, then note how each quote reflects it. Don’t assume you qualify for a conviction-free discount, since eligibility depends on insurer rules.
When discussing options with an insurance broker, have your Brampton address, vehicle details, driving history, and coverage preferences ready. Ask for comparisons based on matching details, and review the terms of any telematics program or bundle. This helps you assess potential savings while keeping the comparison grounded in your circumstances.
Average monthly and annual insurance costs
Monthly and annual figures show different ways to pay, not different measures of driving risk. Compare annual totals across quotes, then review each policy’s payment schedule and term. A monthly payment may be easier to budget, but it doesn’t show the full annual cost on its own. Keep coverage, deductibles, listed drivers, and vehicles consistent so the comparison reflects more than payment timing.
Vehicle choice can make a noticeable difference in quoted costs. These are estimates for profiled vehicles, not prices every owner will receive. The driver’s record, address, vehicle use, and selected coverage also shape the quote.
Use vehicle-specific estimates as a planning prompt before buying, not as a substitute for a quote based on your details. For instance, a Brampton driver comparing a Civic with a RAV4 can request estimates for both before choosing. The difference between sample figures illustrates why the model matters, but it doesn’t establish which vehicle will cost less to insure for every driver.
Driving patterns matter too. Insurers consider vehicle use and driving activity, so accurately describe whether a vehicle is used for commuting, work, or occasional trips. If your routine changes, such as driving less often, update the information used for future quotes. Compare quotes using the same stated use so a change in driving details isn’t mistaken for a difference in insurer pricing.
Coverage selections can change the comparison as well. Ontario’s accident-benefit choices changed on July 1, 2026, when some benefits that were previously mandatory became optional. Review the benefits shown in each quote, along with limits and deductibles. A smaller premium may reflect different selections, not a better price for identical protection. Read the policy wording before deciding what fits your needs.
For a practical review, gather your vehicle details, Brampton address, driver information, intended use, and coverage choices. Request quotes using the same information, then compare annual totals and payment schedules. Insurers may price the same driver and vehicle differently, so review the complete quote rather than relying on one monthly figure. This helps separate differences tied to the vehicle, insurer, or policy terms.
Deductibles and driver licensing
A deductible affects what you pay after a covered claim, while licensing details help insurers assess the driver. Compare both across car insurance quotes. A lower premium may come with a higher deductible, so weigh the potential savings against what you could pay yourself after damage or theft. Choose an amount that fits your budget without assuming a claim will happen.
Increasing a deductible to C$1,000 or more can reduce the premium, but raises your out-of-pocket cost after a claim. For example, if you select a C$1,000 deductible, you must be prepared to pay that amount when it applies to a covered loss. The policy’s wording, limits, and exclusions determine how a claim is handled. Review those details alongside any quoted premium.
Consider repair costs before raising your deductible. A driver who depends on a vehicle for daily travel may prefer a lower amount to pay after a claim, even if the premium is higher. Someone with enough funds set aside may accept a larger deductible for a lower quoted premium. These are budgeting trade-offs, not guaranteed savings.
Licensing experience can also shape a quote. Insurers assess the driver information provided, including licensing and driving history, and their rating approaches vary. A newly licensed driver may receive a different quote from a driver with a longer record. Brampton drivers should enter each driver’s licence details accurately and compare offers using the same household drivers and vehicles.
Use this simple comparison process:
- Request quotes with matching drivers, vehicles, and coverage.
- Compare the deductible listed for each policy and note where it applies.
- Review the premium difference alongside the amount you would pay after a claim.
- Check that every driver’s licensing details and driving record are accurate.
Don’t choose a deductible based only on the annual premium. Consider whether you could cover that amount while managing a repair or other expenses. Then compare the same deductible across quotes. If an offer changes the deductible or coverage, note the difference before judging its price. This keeps the comparison focused on similar policies.
Give licensing details the same care as deductible choices. Provide accurate information for each driver, and update it when household drivers or vehicles change. A quote based on incomplete details may not reflect the policy you need. Before choosing, read the policy documents and compare the deductible, coverage, and premium together. These steps help Brampton drivers weigh upfront cost against potential claim expenses.
Verdant Insurance: Auto Insurance
Verdant Insurance is an Ontario brokerage that helps drivers explore Auto Insurance options suited to their needs. If you’ve compared Brampton quotes and want help reviewing coverage, deductibles, and driver details, a broker can help you understand the choices and how they affect a policy. Pricing and eligibility vary by insurer and individual circumstances, so compare the policy wording and limits as well as the premium. Verdant also provides online tools to obtain quotes and manage policies. For a clearer next step, contact Verdant Insurance to discuss your Ontario auto insurance needs.
Make your next insurance review count
Treat each quote as a decision about both cost and protection. Note the coverage, deductible, listed drivers, and vehicle details you want to compare. This gives you a consistent starting point when your circumstances change, such as moving, replacing a vehicle, or adding a driver. The most useful approach to how to get cheap car insurance in Brampton is to compare options carefully, not focus on a low premium in isolation.
Verdant Insurance offers Home Insurance and Business Insurance alongside auto coverage. If your insurance needs extend beyond your vehicle, you can consider those options as part of a broader review. Quotes are free, and final pricing and eligibility depend on the insurer and your circumstances.
With accurate details and a clear comparison, you can take your next step with greater confidence.
Frequently Asked Questions
How much does car insurance cost in Brampton in 2026?
Treat that as a market benchmark, not a quote for your household. Your estimate can differ based on the vehicle, address, listed drivers, annual kilometres, driving record, and selected coverage. For a useful comparison, request quotes with the same details and policy choices, then compare annual totals and terms.
Does car theft increase car insurance rates in Brampton?
Vehicle theft can affect how an insurer assesses a vehicle and its location, but the effect isn’t the same for every policy. Insurers also consider vehicle details, claims history, and other rating factors. If you’re choosing a vehicle, compare insurance estimates before buying it. Ask how the specific model and your Brampton address affect the quote, rather than assuming every vehicle faces the same theft-related impact.
Why are Brampton’s premiums so steep?
Brampton premiums reflect local insurance risk patterns, including claims frequency and claim costs. The average Brampton insurance claim is C$14,800, compared with C$11,500 for the rest of Ontario. Insurers combine local experience with details about each driver, vehicle, and policy. That means two neighbours can receive different quotes, even with the same postal area, if their vehicles, records, or coverage choices differ.
How can I lower my car insurance rate in Brampton?
Start by checking whether your quote reflects your current driving routine, vehicle, and household drivers. If you drive less than before, provide updated mileage and vehicle-use details, since insurers consider driving activity. You can also compare telematics options or ask whether placing auto and property insurance with the same insurer may qualify for a multi-policy discount. Review the terms and total cost, as eligibility and discount amounts vary by insurer.
What is the average cost of car insurance in Brampton, Ontario, in 2026?
A median is the midpoint of premiums in a group, with half above it and half below. It differs from an average, which combines the values across a group. Use the median to understand a typical market position, then compare it with quotes based on your own details.
Which factors make car insurance rates higher in Brampton?
A higher quote may reflect a driver’s experience, driving record, vehicle, address, annual distance, use, claims history, or selected coverage. For example, a vehicle used for regular commuting may be rated differently from one driven occasionally. Insurer-specific rating methods also matter. When reviewing an increase, compare current and previous policy details to identify changes in drivers, vehicles, use, or coverage.
Which Ontario insurers offer the cheapest car insurance quotes in Brampton?
No single insurer is cheapest for every Brampton driver. Companies weigh driver, vehicle, location, and coverage details differently, so the lowest quote for one profile may not be the lowest for another. Compare multiple quotes using consistent information, and review limits, deductibles, and policy wording alongside the premium. An insurance broker can help compare options from insurers available for your circumstances.
How can drivers compare car insurance quotes in Brampton?
Give each insurer the same information, including vehicle identification details, principal driver, other household drivers, address, annual distance, and intended vehicle use. Set matching liability limits, deductibles, and optional coverage before comparing totals. Check the policy start date and payment schedule too. If a quote differs, look for changes in details or coverage rather than judging the premium alone.


